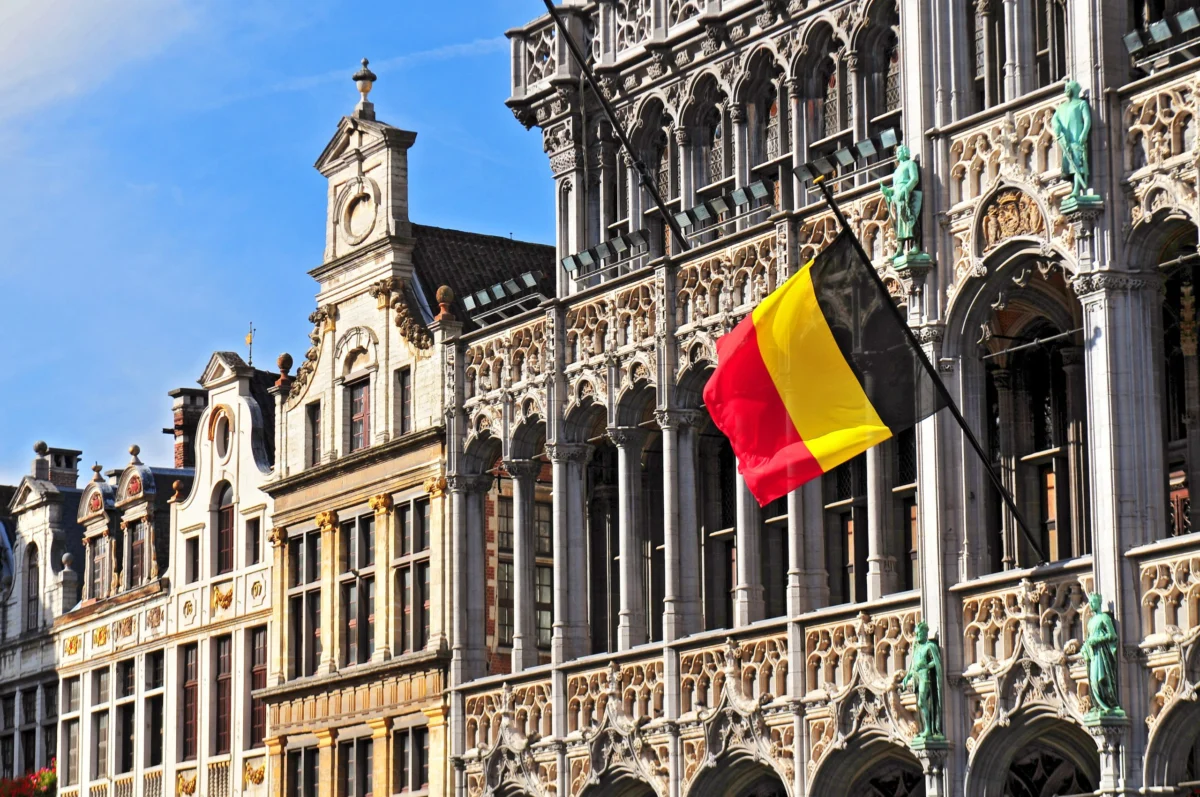
BRUSSELS — As global economies grapple with the rapid digitalization of commerce, governments are scrambling to capture tax revenues from companies that operate across borders without a physical footprint. In Belgium, a major legislative push is underway to adapt the nation’s corporate income tax (CIT) framework to the realities of the modern digital economy.
However, according to economic experts, the proposal may do more harm than good, introducing severe economic distortions, risking international trade retaliation, and ultimately penalizing local consumers and small businesses.
The following report provides a detailed examination of the Belgian legislative proposal, its chronological background, supporting empirical data, official commentary, and its wide-ranging economic implications.
Chronology of Events
The debate surrounding digital taxation in Belgium and the wider European landscape did not materialize overnight. It is part of a decade-long international struggle to reconcile 20th-century tax frameworks with 21st-century business models.
- 2013–2020: The rise of cross-border digital tech giants prompts various European nations to question the traditional "physical presence" requirements for corporate taxation. Major economies begin unilaterally adopting Digital Services Taxes (DSTs).
- May 2026: The Belgian government introduces a landmark legislative proposal designed to overhaul its corporate income tax system. Instead of labeling it an explicit DST, the proposal creates a "Digital Permanent Establishment" (DPE), establishes user-based revenue allocation rules, applies deemed profit margins, and introduces a digital withholding tax.
- August 31, 2026: Cristina Enache, an economist specializing in global tax policy, submits formal written testimony to the Belgian Finance and Budget Committee, warning that the proposal functions as a DST in disguise and carries profound economic risks.
- Late 2026: International economic bodies, including the IMF and the Tax Foundation, release parallel studies highlighting the risks of tax pyramiding, compliance burdens, and trade retaliations stemming from fragmented, unilateral European digital tax frameworks.
Main Facts of the Proposal
Formally presented as a modification to Belgium’s existing corporate income tax, the May 2026 proposal introduces several novel and controversial mechanisms designed to extract revenue from the digital economy:
- Digital Permanent Establishment (DPE): The law reinterprets international tax rules, establishing that a foreign company has a taxable presence in Belgium if it surpasses specific user, connection, or digital participation thresholds during a fiscal year—even if it has zero physical infrastructure or personnel in the country.
- Deemed Profit Allocation: Rather than taxing actual net profits (which can be difficult to calculate under arm’s-length principles when dealing with remote digital services), the proposal assigns presumed profit margins to various digital business models.
- Digital Withholding Tax: Operating as both a minimum tax and a non-refundable levy, a digital withholding tax is imposed in the tax year following the CIT liability at a rate equal to 80 percent of the digital corporate income tax liability. This mechanism creates acute cash-flow challenges, particularly for loss-making enterprises.
Supporting Data and Economic Modeling
While proponents of the Belgian reform argue that modernizing the tax code is essential for fiscal fairness, economic analysis paints a concerning picture regarding its revenue-to-cost ratio.
Projected Revenue vs. Economic Contraction
According to economic modeling conducted by the Tax Foundation, a 3 percent digital tax aligned with the Belgian proposal would generate approximately €148 million annually. While this sounds like a substantial sum, it represents less than 0.06 percent of Belgium’s total tax revenues.
Conversely, the broader economic fallout is projected to dwarf these collections:
- GDP Impact: Belgian Gross Domestic Product is estimated to drop by 0.056 percent, translating to an annual economic contraction of roughly €342 million.
- Investment Decline: Capital investment in the country is projected to fall by 0.073 percent.
- Labor Market Strain: Real wages and total hours worked would both decline by 0.03 percent, pushing total labor compensation down by 0.053 percent.
The Multiplier of Inefficiency
Most striking is the ratio of economic harm to state revenue. The estimated economic output loss of €342 million is 2.3 times larger than the projected annual revenue collection of €148 million. This indicates that the broader contraction of the tax base will likely cannibalize other tax revenues, resulting in a net-negative fiscal outcome for the Belgian government.
Official Responses and Expert Testimony
In her testimony before the Belgian Finance and Budget Committee, economist Cristina Enache dismantled the legal veneer of the proposal, arguing that economic substance must supersede legal semantics.
"Although the proposal is presented as an income tax reform rather than a digital services tax, its economic substance closely resembles the DSTs adopted across Europe over the last decade," Enache stated. "The proposal departs significantly from sound tax policy principles and risks generating substantial economic distortions, legal uncertainty, and trade frictions while raising relatively little revenue."
Furthermore, experts have pointed out that the reinterpretation of existing international tax treaties—specifically trying to force digital operations into traditional permanent establishment definitions—violates the spirit of the Vienna Convention on the Law of Treaties (VCLT). Circumventing years of formal international negotiations at the OECD and UN through unilateral reinterpretation undermines legal certainty and damages international reciprocity.
Implications for Businesses and Consumers
1. Tax Pyramiding and the Penalty on Specialization
Modern digital commerce relies heavily on specialization. A single digital transaction often involves a search engine for discovery, a marketplace for matching buyers and sellers, an advertising platform for customer acquisition, and a specialized payment processor.
Unlike a Value-Added Tax (VAT), which features input tax credits to prevent cascading taxation, the Belgian proposal lacks any mechanism to eliminate multiple layers of taxation. This creates tax pyramiding, effectively penalizing business specialization, discouraging outsourcing, and forcing firms toward inefficient vertical integration.
2. The Burden Falls on Consumers and SMEs
While the tax is ostensibly levied on large multinational technology firms (many of which are headquartered in the United States), empirical evidence from other European nations shows that the economic incidence is largely passed down the line.
When the United Kingdom, France, and other nations implemented DSTs, major tech firms—including Apple, Amazon, and Google—passed the costs onto users via platform fees and ad surcharges. Consequently, the true financial burden falls squarely on local advertisers, marketplace sellers, small and medium-sized enterprises (SMEs), and everyday Belgian consumers.
3. Transatlantic Trade Tensions and Retaliation Risks
Because the tax disproportionately impacts U.S.-based technology giants, the proposal threatens to reignite trade friction between Europe and the United States. The U.S. government has historically opposed unilateral DSTs, utilizing Section 301 investigations and legislative threats (such as the proposed Section 899 retaliatory tax) to combat discriminatory foreign taxes.
Given that the United States is Belgium’s fourth-largest export market—accounting for billions in bilateral trade across ICT and digitally deliverable services—embarking on a unilateral taxation crusade risks triggering retaliatory tariffs that could devastate other sectors of the Belgian export economy.
A Superior Alternative: Strengthening the VAT
For policymakers seeking sustainable revenue from the digital economy, the blueprint already exists. Experts argue that Belgium should abandon its flawed corporate tax reinterpretation and instead focus on optimizing the Value-Added Tax (VAT) system.
A destination-based VAT is inherently neutral, avoids tax pyramiding, applies seamlessly across international borders, and requires no market-distorting deemed profit calculations. Recent reforms to EU e-commerce VAT rules have proved remarkably successful, with revenues collected from non-EU remote businesses scaling dramatically from €3 billion in 2015 to over €33 billion across the EU by 2024.
By broadening the existing VAT base—such as eliminating inefficient reduced rates and policy gaps—Belgium could unlock tens of billions of euros in sustainable revenue without inviting international trade wars or crushing domestic innovation.
Conclusion
Belgium’s May 2026 corporate income tax proposal represents a hazardous policy pivot. By attempting to shoehorn digital user engagement and gross-revenue metrics into a traditional corporate tax framework, policymakers have constructed a digital services tax in disguise.
The consequences are clear: minimal revenue gains offset by massive economic contraction, compounded administrative complexities, heightened risks of double taxation, and the near-certainty of foreign trade retaliation. To protect its economic competitiveness, foster innovation, and maintain stable international relations, Belgium should scrap the DPE proposal and defer to coordinated international frameworks and destination-based VAT mechanisms.