By Financial Markets Desk
Published: April 2026
Main Facts
For generations, conventional financial wisdom prescribed a single path to wealth creation: acquire a significant physical asset—such as a residential home, speculative equities, or high-volatility digital currencies—and wait for long-term appreciation to do the heavy lifting. While this strategy can yield results over extended horizons, it leaves investors acutely vulnerable to macroeconomic volatility, interest rate shifts, and market timing.
A growing faction of wealth builders and institutional giants, however, is pivoting toward an alternative paradigm: cash-flow-first investing. At the epicenter of this strategy are manufactured housing communities, colloquially known as mobile home parks.
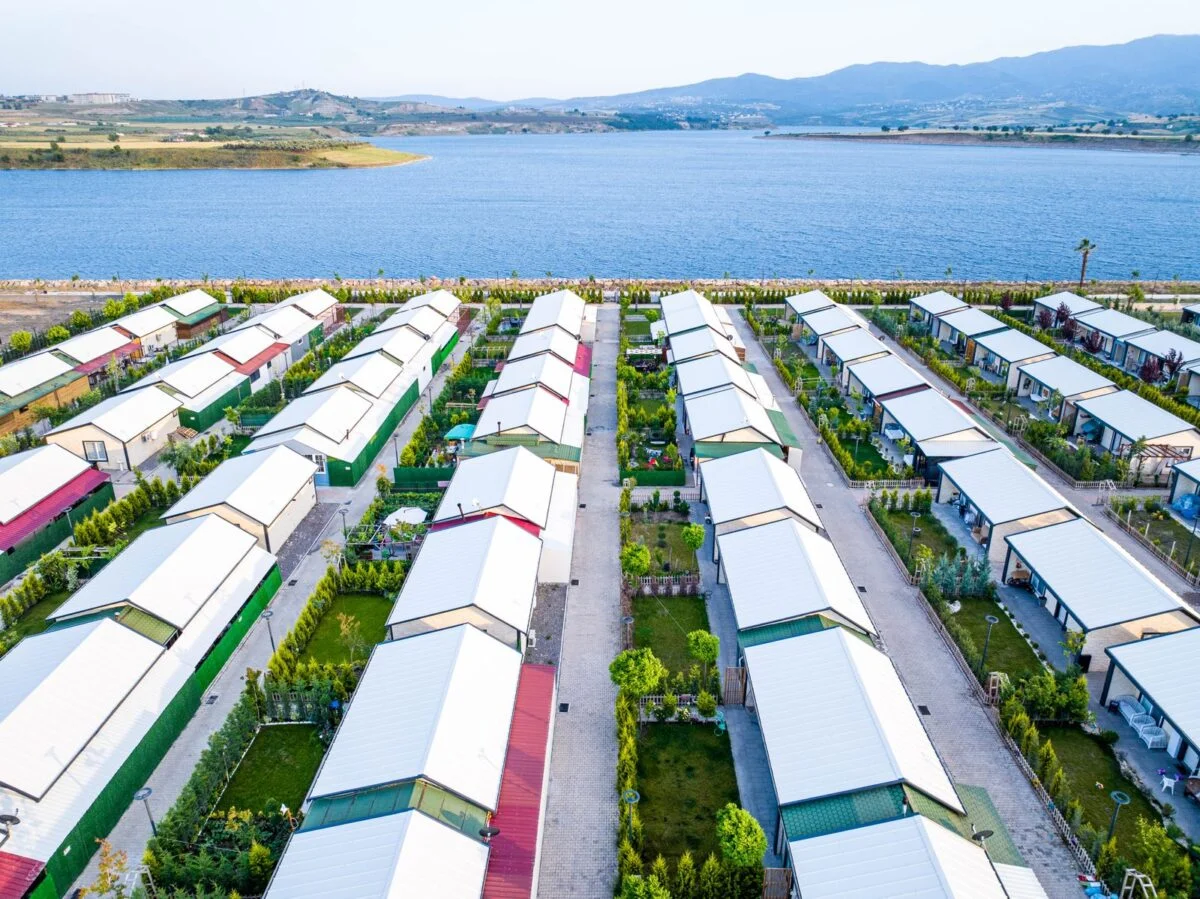
Unlike traditional multi-family apartment complexes or single-family rental portfolios, mobile home park ownership operates on a fundamentally different operational model. Investors generally own the underlying land, the internal roadways, and the overarching utility infrastructure, while the residents own the physical structures resting on the lots. This simple structural distinction decouples the landlord from the capital-intensive maintenance of building interiors—such as roofing, plumbing, and HVAC systems—drastically compressing operating expenses.
Driven by an acute national housing affordability crisis, tight zoning regulations that restrict new supply, and historically high tenant retention rates, mobile home parks have transformed from an overlooked real estate niche into one of the most resilient asset classes in modern finance.
Chronology and Evolution of the Asset Class
The evolution of manufactured housing from a stigmatized, decentralized sector into an institutional-grade asset class spans several decades, characterized by distinct phases of market recognition:
- The 1980s–1990s (The Fragmentation Era): For decades, mobile home parks were largely owned by mom-and-pop operators who developed or acquired land during the late 20th century. These small-scale operators often managed properties with minimal technological integration, below-market lot rents, and inconsistent utility billing practices.
- The Early 2000s (The Institutional Discovery): Billionaire investors and macro-financiers—most notably Warren Buffett (through Clayton Homes) and Sam Zell (founder of Equity LifeStyle Properties)—began recognizing the structural advantages of land-lease communities. They identified that owning the dirt provided a hedge against inflation and a baseline of cash flow largely insulated from broader economic downturns.
- The 2010s (The Professionalization Wave): Private equity firms and Real Estate Investment Trusts (REITs) began aggressively consolidating the fragmented market. They applied institutional management techniques, upgraded neglected infrastructure, and optimized operational efficiencies to drive net operating income (NOI).
- The 2020–2026 Housing Crunch (The Mainstream Acceleration): Fueled by post-pandemic inflation, soaring mortgage rates, and a historic deficit in starter-home construction, demand for manufactured housing surged. National occupancy rates climbed to near-record highs, pushing institutional and retail capital alike to seek exposure to the sector.
Supporting Data and Market Metrics
The financial resilience of manufactured housing communities is underscored by recent market data compiled by industry researchers and real estate analysts heading into 2026.
According to Northmarq’s 2026 market outlook, national occupancy rates in manufactured housing communities reached a staggering 94.9% in the second quarter of 2025. This near-full capacity highlights a severe lack of alternative housing options for lower- and middle-income demographics. Concurrently, average asking lot rents climbed to $752 per month, representing a robust 7% year-over-year increase.
Expense ratios further distinguish mobile home parks from traditional real estate assets. While conventional apartment buildings frequently consume 50% or more of their gross revenue on property management, maintenance, and turnover costs, well-maintained manufactured housing communities typically operate at an expense ratio of 35% to 40%.
This 10-to-20 percent efficiency delta directly benefits the bottom line, preserving distributable cash flow even during periods of economic stagnation. Furthermore, Justin Donald, founder of The Lifestyle Investor, notes that because moving a manufactured home requires heavy logistical coordination, specialized transport permits, and thousands of dollars in capital, tenant turnover is remarkably low—often resulting in tenancies that last years or even decades.
Official Responses and Expert Perspectives
Industry leaders, REIT executives, and financial analysts have increasingly vocalized their strategic rationale for prioritizing manufactured housing over other asset classes.
Justin Donald, writing on macro-investment strategies for Forbes, emphasizes the fundamental importance of prioritizing yield over speculative appreciation:
"When income stands on its own, appreciation is a bonus instead of a goal. Furthermore, the stickiness of tenants—moving a mobile home is a logistical and cost-intensive experience—translates into lower turnover rates and consistent cash flow."
Addressing the tactical playbook for independent investors looking to break into the space, Donald advises targeting undervalued assets rather than competing directly with multi-billion-dollar REITs:
"If you are interested in investing in mobile home parks, it is a good idea to purchase properties that are not yet attractive to institutional investors. An investor can elevate a lower-tier park into an asset that REITs will pay a premium for by increasing occupancy, upgrading infrastructure, and improving the community’s attractiveness."
Industry researcher Ferd Niemann echoes these sentiments, pointing out that the operational friction of traditional rentals—such as a single failed HVAC unit or a defaulting tenant wiping out a year’s worth of profit—is largely mitigated in land-lease communities because capital expenditures are shifted away from the park owner and onto the individual homeowner.
At the same time, market regulators and housing advocates have issued cautionary notes regarding aggressive rent optimization. Because manufactured housing residents face high barriers to relocating their homes, predatory park owners who enact steep, unannounced lot-rent hikes have occasionally drawn negative media attention. Ethical operators and institutional funds increasingly emphasize that long-term asset value is best preserved through predictable, modest rent increases tied directly to tangible community improvements.
Implications for Investors and the Broader Housing Market
The rise of manufactured housing as a preferred cash-flow vehicle carries profound implications for individual wealth builders, institutional allocators, and the broader real estate ecosystem.
1. A Shift in Portfolio Construction
The core philosophy championed by cash-flow investors challenges the speculative nature of modern stock and real estate portfolios. By prioritizing assets that generate consistent, monthly revenue irrespective of broader market cycles, investors insulate themselves from the emotional toll of market timing. This principle—evaluating any potential deal by asking whether it produces immediate, reliable income—serves as a rigorous filter against speculative bubbles.
2. Accessibility Across Capital Tiers
While acquiring a 100-lot commercial park requires significant capital and operational expertise, the financialization of the sector has opened alternative entry points for everyday investors:
- Publicly Traded REITs: Enterprises like Sun Communities and Equity LifeStyle Properties allow retail investors to gain fractional exposure to large-scale portfolios through standard brokerage accounts, capturing regular dividend yields without landlord responsibilities.
- Private Syndications: Accredited investors frequently pool capital through private equity funds and syndications, targeting minimum investments between $25,000 and $50,000. Thorough vetting of the operator’s historical track record is paramount in these arrangements.
- Direct Ownership: Smaller, rural parks offer lower acquisition barriers—sometimes accompanied by seller-financing options—though they demand hands-on management and round-the-clock maintenance oversight.
3. Macroeconomic Pressures and Supply Constraints
The macro-environment heavily favors the persistence of high occupancy in mobile home parks. With starter-home prices remaining out of reach for a significant portion of the workforce, manufactured housing stands as one of the final bastions of independent, single-family living without shared walls. Concurrently, strict local zoning laws and community pushback make the development of new parks exceedingly rare. This immovable supply-side ceiling, paired with escalating demand, ensures that existing park owners retain strong pricing power for the foreseeable future.
Summary
Mobile home parks may lack the cultural cachet of high-tech equities or luxury urban developments, but their structural mechanics tell a different story. By combining low operational expense ratios, exceptional tenant retention, systemic housing demand, and substantial value-add potential through operational modernization, manufactured housing communities offer a masterclass in resilient cash flow generation. Whether through direct ownership or public market equities, understanding the economics of renting dirt rather than houses provides a valuable framework for navigating the future of wealth accumulation.