As real estate markets navigate a shifting landscape defined by higher interest rates, fluctuating inventory, and cautious buyers, savvy investors are finding doors opening to opportunities not seen in years. Far from signaling a downturn for the asset class, today’s economic climate has created a unique buyer’s market characterized by steep developer discounts, creative financing options, and unprecedented negotiation leverage.
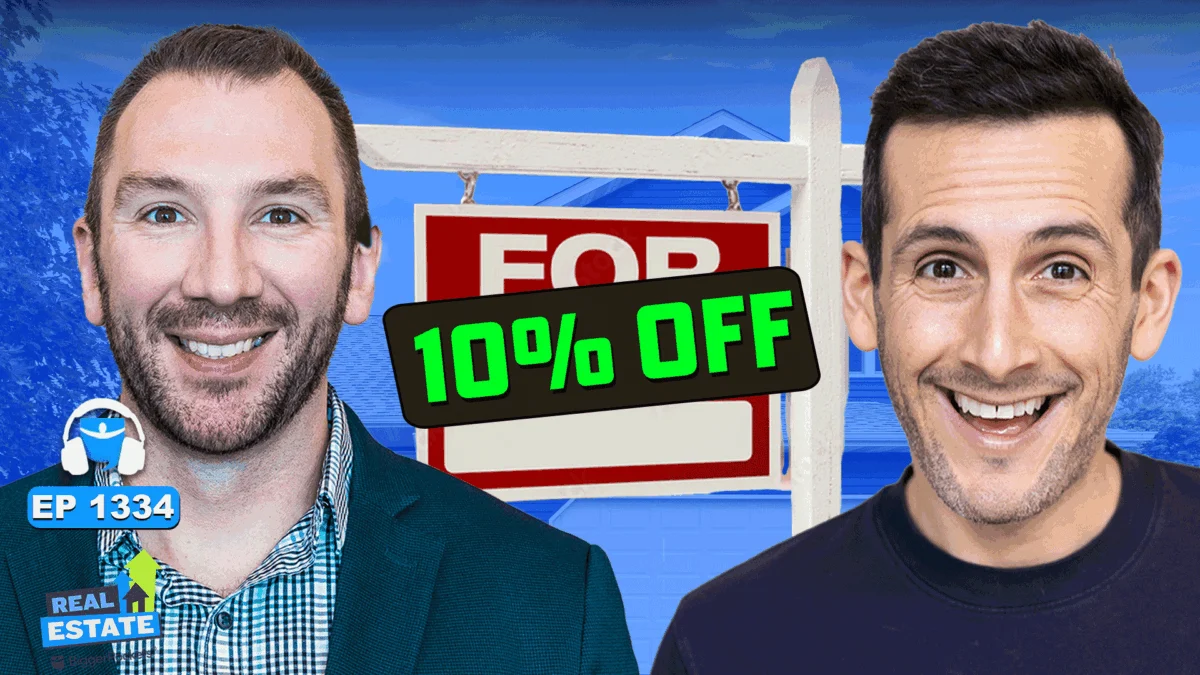
Recently, real estate expert and podcast host Dave Meyer sat down with Zach LeMaster—Air Force veteran, optometrist-turned-investor, and CEO of Rent to Retirement—to dissect the current market. LeMaster shared the exact playbook he uses to secure double-digit discounts on new construction properties, leverage low down-payment options, and build long-term generational wealth regardless of broader economic cycles.
Main Facts: A Paradigm Shift in Modern Real Estate Investing
The prevailing narrative surrounding the housing market often focuses on affordability hurdles and elevated interest rates. However, industry veterans view these conditions through a completely different lens. Rather than waiting on the sidelines for interest rates to drastically recede, top-tier investors are capitalizing on a fundamental shift in supply and demand.
- Massive Builder Discounts: National and regional homebuilders, struggling to match their inventory build-ups with slower retail demand, are heavily incentivized to offload assets. This pressure is translating into baseline price reductions and concessions ranging from 10% to 15% (and occasionally up to 20%) on single-family and small multifamily properties.
- The New Normal on Rates: While historically low interest rates of the pandemic era are unlikely to return anytime soon, investors are utilizing creative structures—such as builder-paid rate buydowns to land in the 3% to 4% range, or adjustable-rate mortgages (ARMs)—to maintain strong cash flow.
- Low Capital Barriers to Entry: Programs like VA loans (offering zero-down terms for eligible military members) and specialized local credit union products allow investors to secure prime residential assets with as little as 5% to 15% down, sidestepping hefty private mortgage insurance (PMI) costs.
- Institutional Pullback: Increased regulatory scrutiny and shifting market dynamics have forced large institutional buyers and REITs to pump the brakes on massive portfolio acquisitions. This has effectively sidelined corporate competition, leaving prime new-construction inventory open to everyday individual investors.
Chronology: From Military Optometrist to Turnkey Empire
Zach LeMaster’s journey into real estate is a testament to the power of consistency and learning through adaptation. His path illustrates how an outsider with no formal financial background built a multi-million-dollar portfolio and one of the nation’s leading turnkey real estate companies.
The Early Years: Military Discipline and House Hacking (2010–2012)
LeMaster’s career path initially had nothing to do with real estate. Trained as an optometrist through a military scholarship (HPSP), he served as a captain in the U.S. Air Force. Stationed in North Dakota roughly 15 years ago, LeMaster had no capital and zero knowledge of the stock market.
Realized as a tangible asset that made intuitive sense, real estate became his primary focus. Leveraging a VA loan with zero money down, he bought his first duplex—effectively "house hacking" before the term was widely popularized. He lived in one half and rented out the other. Encouraged by the results, he continued purchasing local duplexes year after year, building foundational experience while scaling locally until he ran into traditional capital limits.
The Out-of-State Pivot and Early Failures (2013)
Seeking higher returns, LeMaster and his wife expanded their search beyond their local market, dipping their toes into out-of-state investing. Their first venture targeted Southside Chicago, focusing on low-income Section 8 multi-family properties ("two-flats" and "three-flats") with seemingly stellar paper returns.
The reality proved far more challenging. Dealing with ongoing maintenance issues, heavy contractor hurdles, and administrative friction with the Chicago Housing Authority turned portfolio management into a slow drain on resources. Rather than quitting, LeMaster treated the missteps as an expensive masterclass in out-of-state operations. He refined his systems, learned how to properly vet target markets, and focused intensely on building reliable local teams rather than trying to micromanage properties remotely.
Scaling and Founding Rent to Retirement (Present Day)
By consistently buying properties every single year—through up markets, down markets, and everything in between—LeMaster systematically replaced his active income as an optometrist. He eventually left the Air Force and founded Rent to Retirement. Today, the company serves as a leading national turnkey provider, helping retail investors replicate institutional-level acquisition strategies in high-growth corridors.
Supporting Data: The Mechanics of Modern Underwriting
For newer investors intimidated by current market conditions, LeMaster emphasizes that real estate remains fundamentally simple: buy a good asset in a good market with a reliable team, and let time work as your primary compounding partner. However, modern underwriting requires mastering a few key components.
1. The Sunbelt and Midwest Strategy
LeMaster’s portfolio balances two distinct geographic plays:
- The Sunbelt (approx. 80% of focus): Markets across the Southeast (Georgia, Alabama, the Carolinas, Florida, and Texas) where population growth, business migration, and new construction developments converge.
- The Midwest: Affordable housing markets prioritized primarily for pure cash-flow generation.
2. Targeting New Construction Build-to-Rent
Older properties, while occasionally acquired at lower price points, often come with deferred maintenance and unexpected capital expenditures that erode returns. By focusing on new construction—particularly single-family homes and small multi-families priced between $250,000 and $500,000 in A and B neighborhoods—investors benefit from builder warranties, lower ongoing maintenance, and higher-quality, long-term tenants.
3. Maximizing Tax Leverage
Too many novice investors hyper-focus exclusively on monthly cash flow while ignoring the massive wealth-multiplying power of the tax code.
- Cost Segregation and Accelerated Depreciation: By conducting cost segregation studies on new construction properties, investors can generate massive paper losses (e.g., roughly 30% depreciation write-offs in year one) to offset active or passive income.
- The Short-Term Rental Loophole: Utilizing IRS rules regarding material participation (such as the "substantially all" test under IRC Section 469), investors managing their own short-term rentals can utilize depreciation to offset high W-2 or active business income without necessarily qualifying as full-real-estate professionals under stringent hourly minimum tests.
- 1031 Exchanges: Perpetually deferring capital gains taxes allows investors to scale their portfolios upward across market cycles, eventually passing assets to heirs with a stepped-up basis.
Official Responses & Industry Perspectives
Dave Meyer, VP of Market Intelligence at BiggerPockets, echoed LeMaster’s sentiments regarding market timing and strategic pivoting. Meyer noted that his own investing philosophy changed drastically once he moved abroad and was forced to abandon local management.
"For the first 10 years of my investing career, I invested locally… And then 10 years into it, I moved to Europe and everything is long distance to me at this point. So what’s the point of only limiting myself to Denver? When I started to do that, it really changed my whole investing philosophy and I realized how much investing locally actually had held me back."
— Dave Meyer, Host, BiggerPockets Podcast
Industry insiders point out that major homebuilders are fundamentally different retail sellers than everyday homeowners. While a standard individual seller might choose to let their home sit on the market for six months waiting for an unrealistic price, institutional builders operate on volume and balance-sheet velocity. Their carrying costs dictate that inventory must move. This dynamic gives individual investors partnering with turnkey providers immense leverage to extract concessions, price reductions, and rate buydowns.
Implications: Why 2027 Is Shaping Up as a Buyer’s Paradise
The convergence of high interest rates, cooling builder inventory, and reduced institutional competition has created a rare window of opportunity for retail investors.
- Developing True Investor Skills: As LeMaster points out, buying real estate during a period of ultra-low, artificial interest rates required very little skill; almost any asset appreciated or cash-flowed. Today’s market forces investors to hone their negotiation, underwriting, and creative financing skills. Those who build these foundational muscles now will be best positioned to ride the inevitable appreciation wave when broader market competition inevitably returns.
- Embracing Dollar-Cost Averaging in Housing: Just as stock market investors rely on consistent, systematic contributions to build long-term wealth, real estate investors who purchase assets consistently across every market cycle protect themselves from trying to time the absolute bottom.
- Institutional Advantages for Main Street: Through turnkey models that leverage bulk purchasing power, everyday investors can now access the same 13% to 15% volume discounts traditionally reserved for Wall Street private equity firms.
Ultimately, the message for real estate investors looking ahead is clear: stop waiting for the "unicorn deal" or a return to historic lows. By focusing on fundamental asset quality, unlocking developer incentives, and maintaining a long-term horizon, today’s market conditions offer some of the most lucrative and heavily discounted opportunities in over a decade.