Navigating the labyrinth of personal finance and insurance products can be a daunting task for families striving to build long-term security. Among the most enduring and fiercely debated topics in financial planning is the choice between term life insurance and permanent (whole life) insurance. For decades, fiduciary advisors have championed a straightforward philosophy: buy term life insurance to protect your dependents during your peak earning years, and invest the substantial cost savings elsewhere.
Recent data underscores why this strategy continues to outshine complex permanent insurance products for the vast majority of households. By examining the stark price disparities, the mechanics of cash-value policies, and the power of compound interest, families can make informed decisions that maximize their wealth while ensuring adequate protection.
Main Facts: The Core Differences and the 2026 Cost Reality
At its core, life insurance serves a singular, fundamental purpose: replacing your income while others depend on it. Whether it is covering daily household expenses, funding a child’s future education, or paying off a multi-decade mortgage, insurance acts as a financial safety net during your working years.
Term life insurance is designed specifically for this purpose. It provides coverage for a specified period—typically 10, 20, or 30 years—matching the timeframe during which your financial obligations are highest. If the policyholder passes away during the term, the beneficiaries receive the death benefit. If the term expires and everyone is secure, the policy lapses.
Whole life insurance, conversely, is a form of permanent coverage. It remains active for the policyholder’s entire life, provided premiums are paid, and it bundles pure insurance with an internal savings vehicle known as "cash value." A portion of every whole life premium goes toward the death benefit, while the remainder is funneled into the cash-value component, which grows at a guaranteed, albeit typically modest, rate.
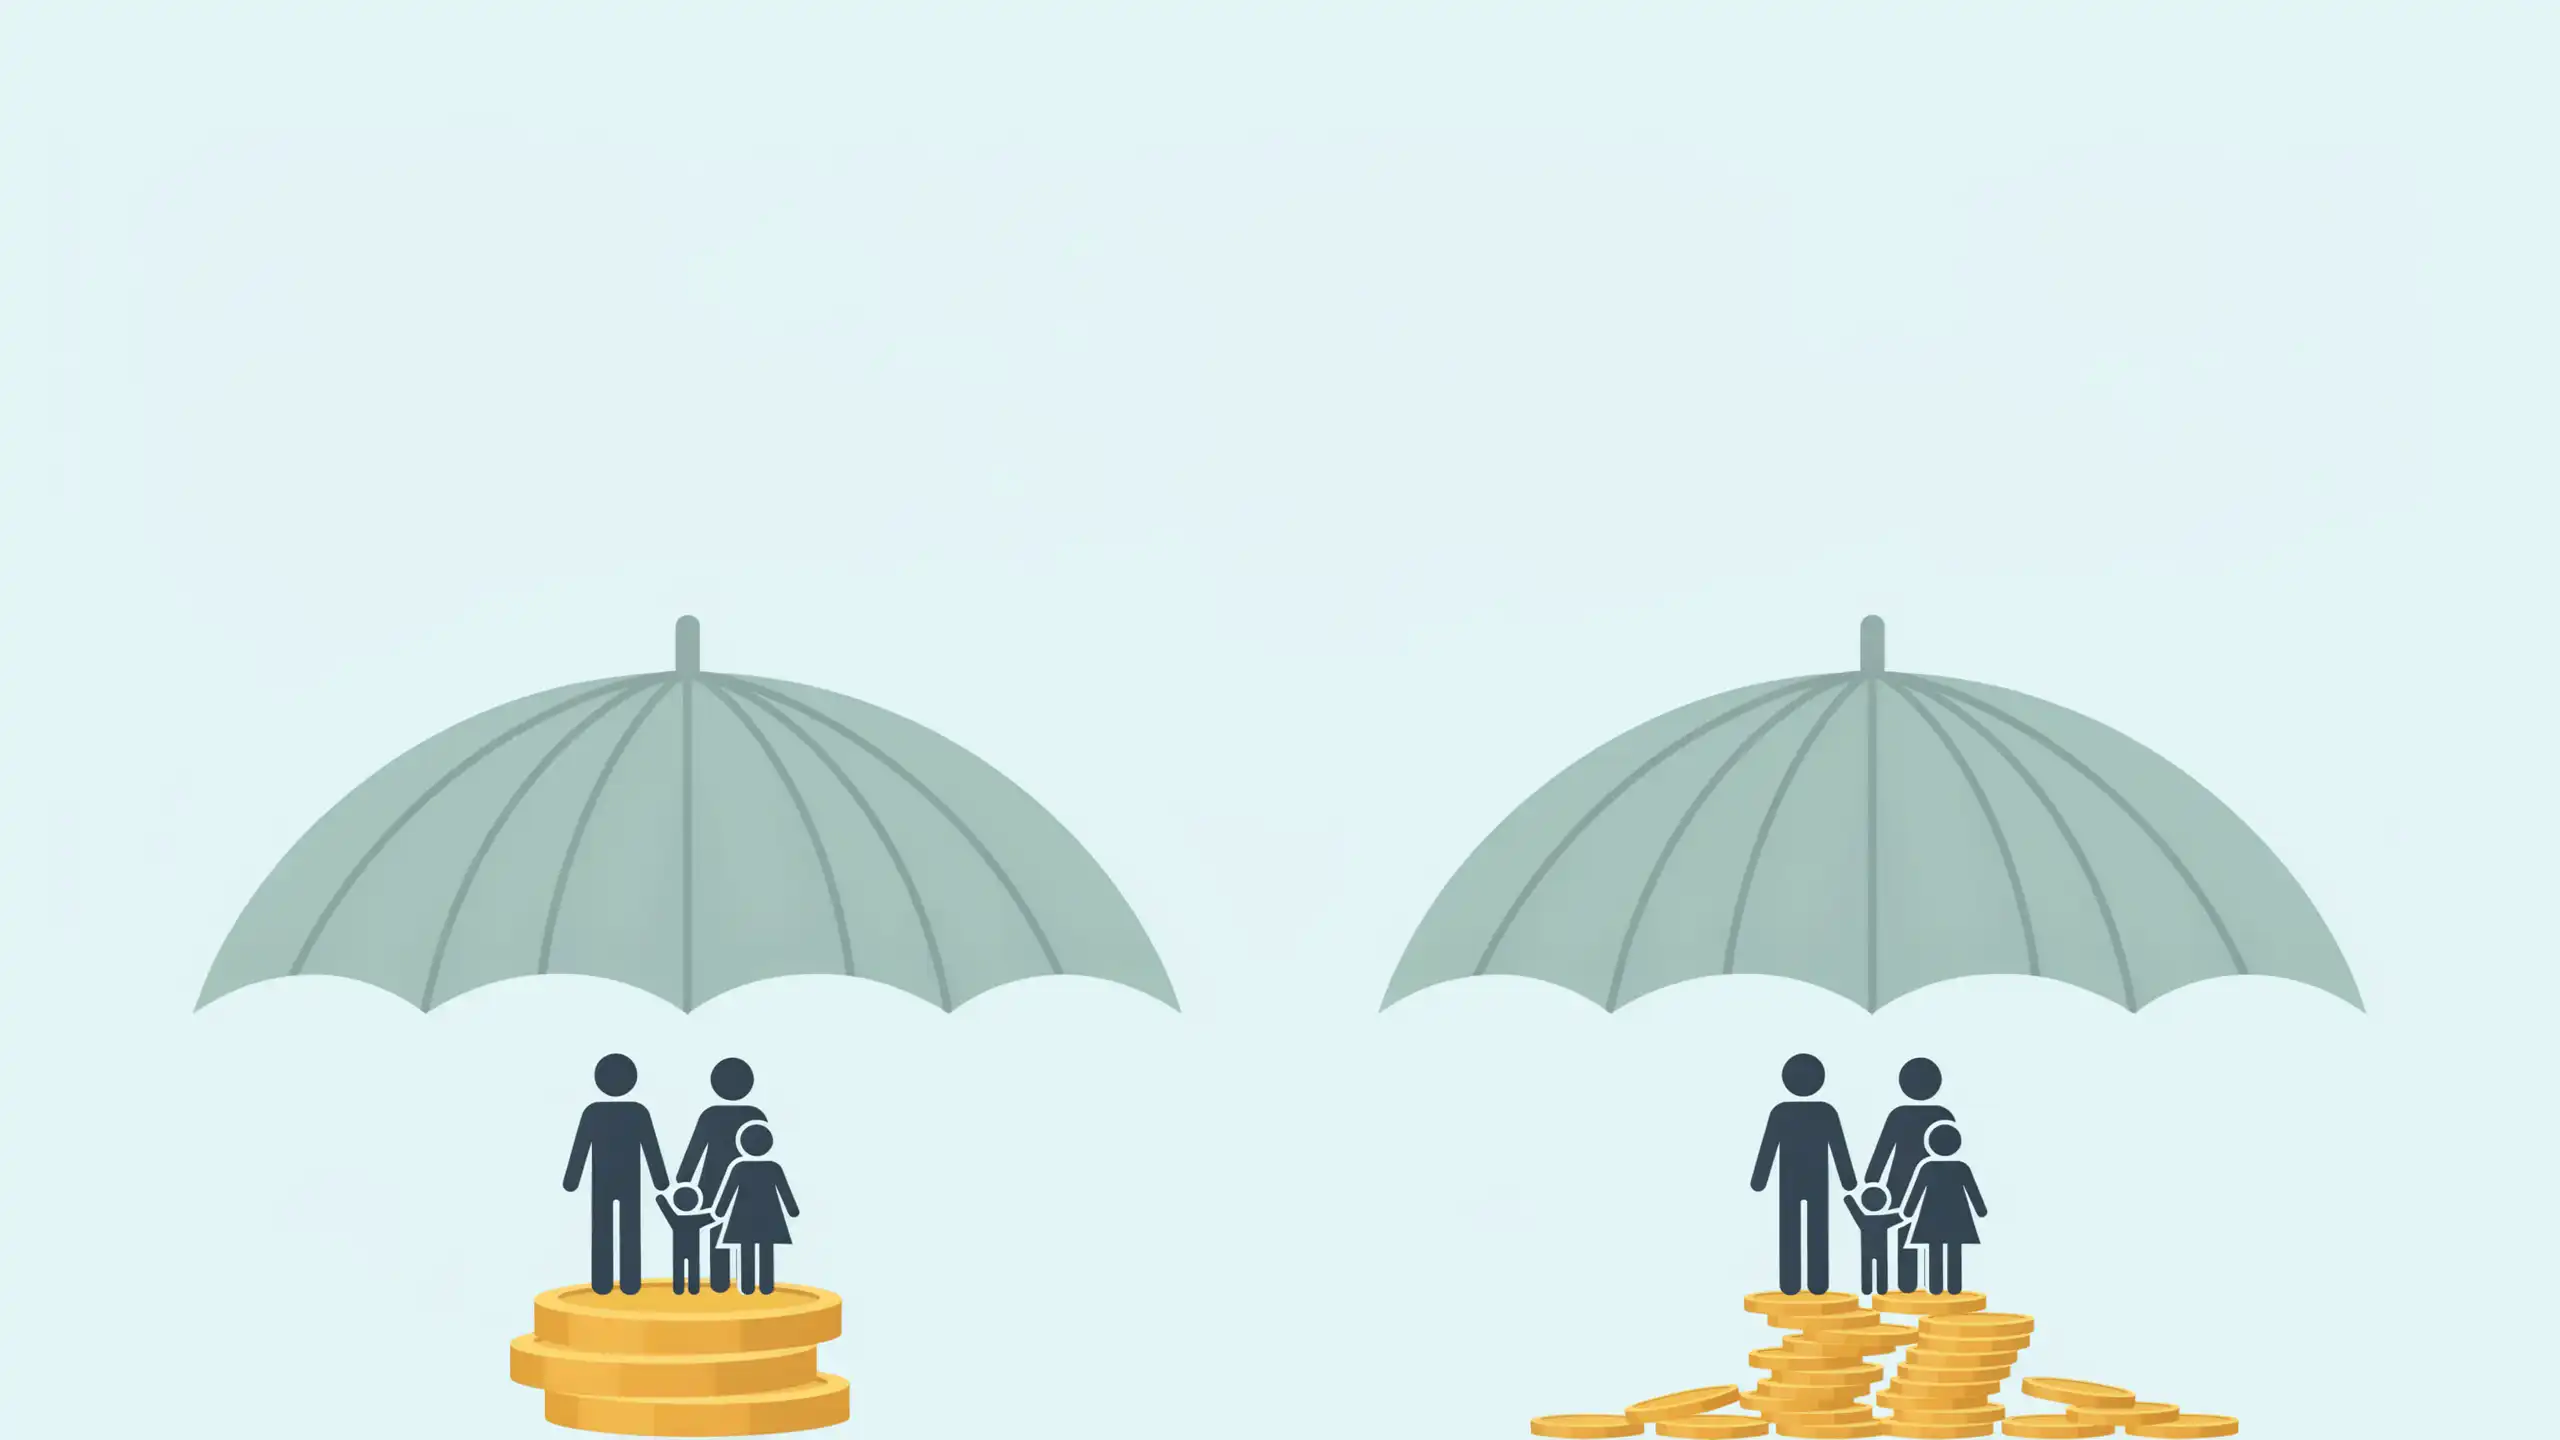
The financial divergence between these two products is staggering. According to a 2026 rate analysis by MoneyGeek, a 35-year-old male nonsmoker in average health can secure a 20-year term life policy with a $500,000 death benefit for approximately $40 a month. By contrast, a whole life policy offering the exact same $500,000 death benefit for the same demographic runs roughly $545 a month.
This means whole life insurance costs nearly 14 times as much as term life insurance for identical immediate payout protection. For the average family balancing a mortgage, grocery bills, and retirement savings, allocating more than $500 a month to a single insurance policy can severely strain monthly cash flow.
Chronology and Evolution of the Insurance Debate
The debate between term and permanent insurance is nearly as old as the modern insurance industry itself.
- The Late 19th and Early 20th Centuries: As commercial life insurance gained prominence in the United States, companies heavily marketed whole life policies. These products appealed to an era before widespread employer-sponsored retirement plans, social security, or accessible mutual funds, serving as both a safety net and a rudimentary forced-savings account.
- The Mid-20th Century ("Buy Term and Invest the Difference"): As financial markets matured and mutual funds became accessible to retail investors in the 1960s and 1970s, pioneering financial educators recognized the severe opportunity cost of whole life insurance. This era birthed the catchphrase "Buy Term and Invest the Difference" (often abbreviated as BTID). Analysts demonstrated that consumers could buy inexpensive temporary protection and redirect the remaining capital into higher-yielding investments like equities.
- The Late 20th to Early 21st Century: Insurance companies responded by introducing variable and universal life policies, attempting to capture higher market returns by tying cash value directly to stock market indexes. However, high administrative fees, complex fee structures, and market downturns often eroded these gains, keeping the fundamental critique of permanent insurance alive.
- The Present Day (2026 Landscape): Today, consumer advocates, fee-only financial planners, and digital insurance brokerages continue to emphasize transparency. With digital tools making term life quotes instantaneous and self-directed investing simpler than ever, the traditional arguments in favor of term-plus-investing remain robust.
Supporting Data: The Math Behind "Investing the Difference"
To truly understand why financial professionals advocate for term insurance, one must look closely at the math. Let us revisit the 35-year-old nonsmoker from the 2026 rate analysis:
- Monthly Term Insurance Cost: $40
- Monthly Whole Life Insurance Cost: $545
- Monthly Savings (The Difference): $505
Instead of surrendering $545 a month to an insurance company—a significant portion of which is eaten up by high commissions and administrative fees in the early years—the policyholder buys the $40 term policy and invests the remaining $505.
Assuming the investor automates this transfer into a diversified portfolio (such as a 401(k), an Individual Retirement Account (IRA), or a standard taxable brokerage account) targeting a conservative, historically grounded 6% average annual return, let us examine the trajectory over the 20-year term of the policy:
- After 5 Years: The monthly contributions and compounding growth yield roughly $35,000.
- After 10 Years: The account balance grows to approximately $82,000.
- After 15 Years: The total climbs to nearly $148,000.
- After 20 Years: At the conclusion of the 20-year term, the investor has accumulated approximately $233,000.
By the time the 20-year term policy expires, the policyholder’s children are likely grown, the mortgage is substantially paid down, and the accumulated investment portfolio of $233,000 (alongside other retirement accounts) can comfortably support a surviving spouse. The insurance is no longer needed, and the individual has built a substantial, liquid pool of wealth that they completely control.
In contrast, a whole life policy’s cash value is notoriously slow to accumulate in the early years. According to consumer guides published by the National Association of Insurance Commissioners (NAIC), cash value policies often build little to no meaningful cash value in their first decade due to high upfront commissions and fees, only accelerating growth later in the policy’s lifecycle. If a whole life policyholder needs to surrender the policy early, they often receive a fraction of the total premiums paid.
Official Guidelines and Industry Perspectives: What Regulators Say
While financial advisors generally favor term life for standard family protection, regulatory bodies and insurance associations maintain a nuanced view, acknowledging that permanent insurance does serve specific, narrow niches.
The National Association of Insurance Commissioners (NAIC) Perspective
The NAIC publishes comprehensive buyer’s guides for life insurance to help consumers navigate complex policy options. According to the NAIC’s disclosures:
- Cash Value as a Long-Term Tool: The NAIC notes that cash-value (whole life) policies can mathematically become the more cost-effective route if and when an individual requires coverage that genuinely lasts their entire life, and if they hold the policy long enough to amortize the heavy front-end fees.
- Early-Year Vulnerability: The NAIC explicitly warns consumers that cash-value accumulation is back-loaded. In the initial years of a whole life contract, a large percentage of the premium goes toward agent commissions and administrative overhead, meaning surrender values can be minimal if the policy is canceled early.
When Permanent Coverage Actually Makes Sense
Fiduciary financial planners generally agree that permanent insurance is appropriate only under specific, exceptional circumstances:
- Permanent Dependents: Families with a child with special needs who will require lifelong financial support and care long after the parents have passed away.
- Estate Liquidity Needs: High-net-worth individuals whose estates are large enough to trigger significant estate taxes, where liquid cash is required immediately upon death to settle debts and taxes without being forced to fire-sell real estate or business assets.
- Maxed-Out Retirement Accounts: High earners who have already maximized contributions to all tax-advantaged accounts (401(k)s, IRAs, HSAs) and are looking for additional tax-deferred asset accumulation vehicles.
For the average middle-class family, however, none of these conditions apply. Their insurance needs are temporary, tied directly to the years children live at home and the lifespan of a mortgage.
Implications for Families and Modern Financial Planning
The ongoing preference for term life insurance carries profound implications for household financial health, budgeting, and wealth generation.
1. Enhanced Household Cash Flow
Freeing up $505 a month—the difference between the whole life and term premiums in our earlier example—provides immense flexibility. In an economic environment marked by inflation and rising living costs, having extra cash on hand allows families to bolster emergency funds, pay down high-interest consumer debt, or invest in career-advancing education.
2. True Separation of Insurance and Investment
Financial experts have long warned against mixing insurance with investment products. Whole life insurance policies are famously opaque, making it difficult for consumers to understand precisely how much they are paying for mortality protection versus investment management fees. By keeping insurance pure (term) and investments transparent (low-cost index funds, ETFs, or retirement accounts), consumers retain total control over their assets.
3. Overcoming Behavioral Hurdles
The "Buy Term and Invest the Difference" strategy relies heavily on discipline. If a consumer buys a term policy and saves $505 a month, but instead spends that money on discretionary lifestyle inflation, they will find themselves defenseless when the term expires. To counter this, financial planners strongly recommend automating transfers into retirement accounts or brokerage platforms on payday, ensuring the savings habit is hardcoded into monthly routines.
Conclusion
Life insurance is an indispensable tool for safeguarding family members against the unexpected, but it should not be treated as a complex investment vehicle unless specific, permanent liabilities demand it.
By purchasing a term life insurance policy that neatly bridges the years your income is actively needed—such as until your children graduate or your mortgage is cleared—you secure maximum protection for minimal cost. Redirecting the substantial savings into disciplined, long-term investments empowers you to build generational wealth on your own terms. Insure the years people depend on you, and let your investments cover the rest.