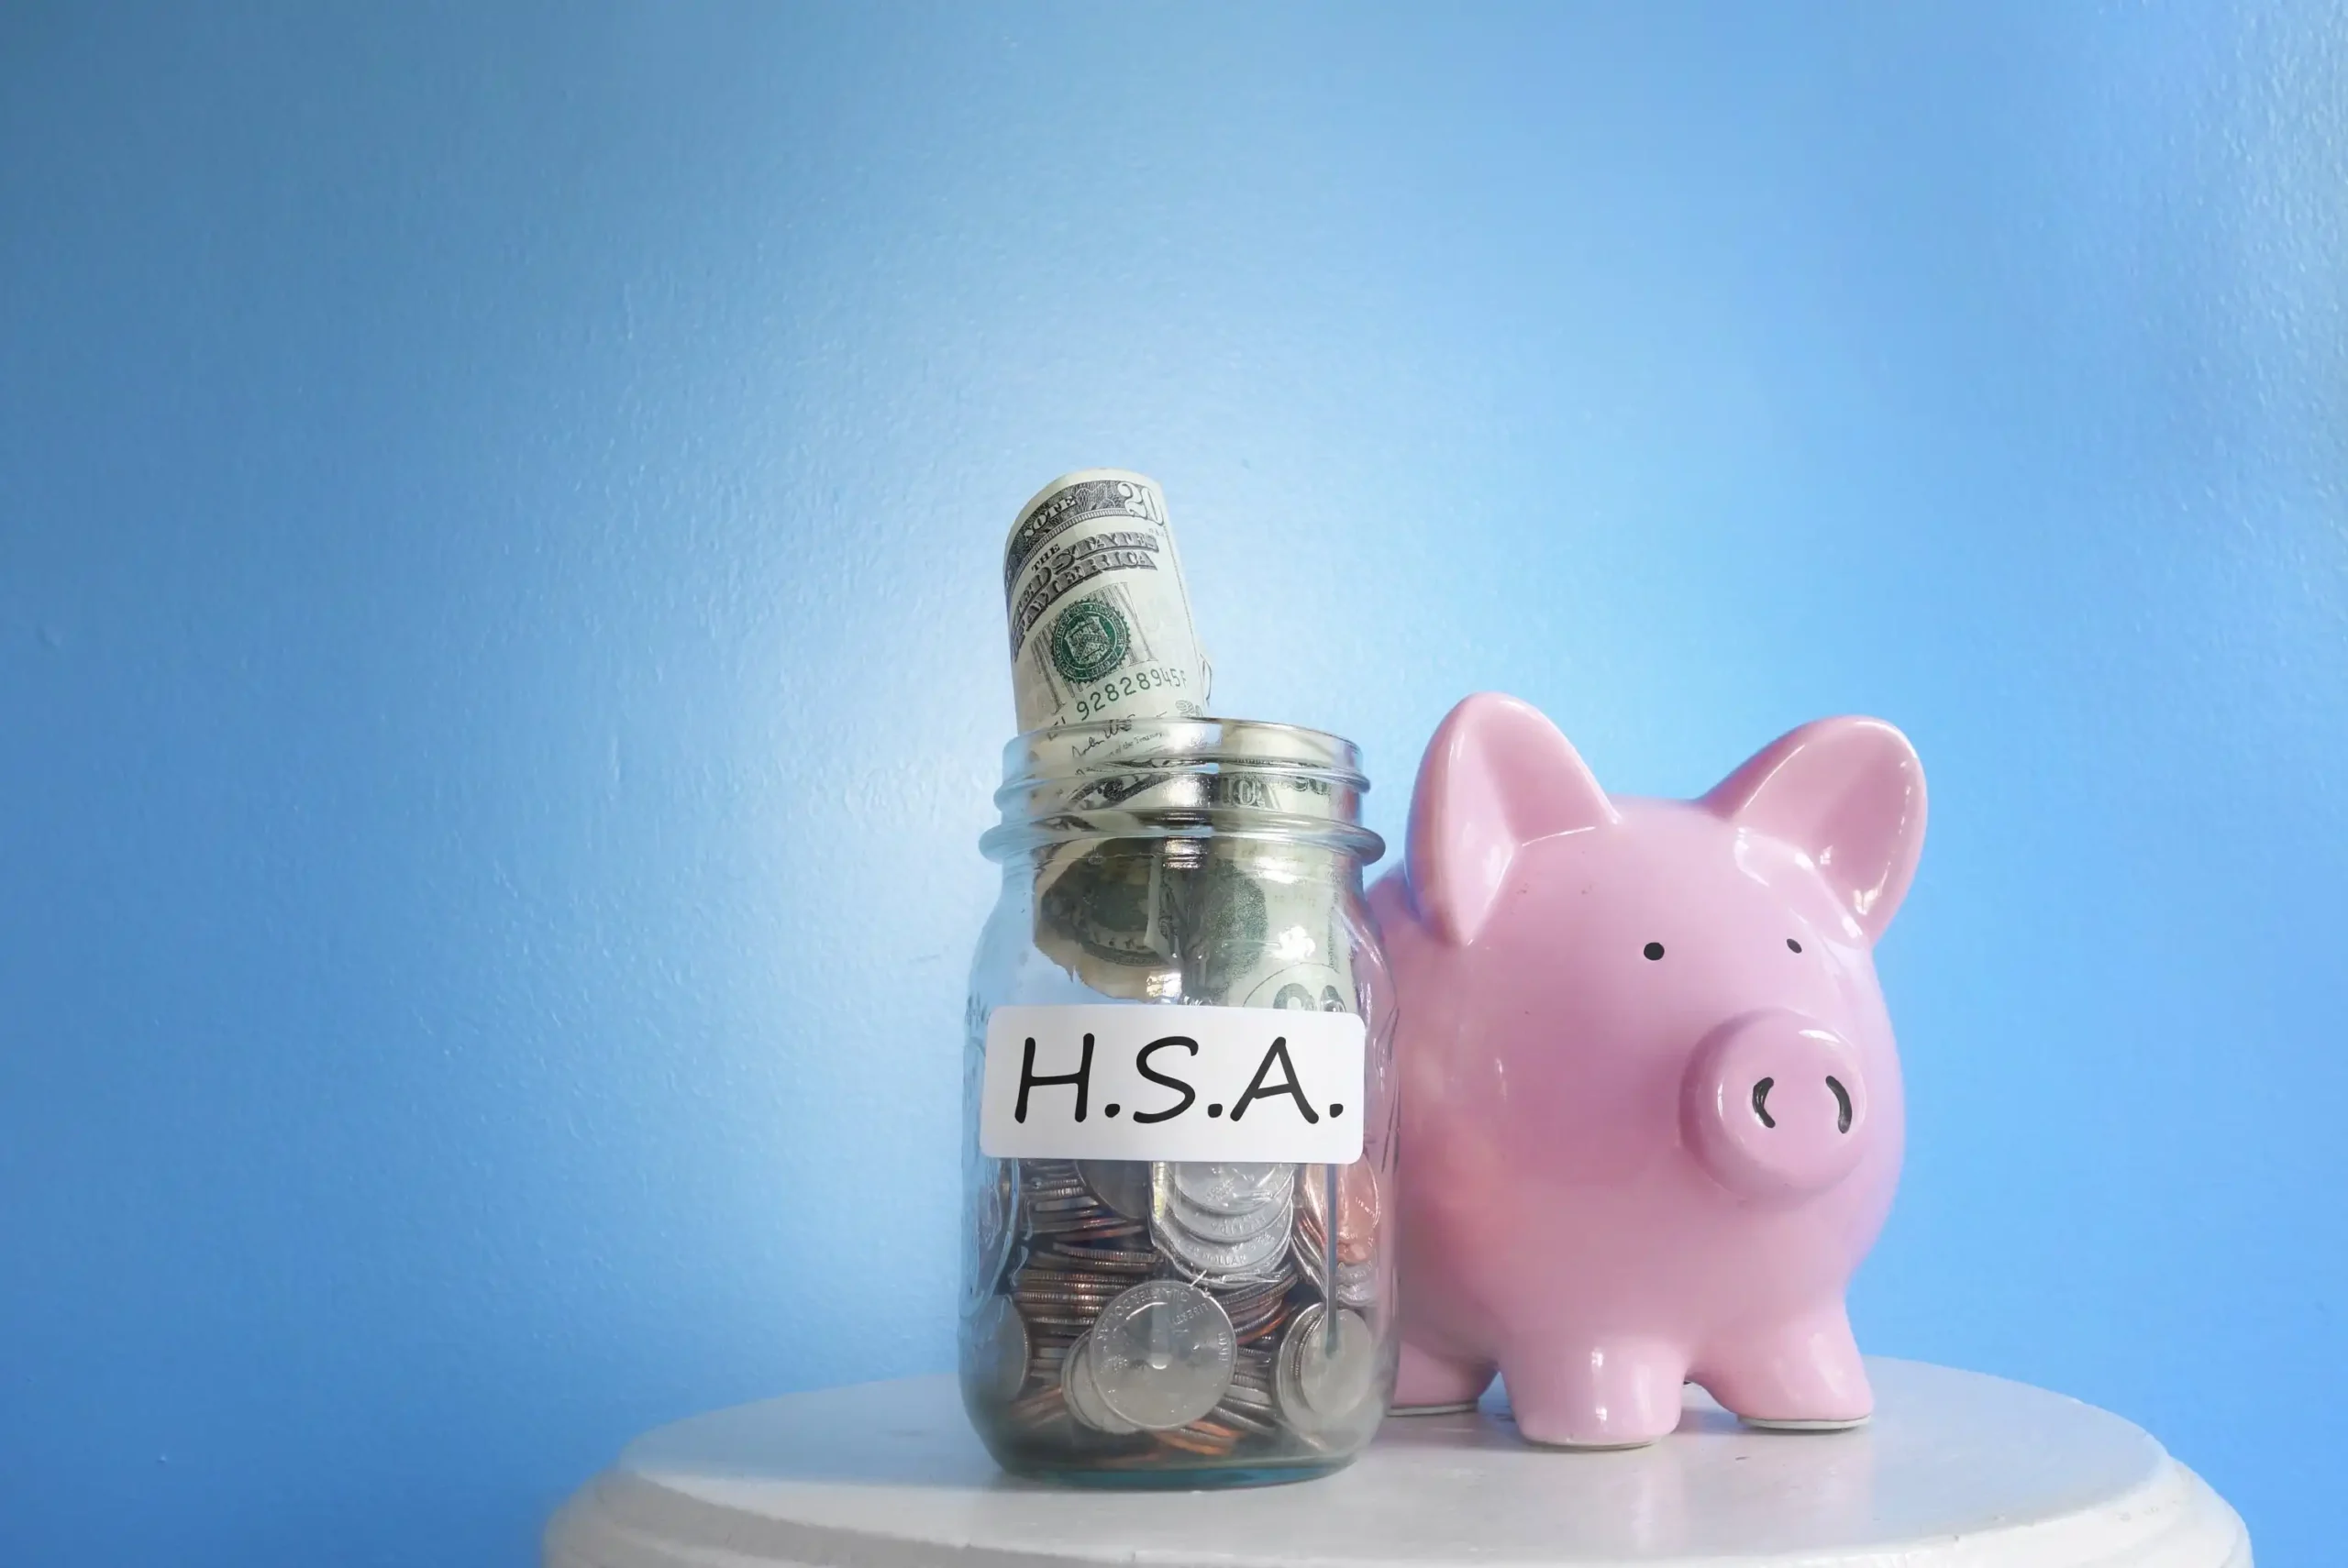
For millions of Americans outside the traditional corporate structure—including gig economy workers, freelance consultants, small-business owners, and those relying on high-deductible health plans (HDHPs)—securing affordable, reliable healthcare coverage often feels like an insurmountable challenge. When navigating the complex landscape of out-of-pocket medical expenses, one of the most powerful and underutilized financial instruments available is the Health Savings Account (HSA).
Famed for its unique "triple tax advantage"—contributions are tax-deductible, funds grow tax-deferred, and withdrawals for qualified medical expenses are entirely tax-free—an HSA can serve as both a short-term medical checking account and a long-term retirement wealth-building vehicle. However, with dozens of administrators populating the financial marketplace, identifying the right HSA provider requires careful analysis of fees, investment menus, accessibility, and account minimums.
Main Facts: What Makes an HSA Essential?
The modern economic landscape has shifted dramatically, pushing a larger percentage of the workforce into independent employment and high-deductible health insurance structures. To survive without employer-sponsored health benefits, consumers must leverage tax-advantaged accounts defensively and offensively.
An HSA is intrinsically tied to an IRS-approved High-Deductible Health Plan. Unlike Flexible Spending Accounts (FSAs), which operate on a strict "use-it-or-lose-it" annual timeline, HSA balances roll over indefinitely. This allows account holders to accumulate significant capital over years or decades. Furthermore, after the account holder turns 65, funds can be withdrawn for non-medical purposes penalty-free (subject only to standard income taxes), making the HSA functionally identical to a traditional IRA when used in retirement.
Choosing the right provider is critical because administration fees, investment expense ratios, and trading commissions directly erode these tax-free gains.
Chronology: The Evolution of the Modern HSA Marketplace
To understand how HSAs became the gold standard of healthcare financing, it helps to examine their institutional trajectory:
- December 2003: President George W. Bush signed the Medicare Prescription Drug, Improvement, and Modernization Act into law, officially creating Health Savings Accounts as a successor to older, more restrictive Archer Medical Savings Accounts.
- The 2010s: As the Affordable Care Act (ACA) took effect and high-deductible health plans proliferated across individual and group markets, consumer demand for self-directed healthcare savings surged. Financial institutions began offering specialized digital platforms.
- The Gig Economy Era (Late 2010s–2020s): With millions entering independent contracting, fintech disruptors entered the space. Companies began offering zero-fee, brokerage-integrated HSAs that mirrored modern online stock trading platforms.
- Present Day (2026): Today’s HSA market features sophisticated hybrid models, robo-advisors, and checking-style accounts designed to serve everyone from risk-averse savers to aggressive, active investors.
Supporting Data: Top HSA Providers on the Market
Evaluating the current marketplace reveals that different administrators cater to distinct consumer profiles. Below is a breakdown of the leading HSA providers based on value, functionality, and investment depth.
1. Best Overall: HSA Authority (Old National Bank)
Old National Bank’s in-house HSA administrator, HSA Authority, routinely claims top honors for overall value. It strikes a rare balance by offering intuitive digital account management, competitive fee schedules, and robust accessibility for individual account holders. It stands out as the most versatile choice for the median user who wants both reliable day-to-day liquidity and dependable long-term growth potential.
2. Best Checking-Style HSA: HealthEquity
For consumers who are risk-averse or hesitant to expose their healthcare savings to market volatility, HealthEquity provides the premier checking-style HSA on the market. It replicates the functionality of a full-service commercial checking account while optimizing funds for long-term appreciation.
- Investment Options: For those willing to dip a toe into the market, HealthEquity offers roughly two dozen Vanguard mutual funds with microscopic expense ratios.
- Management Fees: Their investment management fee is nominal, sitting at just $0.33 per $1,000 invested (0.033% of assets under management).
3. Best Hybrid HSA: Starship HSA
Starship HSA bridges the gap between liquid cash management and wealth accumulation by offering dual-account functionality (checking and brokerage).
- Checking Account: Comes with a standard debit card and zero maintenance fees. Balances over $2,000 earn a modest 0.04% APY.
- Investment Account: Charges a flat $1 per month for balances under $5,000, and a 0.35% annual AUM fee for higher balances. While slightly higher than traditional brokerages, the structured hybrid approach rewards disciplined savers.
4. Best for Zero Maintenance Fees: Fidelity HSA
Capitalizing on its world-class online brokerage infrastructure, the Fidelity HSA delivers an elite experience for aggressive investors. It provides access to the exact same broad spectrum of investment options found in a standard taxable brokerage account, all packaged within a tax-advantaged framework. With zero maintenance fees on its HSA offerings, Fidelity is difficult to beat for individuals eager to aggressively deploy capital into equities.
5. Best for Active Investors: Lively HSA
Powered by TD Ameritrade’s advanced trading platform, Lively caters directly to active investors who demand robust charting tools, comprehensive market research, and granular control over their portfolios.
- Account Minimums: There is no minimum balance requirement to access Lively’s investment tier.
- Trading Costs: TD Ameritrade charges zero commissions on trades, rendering active health and retirement investing both flexible and cost-effective.
6. Best Robo-Advisor: Further HSA (Formerly Select Account)
Utilizing Charles Schwab’s infrastructure, Further HSA is tailored for long-term investors seeking automated wealth management. Account holders can build a preselected asset allocation with a $1,000 balance or leverage Schwab’s Intelligent Portfolios platform—one of the industry’s premier robo-advisors—upon reaching a $10,000 balance.
Methodology: How to Evaluate and Select an HSA Provider
Not all health savings accounts are created equal. Financial experts evaluate administrators using five core criteria:
- Ease of Access: If you intend to use your HSA as a primary vehicle for immediate medical bills, look for administrators providing debit cards, physical check-writing capabilities, online banking portals, and electronic bill pay.
- Investment Options: Account holders generally fall into two categories: "savers" who treat the account like a traditional bank account, and "investors" who demand access to index funds, ETFs, and individual stocks. Ensure your provider matches your financial strategy.
- Minimum Balance Requirements: Watch out for minimum thresholds. Failing to maintain these balances can trigger monthly maintenance fees, trading lockouts, or administrative penalties. Always prioritize providers with low or zero minimums.
- Fee Schedules: Hidden costs can decimate returns. Common fees include setup fees, monthly maintenance fees, investment management fees, and paper statement fees. As a rule of thumb, aggregate annual fees should remain well below 1% of your total invested assets.
- Interest Rates: While cash balances often earn nominal interest, consumers should be wary of chasing low yields if monthly maintenance fees outweigh the interest earned. Avoiding fees is almost always more lucrative than chasing fractional interest bumps on cash holdings.
Official Guidelines: Rules, Regulations, and Use Cases
Understanding IRS guidelines is critical to maximizing an HSA without triggering financial penalties.
What Constitutes a Qualified Medical Expense?
Before the age of 65, HSA distributions must be used exclusively for qualified medical expenses to remain tax-free. This broad category includes doctor visits, prescription medications, dental care, vision care, and medical devices. A complete, exhaustive list of eligible expenditures is maintained in IRS Publication 502.
Withdrawing funds for non-medical purposes prior to age 65 triggers ordinary income taxes plus a steep 20% IRS penalty. Once the account holder turns 65, the 20% penalty disappears, allowing penalty-free withdrawals for any purpose (though standard income tax applies to non-medical withdrawals).
HSA vs. FSA: Key Differences
While both accounts offer tax advantages, their operational mechanics differ entirely:
- Timeframe: HSAs allow tax-deferred accumulation over decades. FSAs are generally "use-it-or-lose-it" accounts that expire shortly after the calendar year concludes.
- Investment Growth: HSAs offer true brokerage-style investing in equities and index funds, functioning similarly to a Roth IRA. FSAs typically sit as stagnant cash accounts.
Should You Invest Your Entire HSA Balance?
The ideal asset allocation depends on your personal health and financial liquidity. Young, healthy individuals with robust emergency funds outside their HSA can safely invest 100% of their balance for long-term growth. Conversely, individuals with chronic medical needs or steep out-of-pocket deductibles should retain a healthy cash cushion within the account to cover immediate medical bills without being forced to liquidate equities during a market downturn.
Implications: The Future of Consumer-Directed Healthcare
As healthcare costs continue to climb and employment models diversify, the Health Savings Account is rapidly transitioning from a niche financial product into a cornerstone of American wealth planning.
For the self-employed worker, gig economy operator, and budget-conscious family alike, utilizing a top-tier HSA provider is no longer just a tactical way to pay for a doctor’s visit—it is an indispensable macroeconomic strategy. By pairing a high-deductible health plan with a zero-fee, high-performance HSA administrator, consumers can effectively insulate themselves from healthcare inflation while building a robust, tax-sheltered nest egg for retirement.