When financial planners discuss comprehensive safety nets, the conversation almost invariably turns to life insurance, health insurance, and emergency savings funds. Yet, one of the most vital layers of financial protection is frequently overlooked: disability insurance. While many workers spend decades protecting their physical property and life earnings, they leave their most valuable asset completely unprotected—their ongoing ability to earn a living.
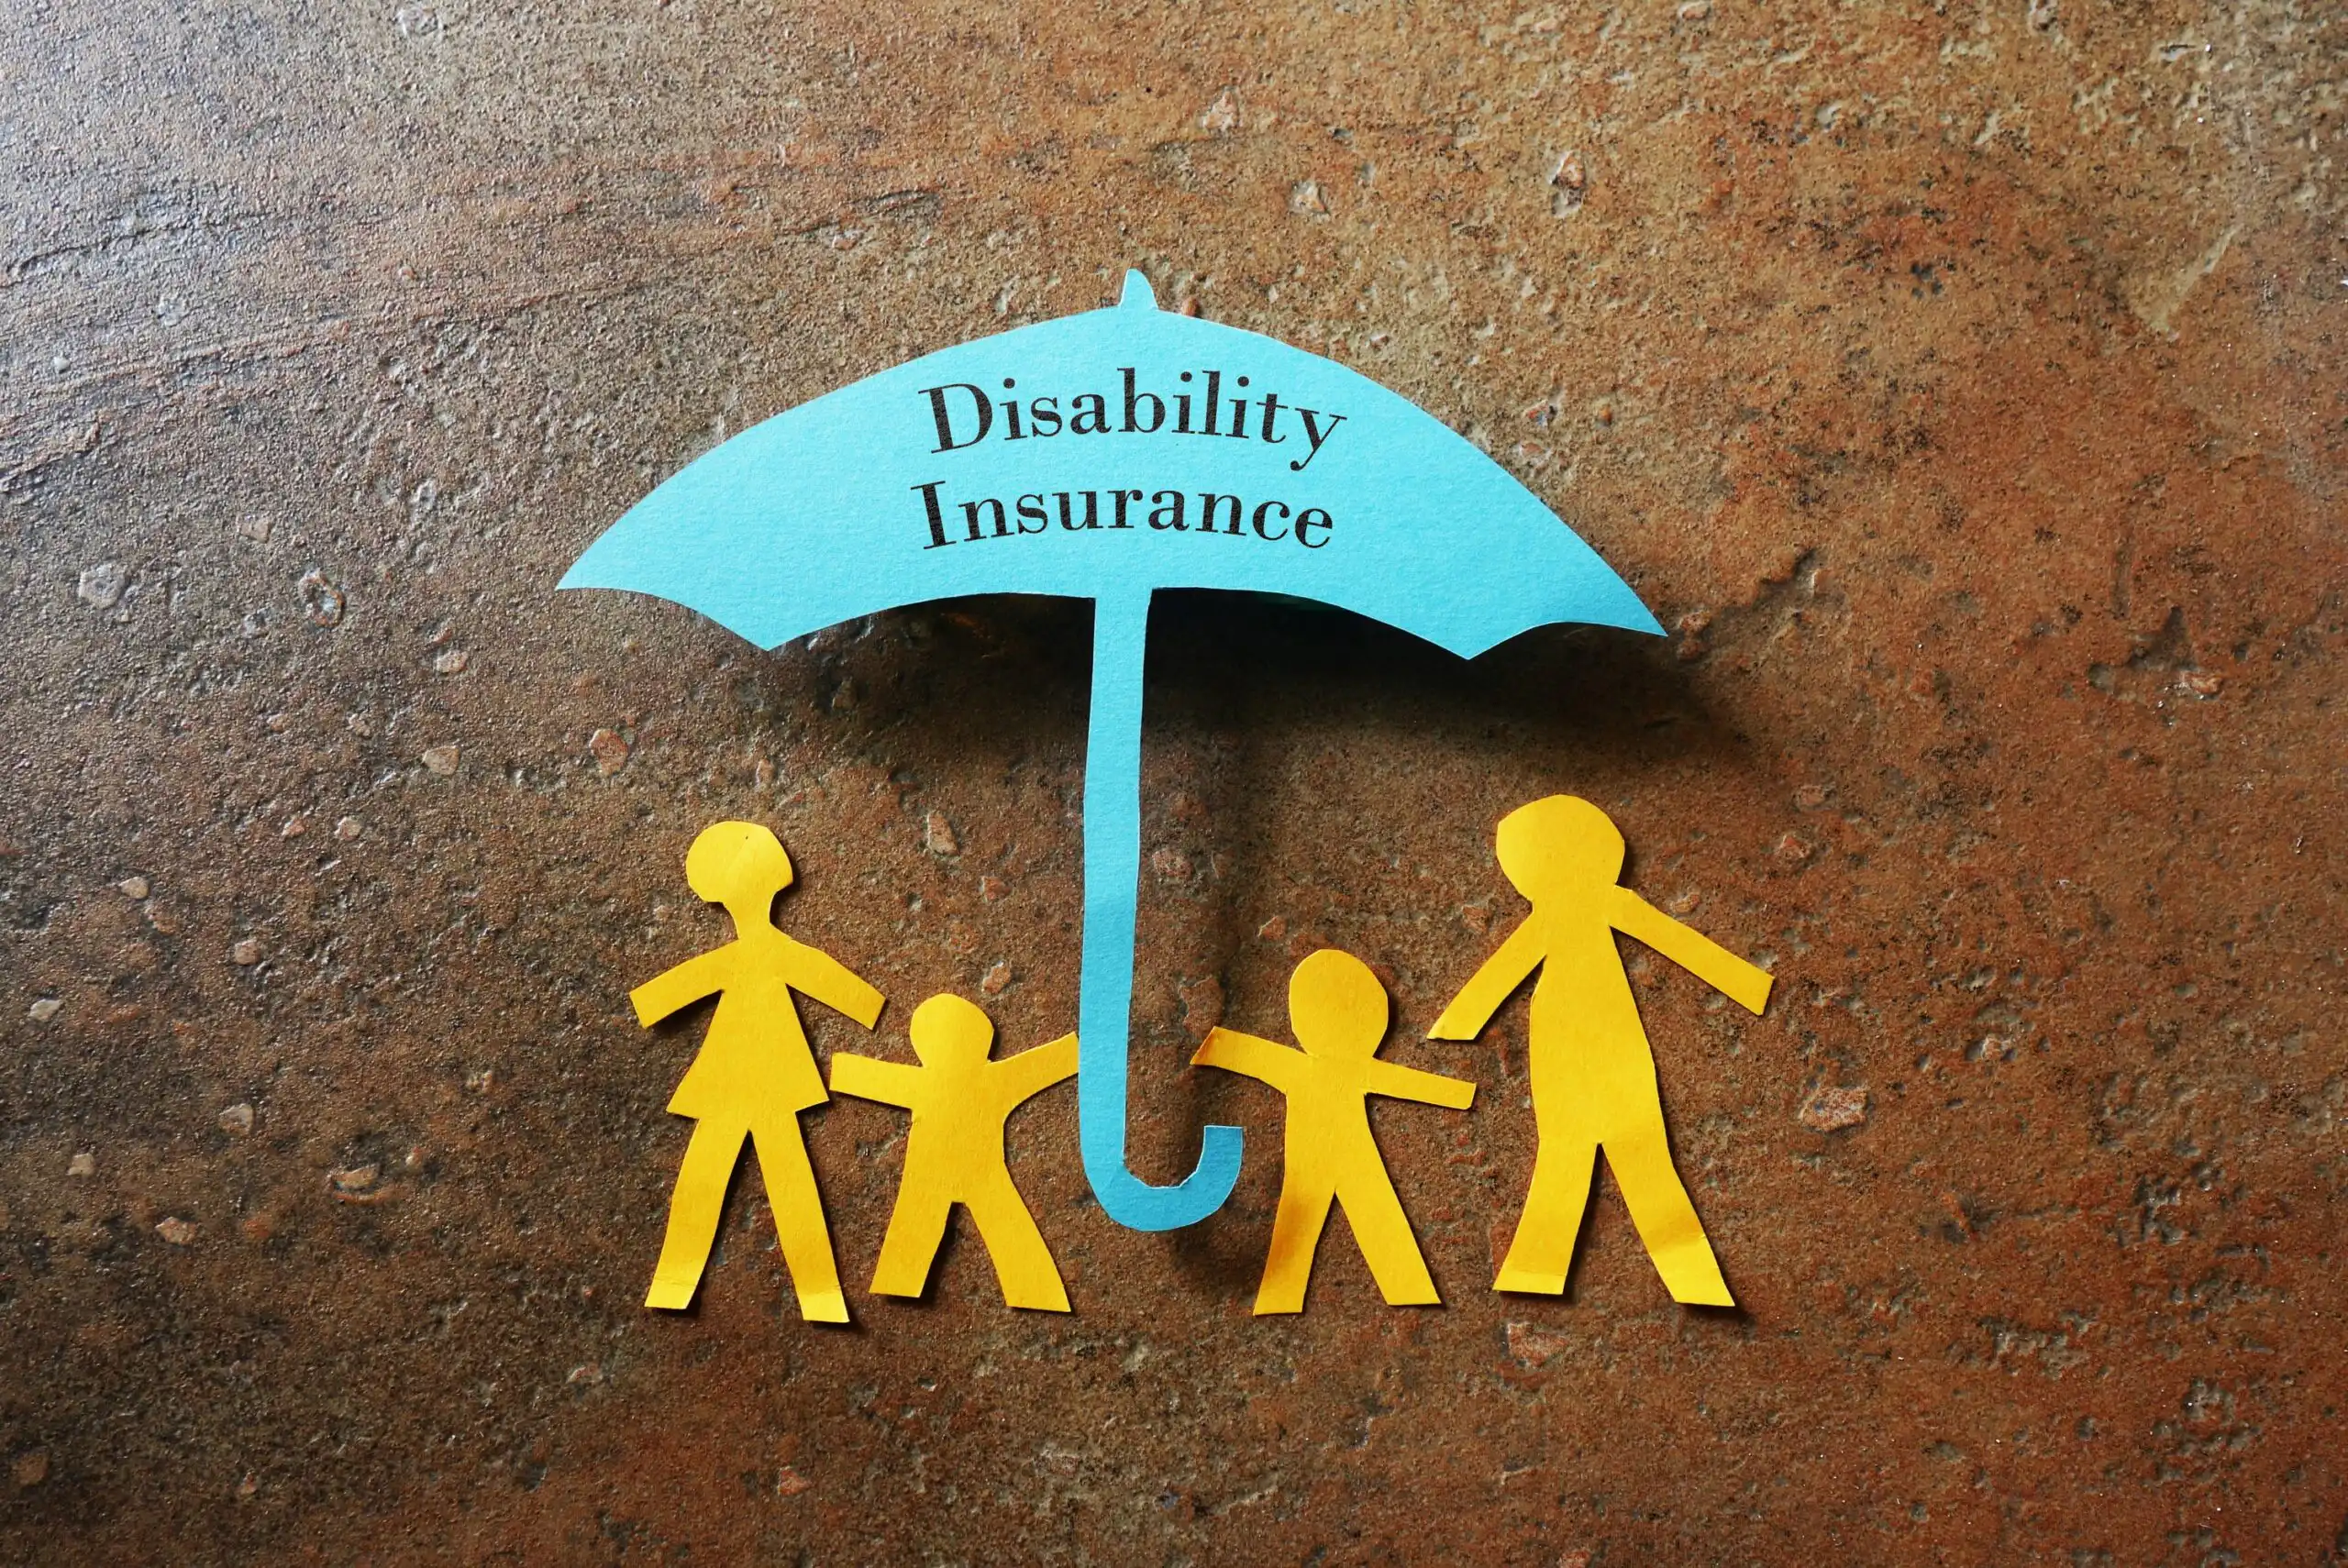
An unexpected illness or severe injury can upend a household overnight, instantly halting cash flow while mounting medical bills pile up. Disability insurance steps in to bridge that gap, replacing a significant percentage of your pre-tax income if you become physically unable to work.
To help consumers navigate this complex market, our financial analysis team evaluated several top-tier disability insurance providers. We rigorously compared their structural benefits, premium costs, elimination periods, definitions of disability, and overall value propositions to bring you the definitive guide on the best disability insurance companies available today.
Main Facts: Understanding the Disability Insurance Landscape
At its core, disability insurance is a contract between you and an insurance provider. In exchange for regular, agreed-upon monthly premium payments, the insurer promises to pay out a monthly tax-free benefit—typically ranging from 50% to 70% of your pre-disability income—should an injury or sickness prevent you from performing your job duties.
Despite its importance, the disability insurance sector remains misunderstood. Many consumers mistakenly assume that government programs like Social Security Disability Insurance (SSDI) will automatically catch them if they fall. In reality, SSDI applications face notoriously strict approval guidelines, lengthy waiting periods, and notoriously high denial rates for initial claims.
Key pillars of disability insurance include:
- Elimination Periods: The waiting period between the onset of your injury or illness and when benefit payouts actually begin.
- Benefit Periods: The length of time you will continue to receive payouts if you remain disabled.
- Definitions of Disability: The strict criteria insurers use to determine whether you qualify for payouts (ranging from "own occupation" to "any occupation").
Chronology and Industry Evolution: How Coverage Has Adapted
The concept of income protection dates back to the late 19th century when mutual aid societies and early life insurance companies began offering rudimentary accident policies. Over the decades, as the workforce shifted from heavy manual labor to corporate, technical, and remote environments, the nature of disabling conditions evolved.
Historically, securing disability insurance was a cumbersome, paper-heavy process requiring invasive paramedical exams, blood draws, and weeks of underwriting delays. However, the insurance industry has experienced a rapid digital transformation over the last decade.
- Early 2000s: Traditional agents dominated the landscape. Purchasing a policy required multiple in-person meetings, physical medical evaluations, and opaque underwriting standards where applicants had little insight into pricing logic.
- 2010s to 2020: Online brokers and fintech disruptors emerged, streamlining the quote-comparison process and making short- and long-term policies more transparent.
- Present Day: Innovative carriers now offer instant-approval pathways, waiving medical exams entirely for low-risk, healthy applicants, and expanding portable coverage options tailored to the modern gig economy and self-employed professionals.
Supporting Data: Evaluating the Top Disability Insurance Providers
We evaluated the marketplace by prioritizing providers that deliver maximum value, operational transparency, and flexible policy options. Here are the top-rated disability insurance companies for various consumer profiles.
1. Breeze Financial & Insurance Services Group: Best Overall
- Ideal For: Tech-savvy workers, entrepreneurs, and those seeking a frictionless digital experience.
- Why We Chose It: Breeze stands out as the best overall provider because it has successfully stripped away the bureaucratic red tape traditionally associated with the insurance sector.
Offering a seamless blend of short- and long-term disability solutions, Breeze allows applicants to complete the entire application process 100% online. Premiums can start as low as $9 a month for young, healthy workers. Furthermore, Breeze offers an instant-approval mechanism for low-risk applicants, completely bypassing traditional, invasive medical exams and lab work. Their transparent underwriting process ensures you are never left guessing where your application stands.
2. MassMutual: Best for Salary and Retirement Income Protection
- Ideal For: Career professionals focused on long-term wealth preservation.
- Why We Chose It: MassMutual delivers highly customizable disability policies backed by unique optional riders.
Their standout feature is a dedicated retirement savings protection rider, which sets aside funds for your retirement accounts even while you are temporarily unable to work, keeping your long-term investment goals on track. Policies cover between 45% and 65% of pre-disability income with competitive baseline premiums. The primary drawback is that policies must be secured through an agent rather than entirely online.
3. Ameritas: Best Built-In Benefits
- Ideal For: Consumers looking for diverse product structures and robust historical backing.
- Why We Chose It: Ameritas offers two distinct structural approaches: DInamic Cornerstone Income Protection® (traditional monthly income replacement) and DInamic Fundamental® (a lump-sum payout if disabled for at least 12 months).
Policyholders can further customize their coverage with riders addressing student loan debt repayment or cost-of-living adjustments (COLA). Tracing its roots back to 1887, Ameritas boasts rock-solid financial stability and an A+ Better Business Bureau rating.
4. Guardian Life Insurance Company of America: Best for Self-Employed Coverage
- Ideal For: Freelancers, small-business owners, and independent executives with fluctuating incomes.
- Why We Chose It: Workers with variable incomes are frequently penalized or underserved by traditional insurers who view them as high-risk. Guardian bridges this gap by offering robust short- and long-term coverage designed specifically for the self-employed, alongside group plans for small-business employers. Guardian maintains an "A" rating with the BBB and enjoys a remarkably low complaint index for a firm of its scale.
5. Principal Financial Group: Best for Portable Coverage
- Ideal For: Mobile professionals changing employers frequently.
- Why We Chose It: Principal Financial Group writes all its disability policies for individuals rather than tied to specific corporate group plans. This makes their coverage entirely portable—meaning your policy stays with you even if you switch jobs, start a new company, or pivot careers. While policies require establishing a relationship with a Principal advisor, clients often secure lower aggregate premiums across their broader financial portfolio.
6. Mutual of Omaha Insurance Company: Best for Coverage After Age 65
- Ideal For: Older workers planning to extend their careers past traditional retirement milestones.
- Why We Chose It: While most disability policies terminate automatically at age 65, Mutual of Omaha offers the unique potential for coverage extending up to age 75, provided the policyholder continues working full-time. Premiums remain level until age 67, after which annual adjustments may occur. Built-in benefits include proportionate disability, terminal illness, and rehabilitation support.
7. Assurity: Best for "Any Occupation" Coverage
- Ideal For: Workers prioritizing flexible, long-term security definitions.
- Why We Chose It: Assurity excels by championing a true "any occupation" standard. Under this framework, you can remain out of your specific workforce and continue collecting benefits if you are unable to perform your trained profession, even if you are technically capable of working in a different, lower-stress role. Policies are guaranteed renewable up to age 65, and monthly earnings under $4,000 often bypass medical exam requirements.
Official Responses and Industry Standards
Insurance regulators, consumer advocacy groups, and industry experts continuously emphasize the necessity of matching policy terms to individual life stages. According to market analysts, the demand for portable, digital-first disability products has surged by over 30% post-pandemic, as workers increasingly embrace remote and freelance arrangements.
Industry compliance guidelines require all licensed disability insurers to explicitly define how they evaluate claims. Major carriers emphasize that transparency during the underwriting phase—disclosing pre-existing conditions accurately—is the single most effective way to guarantee smooth claims processing down the line. Consumers are strongly encouraged to review the fine print regarding Elimination Periods (how long you must wait before benefits trigger) and Benefit Periods (how long payments will last).
Implications: Why Disability Coverage Matters for Your Financial Future
Ignoring disability insurance carries profound financial and lifestyle implications. Consider the following realities:
- The Depletion of Emergency Savings: Financial advisors generally recommend maintaining three to six months of living expenses in an emergency fund. However, the average long-term disability claim lasts significantly longer—often exceeding two to three years. Without insurance, an extended illness quickly wipes out personal savings, retirement accounts, and home equity.
- Impact on Dependents: Families relying on dual or single-income streams face immediate housing, food, and debt repayment crises when cash flow stops. While life insurance protects loved ones after death, disability insurance ensures stability while you are alive and recovering.
- Strategic Financial Planning: Integrating disability coverage into your financial strategy acts as an anchor for long-term investments. Knowing that your cash flow is protected allows you to invest aggressively in retirement vehicles without the constant anxiety of a catastrophic health event derailing your future.
Frequently Asked Questions (FAQs)
What is the difference between short-term and long-term disability insurance?
Short-term disability insurance typically covers you for up to six months following an injury or illness (such as recovery from surgery or childbirth), with waiting periods lasting only a few weeks. Long-term disability insurance covers conditions lasting years or decades, often running until retirement age, with waiting periods that can extend from 90 days up to a full year.
Does disability insurance pay out if you die?
No. Disability insurance is designed exclusively to replace lost wages while the policyholder is alive but unable to work. However, many policies offer short-term survivor benefits (typically spanning up to three months) paid to a spouse or designated beneficiary following the policyholder’s death. For comprehensive death protection, consumers should maintain a separate life insurance policy.
How do I choose the best disability insurance provider?
Begin by evaluating your personal budget, health history, and occupational risk profile. Utilize online comparison tools like Policygenius to evaluate quotes across multiple top-tier carriers, ensuring you select a policy featuring a clear definition of disability, an affordable premium, and a reliable third-party financial strength rating.