Author: Jessica Blais, National Foundation for Credit Counseling (NFCC)
Published: September 1, 2026
Introduction: The Urgent Need for Early Financial Education
In an increasingly cashless, digital-first economy, teaching children the fundamental mechanics of money management has never been more critical. Long gone are the days when a simple piggy bank placed on a bedroom shelf was enough to impart the lessons of fiscal responsibility. Today’s youth are bombarded with digital advertisements, in-app purchases, and peer pressures that encourage instant gratification.
According to financial literacy experts, instilling the habit of saving at an early age is one of the most impactful gifts parents can give their children. When minors learn to delay gratification, set financial goals, and navigate economic setbacks, they transition into adulthood significantly better prepared to handle unexpected expenses. More importantly, they are far less likely to fall into the traps of high-interest consumer debt that plague millions of modern households.
This comprehensive report explores actionable strategies, technological tools, and psychological frameworks designed to help parents raise financially resilient children. Drawing on insights from credit counseling professionals, this guide breaks down how to transform money management from a taboo, stressful chore into an engaging, collaborative family activity.
Main Facts: The Blueprint for Youth Savings
Teaching children about money requires moving past abstract concepts and introducing tangible, real-world experiences. Financial educators emphasize that children learn best by doing rather than listening.
1. Shift from Passive Storage to Active Goal-Setting
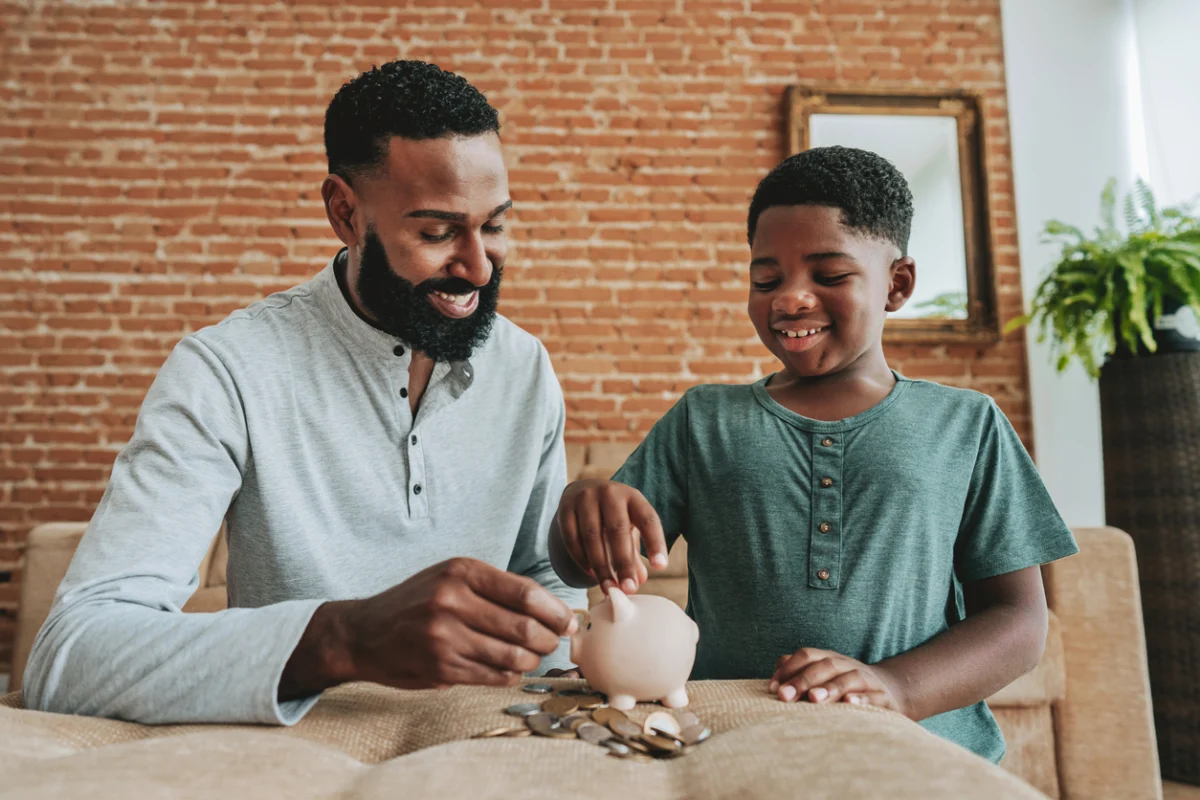
Handing a child a traditional piggy bank and hoping they will naturally feel motivated to fill it is a passive strategy that rarely yields long-term results. Instead, children need a clear "why" behind their saving efforts. Whether they have their eye on a specific video game, a new bicycle, or a trendy clothing item, tying their savings to a concrete, desired object provides the necessary psychological motivation.
2. Leverage Modern Financial Technology
The financial landscape has evolved dramatically, and parents can use this to their advantage. A burgeoning market of kid-friendly financial technology tools—including specialized debit cards, chore-tracking apps, and gamified savings platforms—allows minors to interact with digital currency safely. These tools simulate real-world banking environments while offering guardrails managed by parents.
3. Normalize Financial Conversations
Historically, money has been treated as a taboo subject behind closed doors. Data suggests that as many as 30% of adults hide financial information from spouses or family members, perpetuating a cycle of financial anxiety. Breaking this taboo early by openly discussing savings goals, budgeting, and financial trade-offs normalizes money management and removes the shame often associated with financial struggles.
Chronology: A Step-by-Step Guide to Implementing Savings Habits
Developing lifelong financial habits does not happen overnight. It is a progressive journey that should evolve alongside a child’s cognitive development. Below is a recommended chronological roadmap for parents aiming to integrate financial literacy into their children’s daily lives.
Phase 1: Early Childhood (Ages 4–7) – The Visual Foundation
- The Three-Jar System: Introduce the concepts of "Save, Spend, and Give" using clear jars. Every time a child receives monetary gifts or allowance, help them physically distribute the coins among the three jars.
- Immediate Tangible Rewards: Keep goals short-term. If a child wants a small $5 toy, map out how many weeks of simple chores are required to reach that amount.
Phase 2: Middle Childhood (Ages 8–12) – Goal Setting and Digital Tools
- Specific Item Targeting: Encourage the child to identify a medium-range goal (e.g., a $30 board game). Help them break down the total cost into weekly savings milestones.
- Introduction of Financial Apps: Transition basic allowance tracking to a kid-friendly financial app, allowing them to visualize their progress via digital graphs and charts.
Phase 3: Adolescence (Ages 13–18) – Real-World Tradeoffs and Emergencies
- Managing Setbacks: Teach teenagers how to recalculate their savings timelines when unexpected expenses arise or when income fluctuates.
- The Reality of Trade-offs: Discuss the psychological cost of impulse buys. Encourage teens to weigh the value of an immediate purchase against their long-term savings goals.
Supporting Data and Economic Insights
Financial socialization typically begins at home, yet studies consistently show a significant gap in structured financial education.
- The Debt Crisis Backdrop: According to recent household debt metrics, revolving consumer debt continues to challenge millions of American families. Experts trace many of these adult financial crises back to a lack of foundational budgeting skills established during childhood.
- The Cost of Secrecy: A survey conducted by TD Bank highlighted that approximately 30% of Americans have hidden financial pressures, secrets, or delayed milestones from their family members. This underscores the cultural inertia surrounding money—an inertia that proactive parents can break by involving the entire household in open financial tracking.
- The Power of Micro-Savings: Behavioral economics demonstrates that breaking large goals down into micro-savings milestones increases completion rates by over 60% in both adults and children. When a child sees a $50 goal broken down into five manageable $10 increments, the psychological barrier to saving drops precipitously.
Official Responses and Expert Perspectives from the NFCC
Financial counselors and consumer protection advocates emphasize that teaching kids to save is fundamentally about building psychological resilience.
"When you help your children develop a habit of saving money, they go into adulthood better prepared to cover unexpected expenses and significantly less likely to cycle through chronic debt," notes leadership at the National Foundation for Credit Counseling (NFCC). "It is not merely about accumulating cash; it is about cultivating patience, discipline, and problem-solving skills."
Experts point out that setbacks are an inevitable part of this educational process. Whether a child loses a source of chore income or faces an emergency expense, these moments should not be viewed as failures. Instead, they serve as crucial teachable moments.
"Just like any adult, your child might face setbacks while saving," financial counselors advise. "If their schedule gets interrupted, sit down together to do new calculations and update the timeline. This teaches them that financial setbacks are temporary and solvable with proper planning."
Furthermore, the NFCC stresses that parents must lead by example. Children closely observe parental behaviors regarding money. Initiating an open family savings challenge—where parents openly track their own emergency funds or vacation savings alongside their children—reinforces accountability and mutual support.
Implications: Building Long-Term Financial Resilience
The long-term implications of implementing these early savings strategies extend far beyond a child’s piggy bank balance. By demystifying personal finance, parents equip their children with a psychological armor against modern consumerism.
1. Mitigating Future Economic Stress
Adults who practiced structured saving and goal-setting in their youth report lower levels of financial anxiety. They possess the mental frameworks required to weather job loss, medical emergencies, or inflationary pressures without panicking or resorting to predatory lending options.
2. Fostering Healthy Consumer Habits
Understanding the concept of opportunity cost—the idea that spending money on one item means sacrificing the ability to buy another—reshapes a child’s relationship with material goods. They learn to evaluate purchases critically rather than giving in to impulse marketing tactics.
3. Strengthening Family Bonds
When financial goals are treated as team efforts rather than individual burdens, households experience deeper communication. Celebrating a child’s milestone—whether it is saving $20 for a charity donation or reaching a $100 toy fund—creates positive emotional associations with financial prudence.
Next Steps for Families
Parents who feel uncertain about how to integrate these practices into an already busy household budget do not have to navigate the process alone. Professional resources, including budget-mapping tools and guidance from NFCC-certified credit counselors, are readily available to help families build sustainable financial wellness blueprints for both parents and children alike.