WASHINGTON — In the ever-evolving debate over international tax reform, a seductive economic theory has steadily gained traction among legal scholars and progressive economists: if a government fixes its corporate tax base—most notably by implementing full expensing and closing profit-shifting loopholes—the economic penalties of high tax rates effectively vanish.
This conceptual framework has now been taken to its logical extreme. In a forthcoming Tax Law Review article titled “Taxation and Deglobalization,” prominent legal scholar Reuven Avi-Yonah argues that these structural tax reforms clear the path for a staggering corporate income tax rate of up to 80 percent on multinational corporations with massive global profits.
While the intellectual undercurrent of "fix the base, raise the rate" enjoys support from various prominent policy analysts, a rigorous economic evaluation reveals a dangerous flaw. Although structural reforms like full expensing vastly improve economic efficiency and reduce the growth-inhibiting nature of business taxation, they do not create a free pass for confiscatory tax rates. Real-world complications—ranging from uncompensated entrepreneurial "sweat equity" to asymmetric loss treatments and the realities of progressive corporate rate structures—mean that tax rates always matter.
Main Facts: The "Fix the Base, Raise the Rate" Movement
The core premise of the Avi-Yonah thesis, alongside similar arguments floated by analysts such as Kimberly Clausing, Jason Furman, Michael Linden, and Samantha Jacoby, rests on the notion that traditional economic anxieties regarding high corporate tax rates are primarily artifacts of a poorly designed tax code.
When a tax base is riddled with distortions, high rates amplify those distortions, encouraging corporations to engage in profit shifting—the practice of artificially relocating profits from high-tax nations to low-tax jurisdictions and tax havens. This non-neutrality forces governments to lean on higher statutory rates to capture static revenue targets, which in turn penalizes domestic capital formation, depresses worker productivity, and stifles wage growth.
To combat this, scholars advocate for comprehensive structural overhauls. Chief among these is full expensing, a policy that allows businesses to immediately deduct the full cost of capital investments in new technology, machinery, and structures rather than depreciating them over decades. When paired with limitations on interest deductions and border adjustments—characteristics often associated with a destination-based cash flow tax (DBCFT)—these reforms neutralize major avenues of profit shifting.
However, while traditional analyses treat full expensing as a powerful tool to minimize the economic harm of taxation, Avi-Yonah asserts that an idealized tax base entirely neutralizes the tax rate’s effect on normal corporate investments. Under this assumption, he proposes a progressive corporate tax structure that levies a marginal rate as high as 80 percent on global profits exceeding $10 billion, justified in part by the rise of economic deglobalization, which theoretically makes it harder for firms to flee the U.S. market without losing access to consumers.
Chronology: The Evolution of Modern Tax Reform Debates
To understand how the corporate tax debate arrived at proposals for an 80 percent rate, it is necessary to trace the intellectual milestones that shaped modern tax policy:
- The Hall-Jorgenson Framework (1967): Economists Robert Hall and Dale Jorgenson formalize the standard neoclassical model of the user cost of capital, mathematically demonstrating that under a system of pure cash-flow taxation (or full expensing combined with neutral cost recovery), the statutory tax rate drops out of the investment decision formula entirely.
- The 2017 Tax Cuts and Jobs Act (TCJA): The United States implements major structural changes, temporarily introducing full expensing (bonus depreciation) for short-lived capital investments, which refocuses mainstream economic attention on the pro-growth mechanics of cost recovery.
- The Global Minimum Tax Era (2020–Present): Driven by the OECD and the G20, international discussions pivot toward curbing profit shifting and establishing minimum corporate effective tax rates, sparking renewed debates among American scholars over how to tax multinational corporate rents.
- The Deglobalization Thesis (Recent): Legal and economic scholars begin arguing that geopolitical shifts toward deglobalization reduce corporate mobility. This premise forms the foundation of Reuven Avi-Yonah’s forthcoming Tax Law Review paper, which argues that captive domestic markets can sustain unprecedented corporate tax rates if the tax base is first cleansed of structural defects.
Supporting Data and Economic Theory: Why the Math Breaks Down
The theoretical justification for high tax rates under full expensing relies strictly on the Hall-Jorgenson user cost formula. In standard economic theory, an investor undertakes a capital project only if its expected pre-tax return clears a minimum threshold, known as the user cost of capital ($c$):
$$c = fracr + delta1 – tau (1 – z)$$
Where $r$ represents the required after-tax return, $delta$ is economic depreciation, $tau$ is the tax rate, and $z$ represents the present value of cost-recovery deductions per dollar invested.
Under true full expensing, the present value of deductions equals the initial investment ($z = 1$). When substituted into the equation, the term $(1 – z)$ becomes zero, causing the tax rate ($tau$) to vanish from the calculation entirely. The formula simplifies to:
$$c = r + delta$$
On paper, this suggests that investment decisions are entirely insulated from the corporate tax rate. For low or moderate rate adjustments, this neoclassical model serves as a remarkably reliable approximation. However, extending this logic to justify an 80 percent top marginal tax rate ignores critical, real-world departures from the standard model.
1. Uncompensated Entrepreneurial Effort ("Sweat Equity")
Real-world business creation rarely begins with fully deductible explicit capital alone. Innovation is heavily driven by early-stage entrepreneurs and founders who routinely work for sub-market wages—or no wages at all—while launching a business.
Because tax systems cannot easily accommodate or price a business deduction for this uncompensated "sweat equity" (implicit wages), a vital component of the investment cost goes entirely unrecovered. When factoring in an entrepreneur’s opportunity cost ($omega$) alongside an unindexed tax rate, the tax rate re-enters the investment calculation with a vengeance.
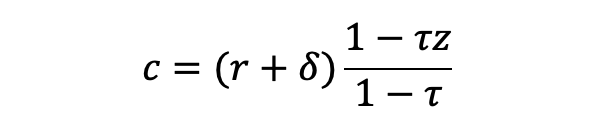
Economic modeling shows that the cost of raising tax rates is non-linear. While hiking a business tax rate from 21 percent to 31 percent imposes a relatively modest increase on the required pre-tax return, jumping from 70 percent to 80 percent exponentially spikes the required return—by roughly 31 percent under standard sensitivity analyses. The marginal economic penalty of rate hikes explodes at higher baseline levels.
2. Asymmetric Treatment of Gains and Losses
Furthermore, cost offsets in the real world are rarely symmetric. Even when capital investments are formally eligible for full expensing, businesses frequently find their deductions delayed or entirely lost if they operate at a loss. Historical data on venture-backed startups reveals that roughly 55 percent ultimately terminate at a loss, meaning their accumulated tax deductions can never be fully realized.
3. Progressive Rate Structures and Intertemporal Asymmetry
Avi-Yonah’s proposal introduces an additional layer of distortion: a progressive rate structure targeting profits over $10 billion. This creates severe intertemporal asymmetries over a firm’s life cycle. A business that incurs heavy startup and early development costs under a low-tier tax rate, only to have its mature, highly profitable operations taxed at an 80 percent rate, faces a heavily distorted investment hurdle. The timing, discounting, and interaction of progressive brackets inevitably drag the tax rate back into the user cost equation.
Official Responses and Stakeholder Perspectives
The debate over the "fix the base, raise the rate" philosophy has drawn sharp divisions across the economic policy community:
- Proponents of Structural Overhaul: Scholars like Avi-Yonah, Kimberly Clausing, and Jason Furman argue that traditional worries about corporate flight are increasingly outdated. They contend that globalization is receding, supply chains are reshoring, and multinational enterprises are increasingly dependent on access to the lucrative U.S. consumer market. From this perspective, aggressive taxation of "supernormal returns" (monopoly rents or excess profits) captured by dominant firms can fund critical public investments without crushing ordinary business formation.
- Skeptics and Free-Market Analysts: Organizations like the Tax Foundation, alongside economists such as Kyle Pomerleau, strongly push back against the notion that tax rates do not matter once expensing is achieved. Critics emphasize that admiring full expensing should not morph into the dangerous illusion that tax rates are economically inert. They warn that an 80 percent corporate rate—even if applied exclusively to firms earning over $10 billion—would severely degrade dynamic incentives for innovation, encourage clever corporate avoidance strategies, and ultimately pass the economic burden down to workers through lower wages and reduced productivity.
Implications: The Dangers of Confiscatory Corporate Taxation
The push to marry structural tax base reforms with confiscatory top tax rates carries profound implications for the future of American economic competitiveness.
Adopting policies that move the U.S. tax code toward a consumption-based or destination-based framework—such as full expensing and measures that eliminate profit-shifting incentives—would undeniably generate significant pro-growth dividends. These reforms lower the cost of capital, encourage capital deepening, and modernize an otherwise sluggish tax apparatus.
However, treating these structural fixes as a blank check to hike statutory rates to historically unprecedented levels represents a fundamental misunderstanding of economic reality. Because taxation inevitably interacts with uncompensated entrepreneurial sweat equity, asymmetric loss recovery, and the dynamic life cycles of growing enterprises, the tax rate always matters.
Attempting to capture corporate rents via an 80 percent top rate under the assumption that deglobalization has trapped capital within national borders risks severe economic fallout. Rather than fostering a fairer economy, punishing mega-corporations with confiscatory rates threatens to strangle the very innovation, risk-taking, and capital investment required to sustain long-term economic growth.