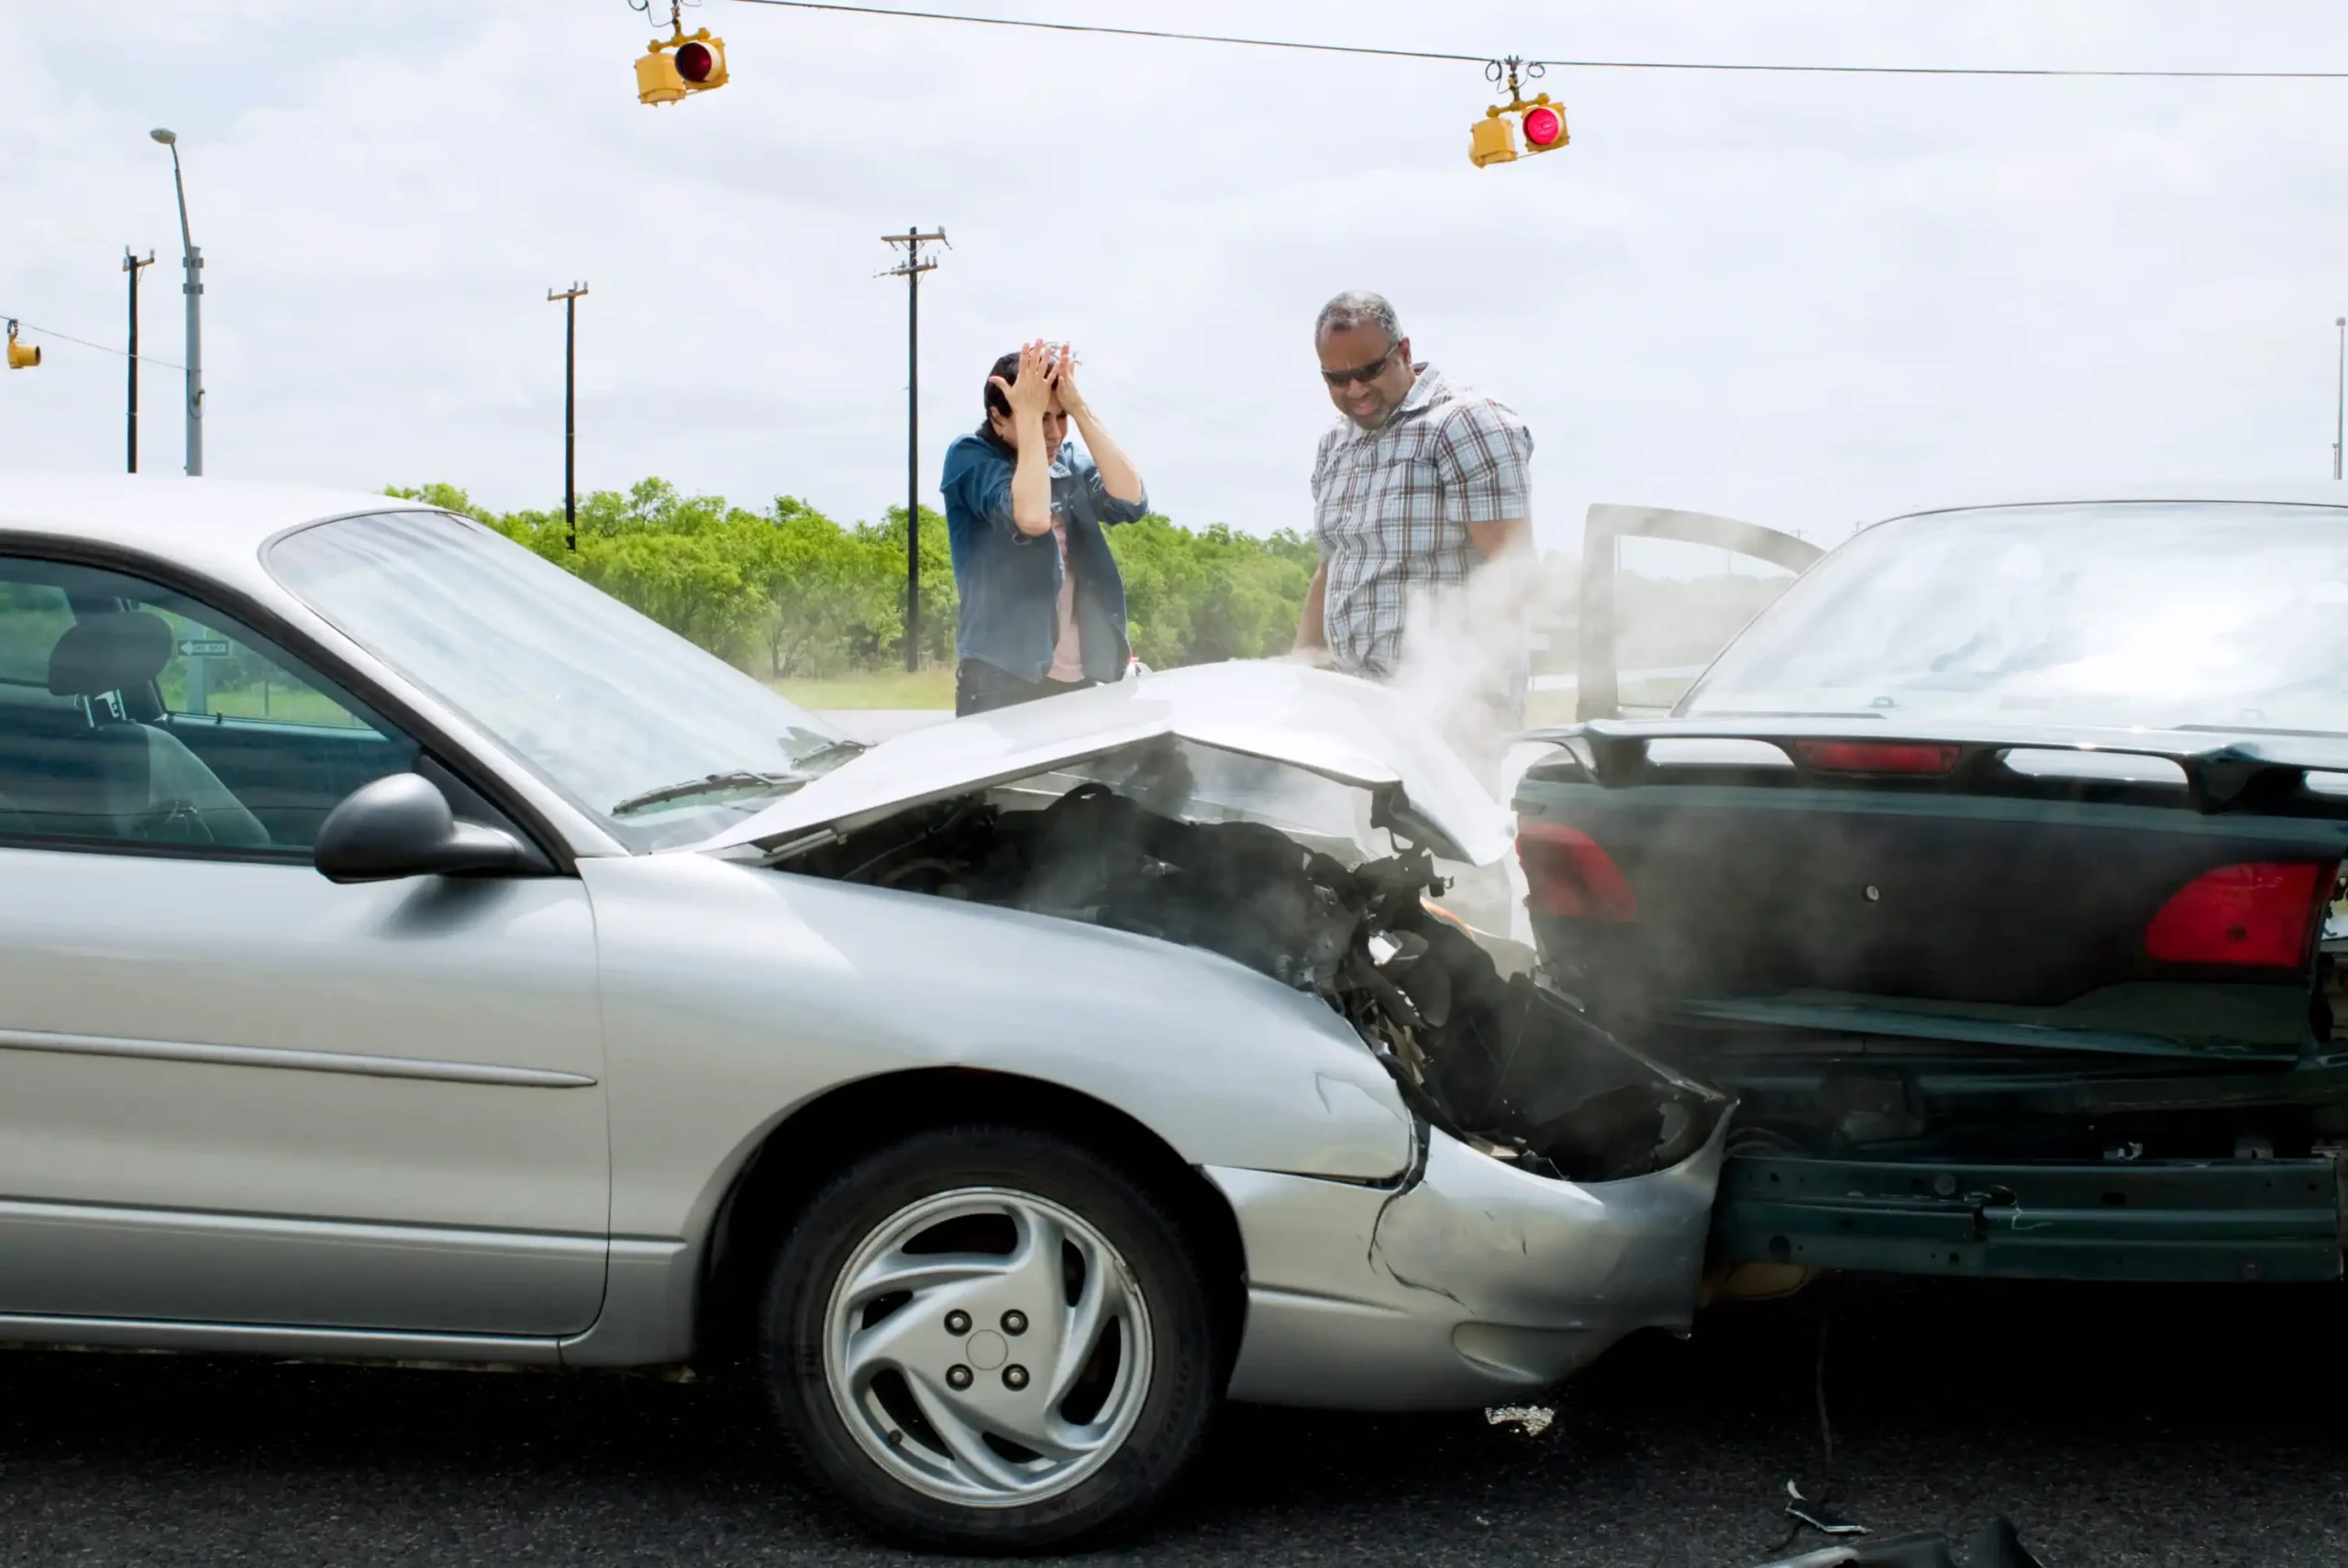
For millions of motorists, paying for car insurance is a routine, albeit unwelcome, monthly expense. Yet, beyond being a legal mandate across all 50 states, adequate auto coverage serves as a critical financial safety net. Whether you own your vehicle outright, are currently locked into a car lease, or are paying off a traditional auto loan, choosing the right insurance provider can mean the difference between financial security and devastating out-of-pocket debt following an accident.
With countless insurers vying for your business—each promising the lowest rates, the best discounts, or the most streamlined mobile apps—finding the right policy can feel overwhelming. To help you make an informed decision, we have broken down the market’s top-performing car insurance companies, explored the fundamental types of coverage, analyzed the core factors impacting your rates, and outlined a clear methodology for selecting the ideal provider for your unique lifestyle.
Main Facts: The Current Auto Insurance Landscape
Auto insurance requirements vary primarily by state, but the underlying purpose remains uniform: to protect drivers from the staggering financial liabilities associated with vehicle crashes, injuries, and property damage. State laws dictate minimum liability limits, but drivers who finance or lease their vehicles face stricter lender requirements, typically needing comprehensive and collision coverage to safeguard the lender’s financial stake in the car.
Because the industry is fiercely competitive, premiums fluctuate wildly based on provider, location, vehicle type, and driver profile. The market is broadly split between direct-to-consumer online insurers—who often pass down savings through low overhead—and traditional agency-based companies that lean heavily on personalized customer service.
To help consumers navigate this crowded ecosystem, industry experts evaluate insurers based on multiple performance indicators, including geographical availability, pricing structures, new customer incentives, general policy discounts, claims handling efficiency, and customer complaint volumes.
Chronology and Evolution of Modern Auto Insurance Shopping
The process of shopping for and managing car insurance has undergone a radical transformation over the past few decades, shifting from paper-heavy, agent-led transactions to instant digital experiences.
- The Traditional Era (Pre-2000s): For decades, securing auto insurance required sitting down with a local, captive insurance agent or calling a toll-free hotline. Quotes took days to process, and policy management involved physical paperwork, mail-in payments, and in-person consultations for claims adjustments.
- The Aggregator and Direct-to-Consumer Boom (2000s–2010s): The rise of the internet birthed online quote aggregators and direct-to-consumer models. Insurers like Geico and Progressive popularized immediate online quoting systems, allowing consumers to compare rates across multiple companies in minutes without leaving their homes.
- The Telematics and App-Driven Revolution (Present): Today, telematics and smartphone apps dominate the industry. Insurers increasingly rely on behavioral data tracking—via mobile apps or plug-in dashboard devices—to monitor driving habits in real-time. Companies like Root Insurance and Nationwide’s SafeRide program have made usage-based insurance a cornerstone of modern pricing, shifting the paradigm from demographic-based risk assessment to merit-based rewards for safe drivers.
Supporting Data: The Market’s Top Insurance Providers
Based on rigorous evaluations of pricing, customer satisfaction, discounts, and specialized offerings, several standout companies currently lead the market. Each excels in distinct categories, ensuring options for diverse driver profiles.
1. State Farm: Best Overall
State Farm may not disrupt the industry with radical pricing experiments, but it delivers undeniable, consistent value for drivers from coast to coast. Its widespread availability, extensive network of local agents, and robust financial stability make it the premier choice for overall auto insurance reliability.
2. Root Insurance: Best for Good Drivers
Root Insurance operates on a unique premise: doing car insurance the "fair way" by monitoring your actual driving habits via a mobile app. Safe drivers are rewarded with significantly lower premiums, with the average customer reportedly saving up to $900 annually. Roadside assistance is built into every policy, and the streamlined app-based onboarding takes under a minute.
3. Auto-Owners Insurance: Best Customer Service
While Auto-Owners is not available nationwide—notably missing from massive states like California and Texas—it boasts legendary customer service anchored by a network of loyal, hardworking independent agents. For those living within its footprint who value a human touch, Auto-Owners is exceptionally difficult to beat.
4. USAA: Best for Service Members and Their Families
USAA restricts eligibility to active-duty military, veterans, and their immediate families, leaving out roughly 95% of the general U.S. population. However, for those who qualify, USAA offers stellar policy options and sign-up incentives that reportedly save new customers upwards of $700 in their first year.
5. Nationwide: Best Safe-Driving Discount
Nationwide strikes a balance between digital accessibility and agent-assisted sales. While its baseline customer satisfaction ratings are middle-of-the-pack, it shines brightly in competitive pricing and safety incentives. Drivers willing to use a tracking device qualify for an instant 10% discount, with potential savings scaling up to 40% through the SafeRide program.
6. Amica: Best General Policy Discounts
Amica is a smaller insurer known for an unusually rich array of policy discounts. Multi-policy bundles (home and auto) slash rates by up to 30%, while multi-car households can save up to 25%. Furthermore, Amica’s rare dividend policies can pay back up to 20% of premiums over time for policyholders who maintain a claim-free record.
7. Allstate: Best for Roadside Assistance
Allstate combines high brand recognition with competitive premiums and standout driver support. Notably, it is the only major national insurer offering multiple 24/7 roadside assistance programs and travel insurance coverages akin to a AAA membership, with standalone annual plans starting as low as $89.
8. Progressive: Best Application Process
Progressive features abundant discounts and policy add-ons, backed by solid financial standing. Its primary differentiator is a remarkably smooth digital onboarding process that guides users effortlessly through quote customization, backed by responsive chat representatives if human assistance is required.
9. Geico: Best for Consistently Low Premiums
For motorists prioritizing low rates above white-glove service, Geico is the undisputed heavyweight. Focusing heavily on digital efficiency from onboarding to claims processing, the company helps average drivers save up to $500 annually upon switching, making it ideal for budget-conscious consumers.
Official Responses and Industry Standards
When assessing the health and reliability of auto insurance companies, regulatory bodies and consumer advocacy groups look to standardized metrics rather than marketing claims.
Industry analysts evaluate insurers based on consumer complaint ratios filed with state insurance commissioners and the National Association of Insurance Commissioners (NAIC). Lower complaint ratios—adjusted for the total volume of active policyholders—signal a company’s ability to handle claims fairly and maintain customer satisfaction.
Furthermore, independent evaluators like J.D. Power regularly survey tens of thousands of policyholders to rank insurers on customer satisfaction indices, examining metrics such as billing practices, policy offerings, and claims interactions. Additionally, Crash Network’s Collision Repair data helps consumers understand how specific insurers treat repair shops and whether they hinder or facilitate quality, timely vehicle restoration following an accident.
Implications: Understanding Coverage Types and Cost Factors
Choosing the right policy requires a firm grasp of the mechanics of auto insurance and the financial implications of underinsurance.
Core Types of Car Insurance
- Liability Insurance: Covers bodily injury and property damage you cause to others in a crash. This is legally mandated in nearly all states.
- Collision Insurance: Pays for damages to your vehicle resulting from a collision with another car or a stationary object like a telephone pole.
- Comprehensive Insurance: Protects your car against non-collision incidents, such as theft, vandalism, fire, or weather-related natural disasters.
- Uninsured/Underinsured Motorist Coverage: Steps in to pay for your damages if you are hit by a driver who lacks adequate insurance.
- Gap Insurance: Crucial for leased or financed cars. Because vehicles depreciate rapidly, your loan balance may exceed the car’s actual cash value; gap insurance covers the difference if the vehicle is totaled.
What Drives Your Rates?
Insurance companies evaluate risk using several core criteria. Higher perceived risk directly translates to elevated premiums:
- Driving Record: Speeding tickets, at-fault accidents, and DUIs dramatically spike costs.
- Location: Urban areas with high traffic congestion and theft rates typically face higher insurance costs than rural regions.
- Vehicle Make and Model: Cars that are expensive to repair, prone to theft, or boast high-horsepower engines cost more to insure.
- Age and Experience: Younger, inexperienced drivers pay higher premiums due to statistically higher accident rates.
- Credit Score: In most states, insurers use credit-based insurance scores to predict the likelihood of a customer filing a claim.
Conclusion: How to Choose the Best Policy for Your Needs
Securing high-quality auto insurance at an affordable rate demands discernment. Drivers should look beyond flashy advertisements and focus on companies offering a balanced combination of competitive base premiums, generous discount structures (such as safe-driving, bundling, and loyalty perks), transparent claims processing, and low customer complaint volumes.
Before committing to a policy, pull multiple quotes using online aggregators, evaluate your specific state requirements against your personal financial assets, and ensure you aren’t paying for superfluous extras—or conversely, leaving yourself dangerously underinsured. By taking a thoughtful, structured approach, you can protect your vehicle, safeguard your financial future, and keep your monthly expenses firmly under control.