For every novice real estate investor stepping into the market, a foundational crossroads emerges early on: Should you purchase a single-family home or a multifamily property? This initial decision dictates more than just property management responsibilities—it fundamentally shapes the speed of cash flow accumulation, the long-term appreciation trajectory, and the scalability of an emerging portfolio.
In a recent comprehensive deep-dive on the Real Estate Rookie Podcast, co-hosts Ashley Kehr and Tony Robinson tackled this age-old debate head-on. By dissecting real-world market data, analyzing active listings, and sharing hard-earned lessons from their own multi-million dollar portfolios, the experts provided a masterclass on how new investors can align property types with personal financial freedom goals.
Main Facts: The Core Differences at a Glance
To understand the debate, investors must first establish clear definitions.
- Single-Family Properties: Typically structured to house a single household under one roof, these assets are ubiquitous across suburban and urban markets alike. While some single-family homes may feature legally permitted Accessory Dwelling Units (ADUs), they remain zoned for single-family use.
- Multifamily Properties: These assets comprise multiple housing units under unified ownership, allowing separate households to occupy the same parcel. This category spans small multifamily (duplexes, triplexes, and quadplexes) to large apartment complexes featuring five or more units.
The fundamental divergence between the two strategies boils down to inventory abundance, financing structures, tenant management dynamics, and market appreciation. Single-family properties offer widespread availability and simpler exit strategies, whereas multifamily assets provide higher combined rental yields and accelerated portfolio scaling through a single acquisition process.
Chronology: The Evolution of an Investor’s Journey
To trace how investors arrive at these distinct asset classes, Kehr and Robinson looked back at their own origin stories in the real estate arena.
The Dual-Path Beginnings
- Ashley Kehr’s Introduction: Kehr kicked off her portfolio with a small duplex in upstate New York, purchased for a modest $17,000. Her primary driving force at the time was immediate cash flow to break free from her W-2 job. Over a decade, her portfolio expanded to include a mix of small multifamily units and select single-family assets.
- Tony Robinson’s Introduction: Robinson took a different route, launching his career entirely through single-family homes and later scaling into short-term rentals and hospitality ventures like a 13-room motel. He has never owned a traditional small multifamily duplex or triplex.
The Learning Curve of Scale
As both investors matured, their perspectives on management evolved. Kehr, who once managed a 40-unit apartment complex alongside a portfolio of individual rentals, noted a surprising counterintuitive reality: while managing the physical infrastructure of 40 units under one roof is vastly simpler for maintenance crews, managing the tenant dynamics is exponentially harder.
Shared hallways, communal dumpsters, single mailrooms, and tight parking lots frequently breed daily interpersonal disputes among tenants living in close quarters. Conversely, single-family tenants operate independently, eliminating shared-space friction.
Supporting Data: Underwriting Real Deals in Today’s Market
Theory is vital, but numbers dictate survival in real estate. To illustrate the mathematical differences, the podcast hosts examined two active properties listed on the market in Memphis, Tennessee, running side-by-side financial analyses assuming a 20% down payment, a 7% mortgage interest rate, 8% vacancy, and 1% annual maintenance/CapEx reserves.
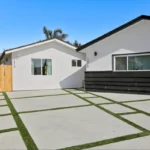
Deal A: The Single-Family Home (Maple Tree Drive)
- Purchase Price: $210,000
- Down Payment (20%): $42,000
- Monthly Expenses: Principal & Interest ($1,100), Property Taxes ($230), Insurance ($120), Maintenance ($175), Vacancy ($128). Total expenses outpace income.
- Projected Rent: $1,600
- Monthly Cash Flow: -$172 per month
Despite pristine new construction, this particular single-family asset operates at a net monthly loss under conservative underwriting. However, single-family assets typically benefit from a broader pool of retail buyers upon exit, translating to stronger long-term appreciation in many suburban markets.
Deal B: The Duplex (Waynoca Avenue)
- Purchase Price: $269,900
- Down Payment (20%): $53,980
- Monthly Expenses: Principal & Interest ($1,400), Property Taxes ($315), Insurance ($160), Maintenance ($225), Vacancy ($200).
- Projected Rent: $1,250 per unit ($2,500 total gross monthly rent)
- Monthly Cash Flow: +$164 per month
While the duplex requires a slightly higher capital outlay, the combined rental income eclipses the single-family benchmark. Crucially, fixed expenses do not double linearly: property taxes on the duplex ($315) are only marginally higher than those on the single-family home ($230), despite generating nearly $1,000 more in monthly gross revenue.
Official Perspectives: Pros and Cons Defined
Single-Family Homes: The Case for Simplicity
- Pros:
- Ubiquitous Inventory: Readily available in virtually every geographic market.
- Easier Appraisals: Appraised primarily using comparable sales data from nearby single-family homes.
- Frictionless Management: Zero shared common areas eliminate disputes over snow removal, landscaping, and parking.
- Stronger Exit Liquidity: A wider pool of retail homebuyers (not just investors) exists upon resale.
- Cons:
- Binary Vacancy Risk: 100% vacancy when a tenant leaves; zero income generated.
- Slower Portfolio Scaling: Requires separate purchase contracts, inspections, and closings for every individual door.
Multifamily Properties: The Case for Scale and Cash Flow
- Pros:
- Accelerated Cash Flow: Multiple income streams under one roof cushion against localized vacancy drops.
- Efficient Acquisitions: Securing a fourplex yields four doors under a single loan, insurance policy, and due-diligence cycle.
- Expense Efficiency: Lower per-door overhead for maintenance coordination and property management.
- Cons:
- Commercial Financing Hurdles: Small and large multifamily properties often require commercial loans, demanding higher down payments (20% to 30%), strict Debt Service Coverage Ratios (DSCR), and annual financial reporting to banks.
- Tenant Friction: Shared spaces can generate frequent interpersonal friction and management headaches.
Implications: Tailoring the Strategy to Personal Financial Goals
Ultimately, neither asset class is universally superior; success hinges entirely on matching the property type to the investor’s overarching life goals and operational bandwidth.
- The Timeline to Financial Freedom: If an investor’s objective is to rapidly replace a full-time W-2 income ("quit yesterday"), the immediate cash flow advantages of small multifamily units or high-yield single-family niches (such as short-term or mid-term rentals) prove critical. If the timeline spans 25 to 30 years toward retirement, appreciation-heavy single-family homes can build substantial generational wealth as mortgages are paid down.
- Execution Capability: As Tony Robinson emphasized, the core question is not which strategy is objectively best on paper, but which strategy the investor can execute most effectively.
- Market Realities: Local market dynamics dictate the verdict. In markets where single-family homes historically outperform small multifamily units in appreciation, a hybrid approach—starting with cash-flowing multifamily units to build a financial foundation, then layering in appreciation-driven single-family homes—offers a balanced roadmap to long-term prosperity.