By Banking Dive Staff | September 30, 2026
In a landmark decision that promises to reshape the regulatory landscape for the nation’s largest financial institutions, the Federal Reserve Board on Wednesday finalized a comprehensive package of rules designed to modernize the bank stress-testing process. The move marks a definitive pivot toward greater transparency and reduced year-to-year volatility in capital requirements, effectively ending years of friction between federal regulators and the banking industry.
The new framework, which has been in the pipeline for nearly a year, introduces structural changes to how the Fed develops its stress scenarios and calculates the stress capital buffers (SCB) that banks must hold to withstand economic downturns. While the Fed asserts these changes will foster a more resilient and accountable regulatory environment, the decision has ignited a fierce internal debate among the Fed’s own governors regarding the long-term impact on financial stability.
Main Facts: The New Regulatory Architecture
The Federal Reserve’s finalized rules fundamentally alter the mechanics of the Comprehensive Capital Analysis and Review (CCAR) and the Dodd-Frank Act Stress Test (DFAST) processes. Two primary components define this regulatory shift:
- Public Comment and Scenario Transparency: The Fed will now be required to invite public comment on its annual stress-test scenarios and any material changes to the models used to evaluate bank performance. This ensures that the assumptions underlying these tests—such as unemployment spikes, interest rate shifts, and GDP contractions—are subject to rigorous external scrutiny before implementation.
- Market Shock Methodology: Under the new rules, banks will be evaluated against two distinct global market shock components annually. The final stress-test result for each institution will be determined by the specific shock that generates the larger loss, ensuring a more conservative, yet predictable, assessment of capital adequacy.
- Capital Buffer Smoothing: Perhaps the most significant change for bank balance sheets is the transition to a two-year average for calculating the Stress Capital Buffer (SCB). Effective in 2028, this methodology aims to dampen the dramatic year-over-year fluctuations in capital requirements that have historically hampered long-term capital planning.
Alongside these final rules, the Fed has also issued a proposal to revise the models used to measure noninterest income. This initiative aims to better capture the diverse ways in which modern financial institutions generate fee income, acknowledging that a one-size-fits-all model often misrepresents the risk profiles of varied business models.
Chronology of a Regulatory Shift
The path to these finalized rules has been marked by litigation, industry lobbying, and a significant change in the Fed’s internal leadership.
The roots of the current reform date back to the early 2020s, as the banking industry grew increasingly vocal about the "black box" nature of Fed models. By December 2024, the frustration reached a boiling point when major trade groups—including the American Bankers Association (ABA) and the Bank Policy Institute (BPI)—filed a lawsuit against the Federal Reserve. The plaintiffs argued that the Fed’s lack of transparency violated the Administrative Procedure Act, preventing banks from understanding or challenging the rationale behind their capital charges.
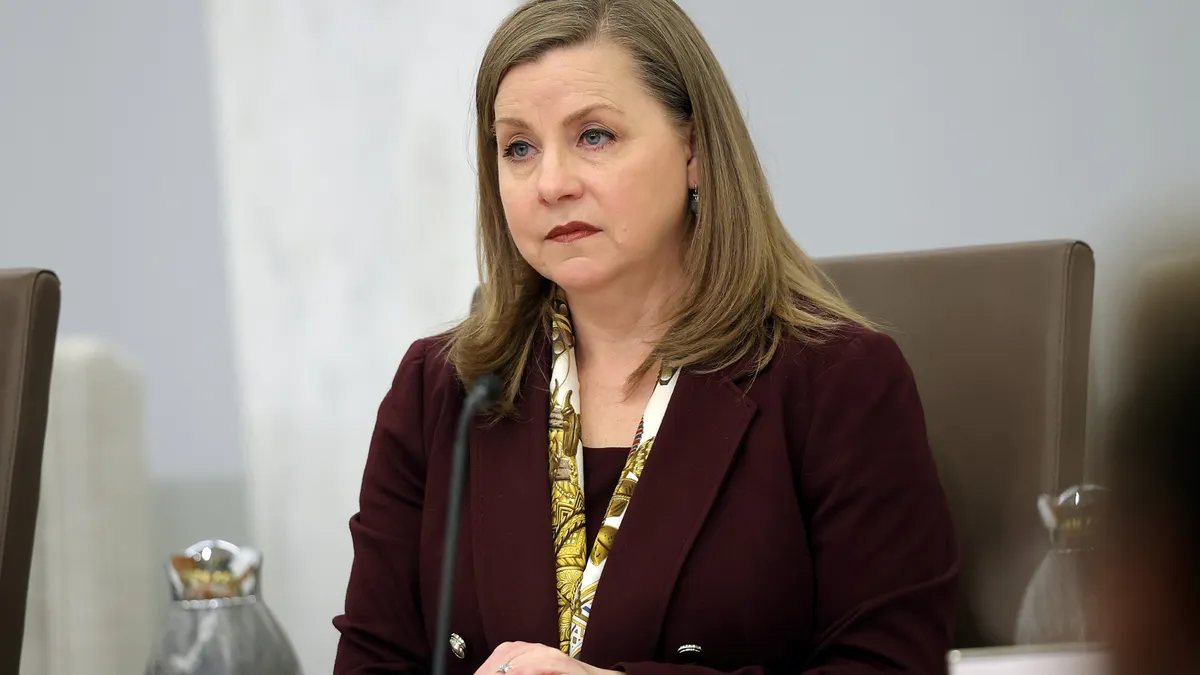
Throughout 2025, the Fed began to signal a willingness to reconsider its approach. The turning point came in October 2025, when the central bank released an initial proposal that mirrored much of what was finalized this week. Michelle Bowman, the Fed’s vice chair for supervision, became a primary architect of this shift, consistently advocating for a more "granular and risk-sensitive" framework. Following a speech in London earlier this month where she teased the impending updates, the Fed moved to finalize the rules, effectively codifying a more collaborative regulatory approach.
Supporting Data and the Volatility Problem
For years, the banking sector has struggled with "model noise"—unpredictable swings in stress-test outcomes that bore little relation to the underlying risk profile of a bank’s portfolio. These fluctuations often forced banks to hold excess capital during benign periods or scramble to raise capital during downturns, a process that arguably stifled lending and economic growth.
The Fed’s own internal analysis suggests that these reforms could cut annual volatility in stress-test-mandated capital requirements by as much as 50%. By averaging the results of the last two annual tests, the Fed creates a "buffer of buffers" that protects banks from the sudden, often inexplicable spikes that have historically plagued the sector.
Furthermore, the revision of the noninterest income model is a direct response to the evolution of bank revenue streams. As banks shift away from traditional net interest margin reliance toward diversified fee-based services, the old models—which often treated all fee income as equally sensitive to economic shocks—were increasingly viewed as inaccurate. The 60-day comment period for this specific proposal will allow market participants to help the Fed refine these models to better reflect modern banking realities.
Official Responses: A Divided Board
The final vote of 6-1 in favor of the rules highlights a deep ideological rift within the Federal Reserve Board.

Vice Chair Michelle Bowman championed the rules as a triumph for institutional integrity. "Today’s changes preserve the [stress test’s] resilience by ensuring that it is transparent, granular, and risk-sensitive," Bowman stated. "The public will now have greater assurance that the risks banks take will be reflected appropriately in their stress test losses and their capital requirements."
However, the lone dissenter, Governor Michael Barr, expressed profound concerns regarding the potential long-term erosion of the stress test’s efficacy. In a strongly worded dissent, Barr argued that while the desire for transparency is understandable, the consequences for financial stability could be severe.
"Disclosure of the stress test models and annual public comment processes on model changes and scenarios will make the stress tests less responsive to emerging risks," Barr warned. "Calcified models will also allow banks to optimize their balance sheets to the test, rather than focusing on underlying risk."
Barr’s fear is that by turning the stress test into a transparent, predictable process, the Fed is essentially providing banks with a "roadmap" to navigate around the rules, potentially allowing them to engage in risky behaviors that fall just outside the parameters of the known, static models.
Industry Implications and Future Outlook
The industry’s reaction to the announcement has been overwhelmingly positive. The ABA and BPI issued a joint statement hailing the reproposal as a victory for the Administrative Procedure Act.
"Transparency and public input have produced a better stress-testing framework that should improve accuracy and allow more thoughtful capital planning at covered banks, with economic benefits to the country," the trade groups noted. They particularly praised the Fed for taking the time to address the specific flaws in the previous models, characterizing the process as a model for future regulatory development.

However, analysts suggest that the "honeymoon" phase may be short-lived. As banks adjust to the new regime, they will likely face increased scrutiny regarding their "model risk management." If banks do indeed begin to optimize their balance sheets to "pass" the test—as Barr fears—the Fed may find itself in a perpetual game of cat-and-mouse, constantly updating its models to catch up with the industry’s sophisticated financial engineering.
Furthermore, the 2028 implementation date for the capital buffer smoothing gives the industry time to adjust, but it also creates a multi-year transition period where regulators and banks must manage two different methodologies.
Ultimately, the Federal Reserve has traded a measure of "regulatory mystery" for "regulatory certainty." Whether this trade-off results in a more stable banking system or a more vulnerable one remains the central question of the post-2026 era. For now, the banking sector has the clarity it has sought for over a decade, but the burden of proof has shifted: it is now up to the industry to prove that this increased transparency will be used for prudent capital management rather than regulatory arbitrage.