In an era of rising litigation costs, record-high settlement awards, and increasingly litigious environments, everyday homeowners and drivers are sitting on a financial powder keg. Most people operate under the comforting assumption that maxing out the standard liability limits on their auto and homeowners insurance policies provides a foolproof safety net.
Unfortunately, that assumption can lead straight to financial ruin.
When a catastrophic accident occurs—whether it’s a multi-vehicle pileup on the highway, a severe slip-and-fall accident at a backyard barbecue, or a bite from a family pet—standard liability caps are often breached within minutes of a jury’s verdict. Once those primary insurance funds are exhausted, the remaining balance doesn’t vanish; it falls squarely on the shoulders of the policyholder.
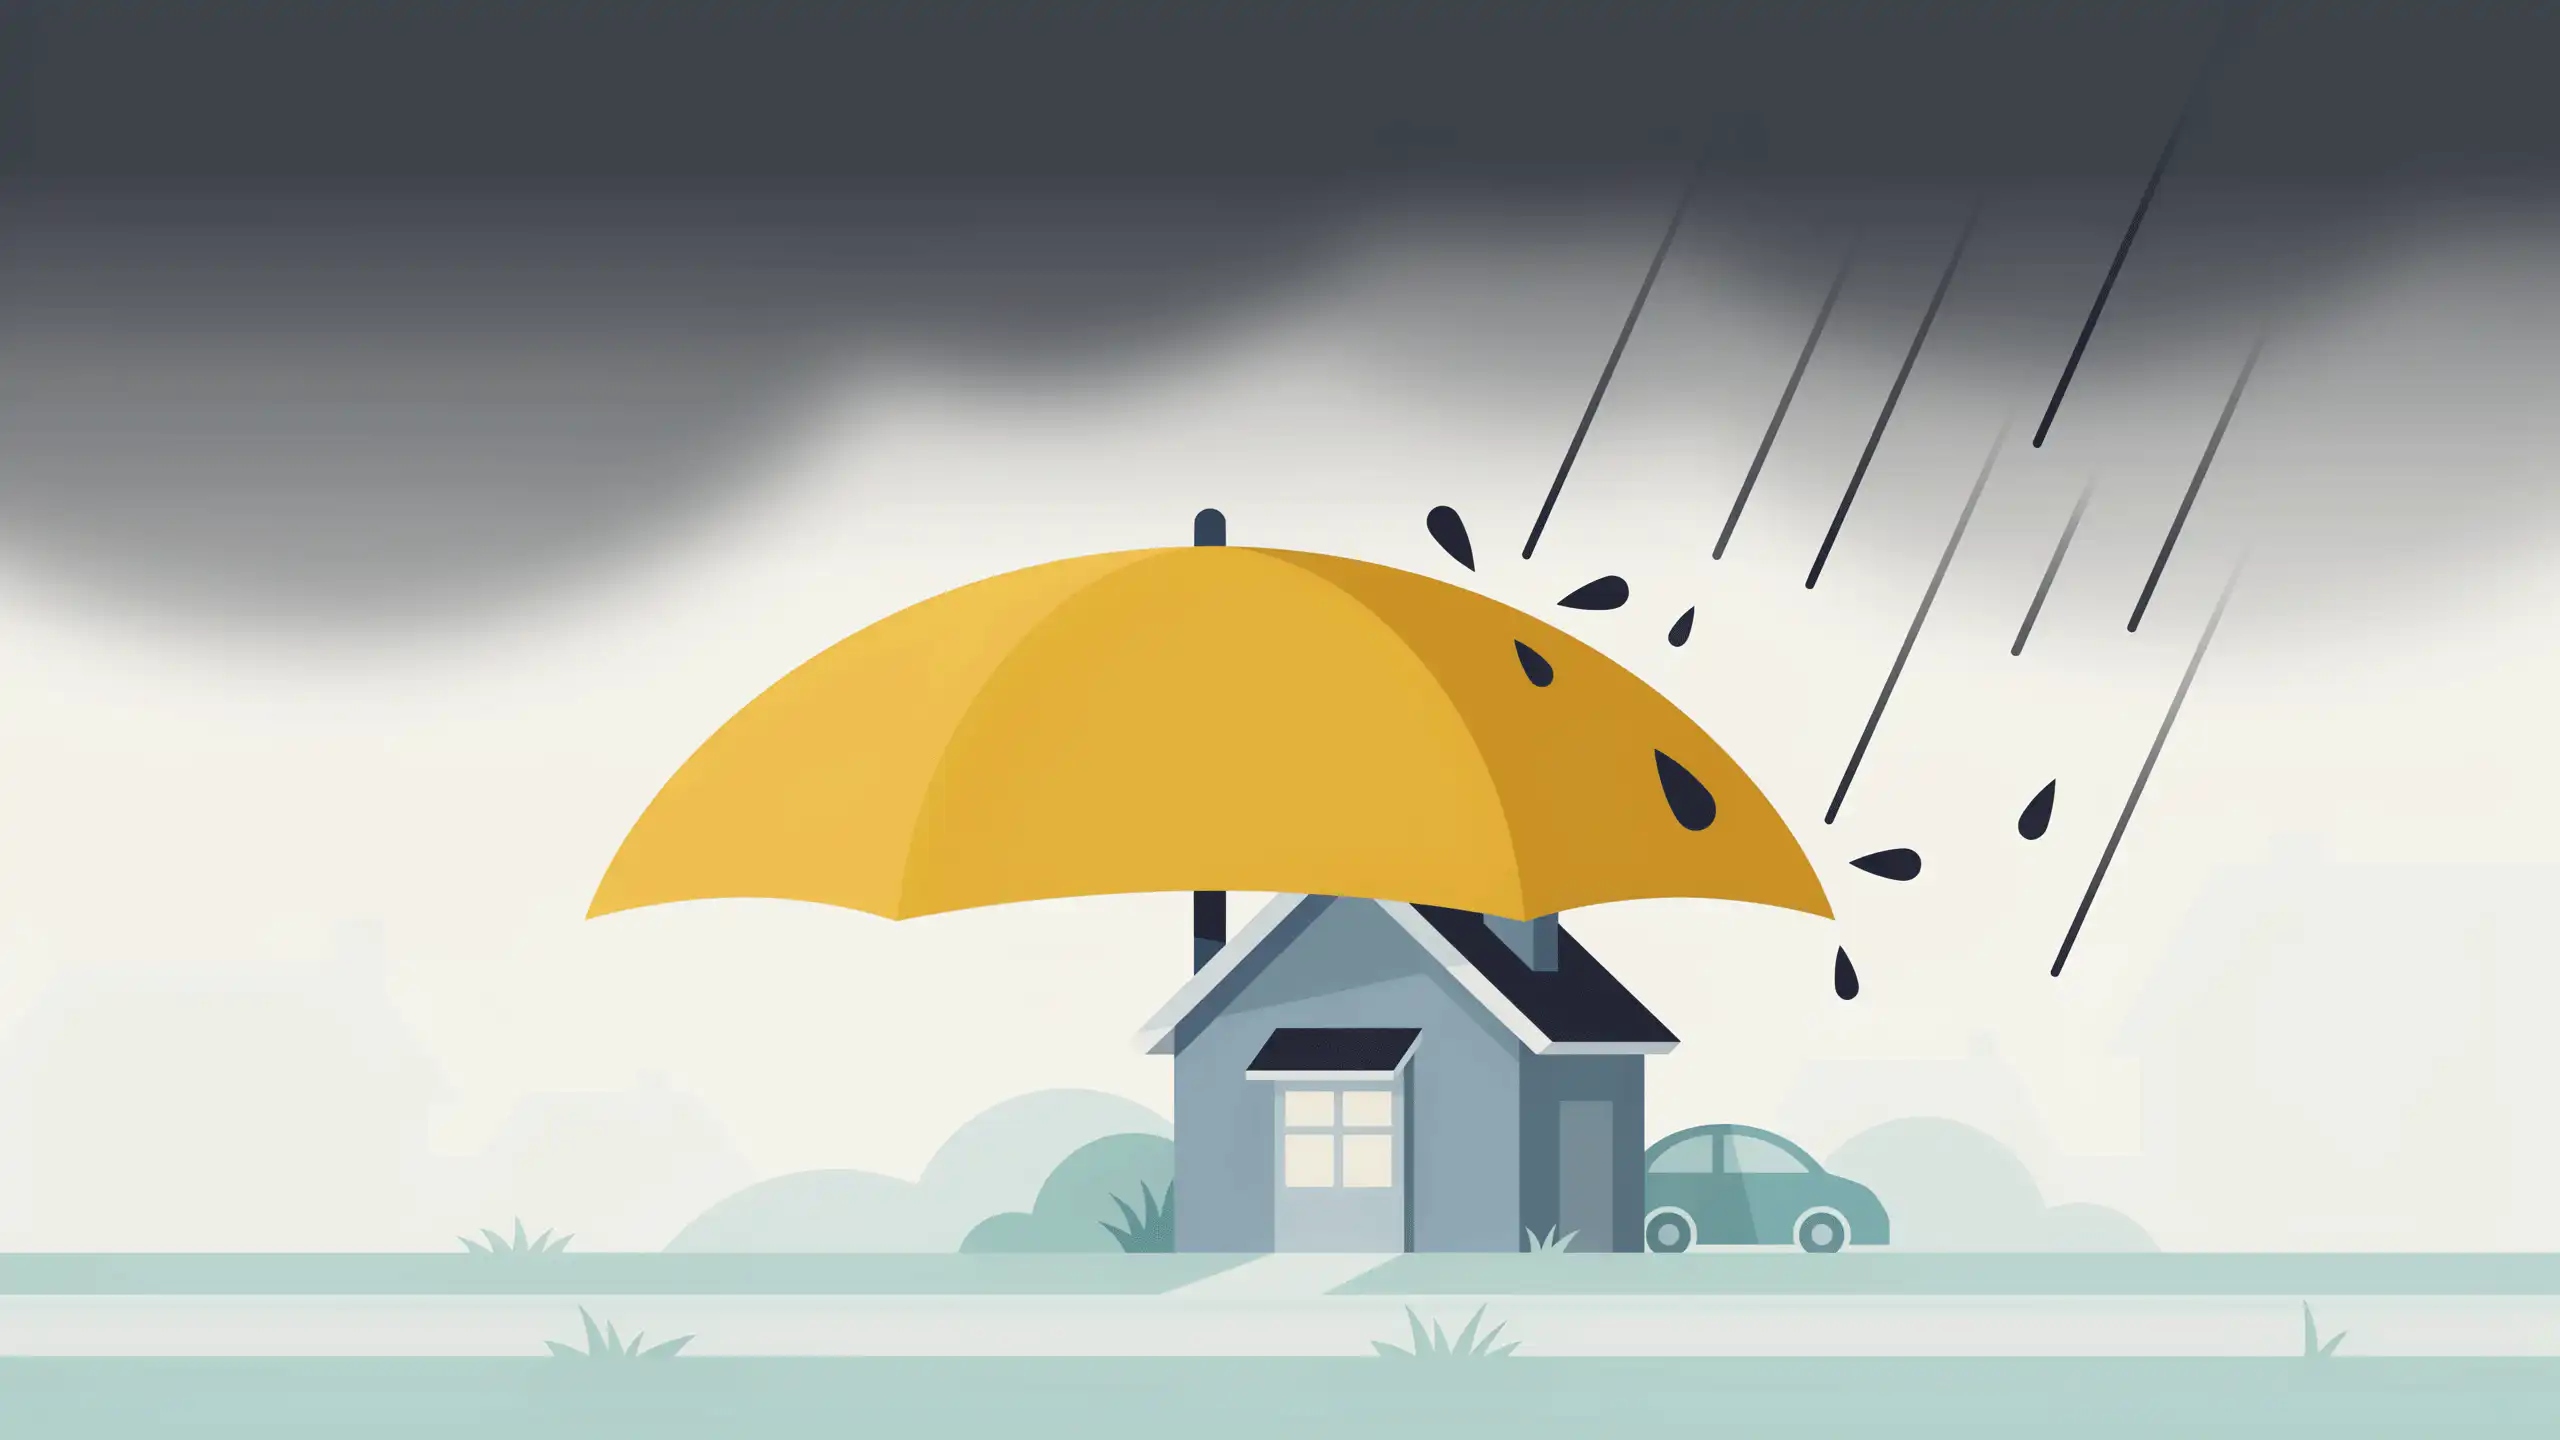
Enter the personal umbrella policy: a high-limit, surprisingly affordable secondary layer of insurance designed to bridge the gap between standard coverage and total financial devastation. Despite its relative affordability and profound utility, millions of Americans remain uninsured or underinsured against catastrophic legal liabilities.
Main Facts: Understanding the Vulnerability Gap
To understand why a personal umbrella policy is necessary, one must first look at the mechanics of standard liability insurance.
Standard auto and homeowners insurance policies include specific liability caps. For instance, a common auto insurance policy might feature limits of $250,000 per person and $500,000 per accident. If you cause a severe accident that results in injuries to multiple parties, your insurance company will pay out claims only up to that established limit.
The Real-World Cost of a Catastrophe
Picture a scenario in which you are at fault for a serious traffic collision that severely injures two individuals. A court subsequently awards each victim $450,000 for medical bills, lost wages, and pain and suffering—totaling $900,000 in damages.
With standard auto limits of $250,000 per person and $500,000 per accident:
- Your insurer pays out the maximum policy limit: $500,000.
- The remaining balance: $400,000.
That remaining $400,000 is your personal responsibility. Without an umbrella policy to absorb the blow, plaintiffs can legally collect this debt by seizing your personal savings, liquidating your retirement accounts (depending on state laws), or legally garnishing up to 25% of your after-tax wages—the federal maximum limit—for years to come.
What an Umbrella Policy Covers
A personal umbrella policy acts as an elevated financial shield. It triggers the moment your primary auto, homeowners, watercraft, or recreational vehicle liability limits are completely exhausted.
Furthermore, umbrella policies frequently extend coverage into areas that standard policies often exclude or handle restrictively. According to the Insurance Information Institute (III), many robust umbrella policies provide protection against claims involving:
- Libel and Slander: Defamation lawsuits stemming from social media posts, public reviews, or verbal statements.
- False Arrest, Detention, or Imprisonment: Legal fallout if you attempt to perform a citizen’s arrest or detain someone mistakenly.
- Malicious Prosecution or Invasion of Privacy: Non-physical torts that can still result in devastating civil judgments.
- Worldwide Coverage: Incidents that occur while you are traveling internationally (though exceptions apply).
Chronology: The Evolution of Personal Risk and Liability
The modern concept of liability insurance has evolved dramatically over the last century, shifting in tandem with societal litigiousness and legal precedents.
Early 20th Century: The Rise of Basic Protection
- 1920s–1950s: As automobiles became ubiquitous across Western households, the risk of road accidents soared. Governments and private markets responded by introducing mandatory or standard liability insurance. At the time, legal judgments were comparatively modest, and standard policy limits easily covered the vast majority of lawsuits.
The Late 20th Century: The Litigious Explosion
- 1970s–1990s: Driven by escalating medical costs, more aggressive legal representation, and changes in tort law, jury awards began to skyrocket. Million-dollar judgments transitioned from statistical anomalies to realistic possibilities. Insurers and brokers recognized that affluent and middle-class families alike were vulnerable to single lawsuits that could wipe out a lifetime of wealth accumulation. The personal umbrella policy was popularized during this era as a high-net-worth safeguard, before eventually becoming accessible to the general public.
The Modern Era: Hyper-Connected and High-Risk
- 2000s–Present: Today, the risk landscape has expanded further. The rise of social media has introduced new vectors for litigation, such as digital defamation and privacy violations. At the same time, medical inflation continues to outpace general inflation, meaning that a severe bodily injury claim routinely clears the $500,000 threshold far more quickly than it did decades ago. Insurance providers now routinely market umbrella policies not just to the wealthy, but to any household with accumulated equity, future earning potential, or everyday lifestyle risk factors.
Supporting Data: The Economics of Umbrella Insurance
When consumers hear the phrase "$1 million in extra coverage," they often assume the cost must be prohibitive. In reality, personal umbrella policies are among the most cost-effective insurance products on the market.
Cost-to-Coverage Breakdown
Because an umbrella policy only pays out after your primary auto or homeowners policy has been completely tapped out, the statistical likelihood of the insurer having to pay a claim is relatively low. This structural design keeps premiums remarkably low.
According to data compiled by major insurers like Progressive:
- The Baseline Cost: An average $1 million personal umbrella policy covering a single primary residence, two cars, and two drivers typically costs around $383 per year.
- Scaling Up: Increasing coverage from $1 million to $2 million—or adding subsequent million-dollar increments—is typically very inexpensive, often costing only about $75 more per year per additional million.
Who Needs It Most?
While anyone with assets to protect should consider an umbrella policy, the Insurance Information Institute explicitly highlights several specific demographic and lifestyle profiles that make prime candidates for immediate coverage:
- Households with Teenage Drivers: Statistically, teen drivers have a higher crash frequency, exponentially increasing the likelihood of a major at-fault accident.
- Dog Owners: Certain breeds or even docile dogs can cause severe bite injuries. Homeowners insurance often limits dog bite liability, making an umbrella policy vital.
- Property Owners and Landlords: Owning rental properties exposes you to tenant injuries, slip-and-falls, and premises liability claims.
- Hosts of Frequent Social Gatherings: If you frequently host parties, maintain a swimming pool, or have trampolines on your property, your risk profile for guest injuries rises significantly.
Official Responses and Industry Guidelines
Insurance regulators, financial planners, and consumer advocacy groups uniformly recommend assessing one’s liability exposure regularly, though prerequisites must be met before purchasing an umbrella policy.
Prerequisites for Purchase
You cannot simply walk into an insurance agency and buy an umbrella policy in isolation. Because umbrella policies sit on top of underlying policies, insurance companies require you to maintain robust foundational coverage.
Typically, insurers will not issue an umbrella policy unless your primary coverage meets specific minimum thresholds:
- Auto Liability Limit: Usually a minimum of $250,000 per person / $500,000 per accident for bodily injury, and $100,000 for property damage.
- Homeowners Liability Limit: Usually a minimum of $300,000.
If your current policies fall short of these thresholds, you will need to adjust and slightly increase your primary limits before an umbrella policy can be bound.
How Much Do You Need?
Financial advisors recommend calculating your net worth—including homes, vehicles, retirement accounts, investments, and savings—and ensuring your total liability coverage at least matches that figure.
However, experts emphasize that future earnings must also be factored into the equation. If you are a high earner early or mid-career, a court-mandated wage garnishment can reach deep into your future paychecks for years. In such cases, purchasing a $2 million or $3 million policy, even if your current net worth is modest, provides essential income protection.
Implications: What You Should Do Next
Ignoring liability gaps is a gamble that can undo decades of diligent saving, homeownership, and career building in a single afternoon. Fortunately, closing the gap requires only a few straightforward steps:
- Pull Your Declarations Pages: Locate the one-page coverage summary (declarations page) for your current auto and homeowners insurance policies.
- Audit Your Limits: Check your current liability numbers. Do they meet the standard $250k/$500k auto and $300k home minimums? If not, contact your agent to adjust them.
- Assess Your Net Worth and Risk Factors: Add up your total assets and evaluate whether you possess risk multipliers like teenage drivers, rental properties, swimming pools, or large dogs.
- Request a Quote: Call your current insurance provider this week and ask for a quote on a $1 million or $2 million personal umbrella policy. For roughly a dollar a day, you can secure complete peace of mind against the unforeseen financial cliffs of modern life.