The modern real estate market is defined by a striking paradox: while certain economic sectors experience unprecedented booms fueled by technological advancements, others face acute distress, rising delinquency rates, and shifting consumer behavior. Navigating this dynamic landscape requires real estate investors to look beyond broad market designations and analyze the underlying drivers of demand, debt structures, and exit risks.
In a recent roundtable discussion, real estate experts James Dainard, Kathy Fettke, and Henry Washington dissected key macroeconomic trends affecting the industry. Their analysis provides critical insights into how localized tech infrastructure projects, commercial debt maturity walls, and changing mortgage rates impact residential and commercial investors alike.
Main Facts: The Current Real Estate Landscape
The macroeconomic environment is marked by distinct pressure points across multiple asset classes:
- AI Infrastructure and Housing Shocks: Massive artificial intelligence data center projects are revitalizing small, rural, or secondary markets across the United States. However, the temporary influx of thousands of construction workers creates artificial spikes in home prices and rents, followed by rapid demand contraction once construction completes.
- Commercial Real Estate Distress: Driven by higher interest rates and a looming "maturity wall," sectors including industrial, hospitality, retail, and self-storage have posted billions in new distress. Multifamily properties have seen a dramatic rise in loan modifications and delinquencies, reflecting the severe strain of resetting interest rates.
- Fix-and-Flip Market Pressures: Elevated mortgage rates are slowing sales velocity for residential flippers. Increased days on market, price reductions below initial After Repair Value (ARV) estimates, and tighter profit margins are forcing investors to reevaluate their short-term operational strategies.
Chronology: The Evolution of Market Cycles and Infrastructure Booms
Understanding current market trends requires examining how economic forces develop and ultimately recede over time.
The Lifecycle of Boomtowns
Historically, resource-driven and infrastructure-heavy booms follow a predictable trajectory. Whether observing the nineteenth-century gold rushes, past oil booms in the Dakotas and Texas, or modern technology-driven expansions, the pattern remains consistent:
- The Announcement and Influx: A massive project—such as a multi-million-square-foot AI data center—is announced in a localized market. Thousands of specialized construction workers, electricians, and engineers flood the area.
- The Housing Crunch and Price Surge: Immediate demand outstrips available supply, causing local home prices, short-term rentals, and long-term lease rates to surge dramatically. Investors and opportunistic buyers rush into the market, often paying inflated prices to capture short-term cash flow.
- Project Completion and Exodus: Once construction finishes, the operational phase requires only a fraction of the workforce—typically a few hundred technicians and management personnel. The thousands of construction workers depart for the next project.
- The Post-Boom Correction: Local housing demand plummets. Investors who purchased properties at the peak of the boom find themselves "holding the bag" with inflated debt bases, declining rents, and diminished property values.
The Commercial and Flip Real Estate Timeline (2020–Present)
- 2020–2022 (The Low-Rate Environment): Low interest rates catalyzed aggressive expansion, particularly in the multifamily and fix-and-flip sectors. Investors secured low-cost debt (frequently around 4%), pushing property valuations to historic highs based on peak income projections.
- 2023–2024 (The Rate Reset): As central banks raised interest rates to combat inflation, commercial loans began maturing and resetting to significantly higher rates (often 7% to 8% or higher). Cash flows compressed across large asset classes.
- Late 2024–Present (The Operational Adjustment): Investors face extended days on market, increased reliance on loan modifications, and tighter profit margins. Successful market participants are shifting focus toward conservative underwriting, deep off-market acquisitions, and proactive communication with lenders.
Supporting Data and Market Metrics
1. The Abilene, Texas AI Housing Phenomenon
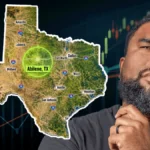
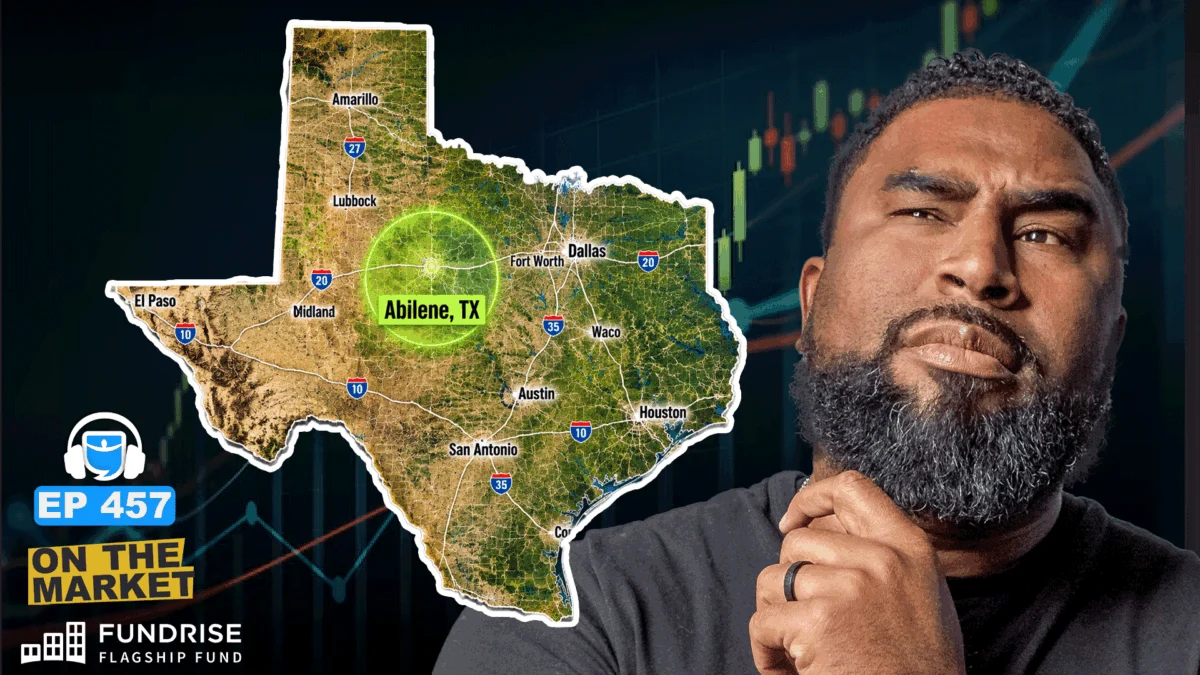
A prime example of infrastructure-driven market volatility is unfolding in Abilene, Texas, home to a population of approximately 100,000. The construction of the Stargate AI facility—a massive four-million-square-foot data center complex—required an immediate workforce of roughly 6,000 construction personnel.
- This represented an approximate 6% population increase overnight.
- Consequently, local home prices rose 9.5% year-over-year, accompanied by steep rent increases.
- Similar patterns were documented in Quincy, Washington, where low utility rates attracted data center construction, providing a temporary two-to-three-year cash flow enhancement for early-moving investors before stabilizing.
2. Commercial Real Estate and Multifamily Distress
According to data from CreditIQ highlighted by industry analysts, distress is spreading beyond traditional office spaces:
- Broad Sector Distress: Industrial, hospitality, retail, and self-storage sectors recently posted $14.6 billion in new distress.
- Office Sector Concentration: Office properties remain heavily impacted. Out of 371 metropolitan areas, just 10 metros account for 57% of the total $87 billion office balance distress, led by major urban centers like New York, New Jersey City, Los Angeles, San Francisco, and Seattle (where office vacancy rates have climbed to 28.2% in the Puget Sound region).
- Multifamily Delinquency Surge: Multifamily delinquency rates have multiplied sixfold (a 600% increase) over the past few years, reflecting severe debt-service coverage pressures as loans transition from fixed low rates to higher variable or renewed commercial rates.
3. Fix-and-Flip Survey Insights
A recent survey of 270 home flippers published by HousingWire outlines current operational strains:
- 59% of flippers reported increased days on market compared to the first quarter.
- Regional impacts are particularly acute, with 83% of flippers in the Northwest and 75% in Texas experiencing longer holding times.
- 17% of surveyed flippers admitted to selling properties below their projected After Repair Value (ARV), though actual market concessions and price drops are widely believed to be higher.
Official Responses and Strategic Guidance from Industry Experts
Faced with tightening credit and shifting asset values, industry leaders James Dainard, Henry Washington, and Kathy Fettke emphasize proactive management and conservative underwriting.
The Importance of Bank Communication
A recurring theme in managing commercial and multifamily distress is direct engagement with lenders.
- Loan Modifications: Data shows that multifamily lenders are increasingly utilizing loan modifications rather than initiating costly foreclosures. Lessons learned from the 2008 financial crisis have taught financial institutions that foreclosing on distressed properties is often less profitable than restructuring terms.
- Practical Relief: Borrowers facing rate resets or cash-flow crunches are urged to communicate early with their banking partners. Instances of lenders granting rate reductions in exchange for minor fees, or extending interest reserves for up to five additional months on stabilizing properties, demonstrate that banks prefer collaborative solutions.
Underwriting Conservatism for Fix-and-Flip Investors
Henry Washington notes that successful flippers are adjusting their operational models to survive prolonged market cycles:
- Multiple Exit Strategies: Properties must be underwritten with more than one exit strategy. If a home fails to sell within the anticipated timeframe, the investor must ensure the asset can transition into a cash-flowing or break-even rental property.
- Buffer Construction: Adding two to three months of holding time to initial projections helps absorb unexpected market slow-downs.
- Deep Discounts: Acquiring assets significantly below market value (such as 50 to 60 cents on the dollar via off-market channels) ensures profitability even if traditional resale values experience a minor correction.
Implications for Real Estate Investors
The current convergence of AI infrastructure booms, commercial debt distress, and fix-and-flip market normalization carries several strategic implications for investors:
1. Evaluate Demand Drivers Carefully
Investors capitalizing on localized economic booms—such as those driven by data centers, manufacturing plants, or energy projects—must distinguish between temporary and permanent demand. Short-term rentals aimed at transient construction labor can yield exceptional cash flow, but underwriting must assume a return to traditional baseline rents and population levels once the project concludes. Markets with diverse employment sectors remain far more resilient against single-employer or single-project exits.
2. Scale Wisely and Avoid FOMO
Fear of missing out (FOMO) often drives investors to enter asset classes at the peak of a cycle. Large-scale projects, whether massive multifamily complexes or high-end luxury flips, carry magnified risks when market corrections occur. A 5% valuation drop on a multi-million-dollar asset represents a substantial capital loss compared to smaller, more manageable residential units or small multifamily holdings (e.g., 10 to 20 units) where active value-add construction can restore equity.
3. Maintain Liquidity and Structured Debt
Cash reserves and structured debt are the primary tools for weathering market downturns. Investors must actively manage their debt obligations, seek interest reserves during refinancing, and utilize down-cycles to acquire assets at more favorable terms. As historical market cycles demonstrate, periods where selling is difficult frequently present the greatest opportunities for strategic, long-term buying.