For vehicle owners across the United States, auto insurance is an inescapable financial reality. Whether mandated by state law or required by a lender for a leased or financed vehicle, coverage acts as a vital financial safety net. Yet, with premiums fluctuating and options spanning dozens of national and regional providers, identifying the right policy can feel like navigating a maze.
Understanding how to balance required minimums, valuable add-ons, and cost-saving opportunities is critical to getting the best value out of your hard-earned money. Below is a deep dive into the state of the auto insurance market, a ranking of the top providers, and a strategic guide to selecting the coverage that fits your lifestyle and budget.
Main Facts: The Current Landscape of Auto Insurance
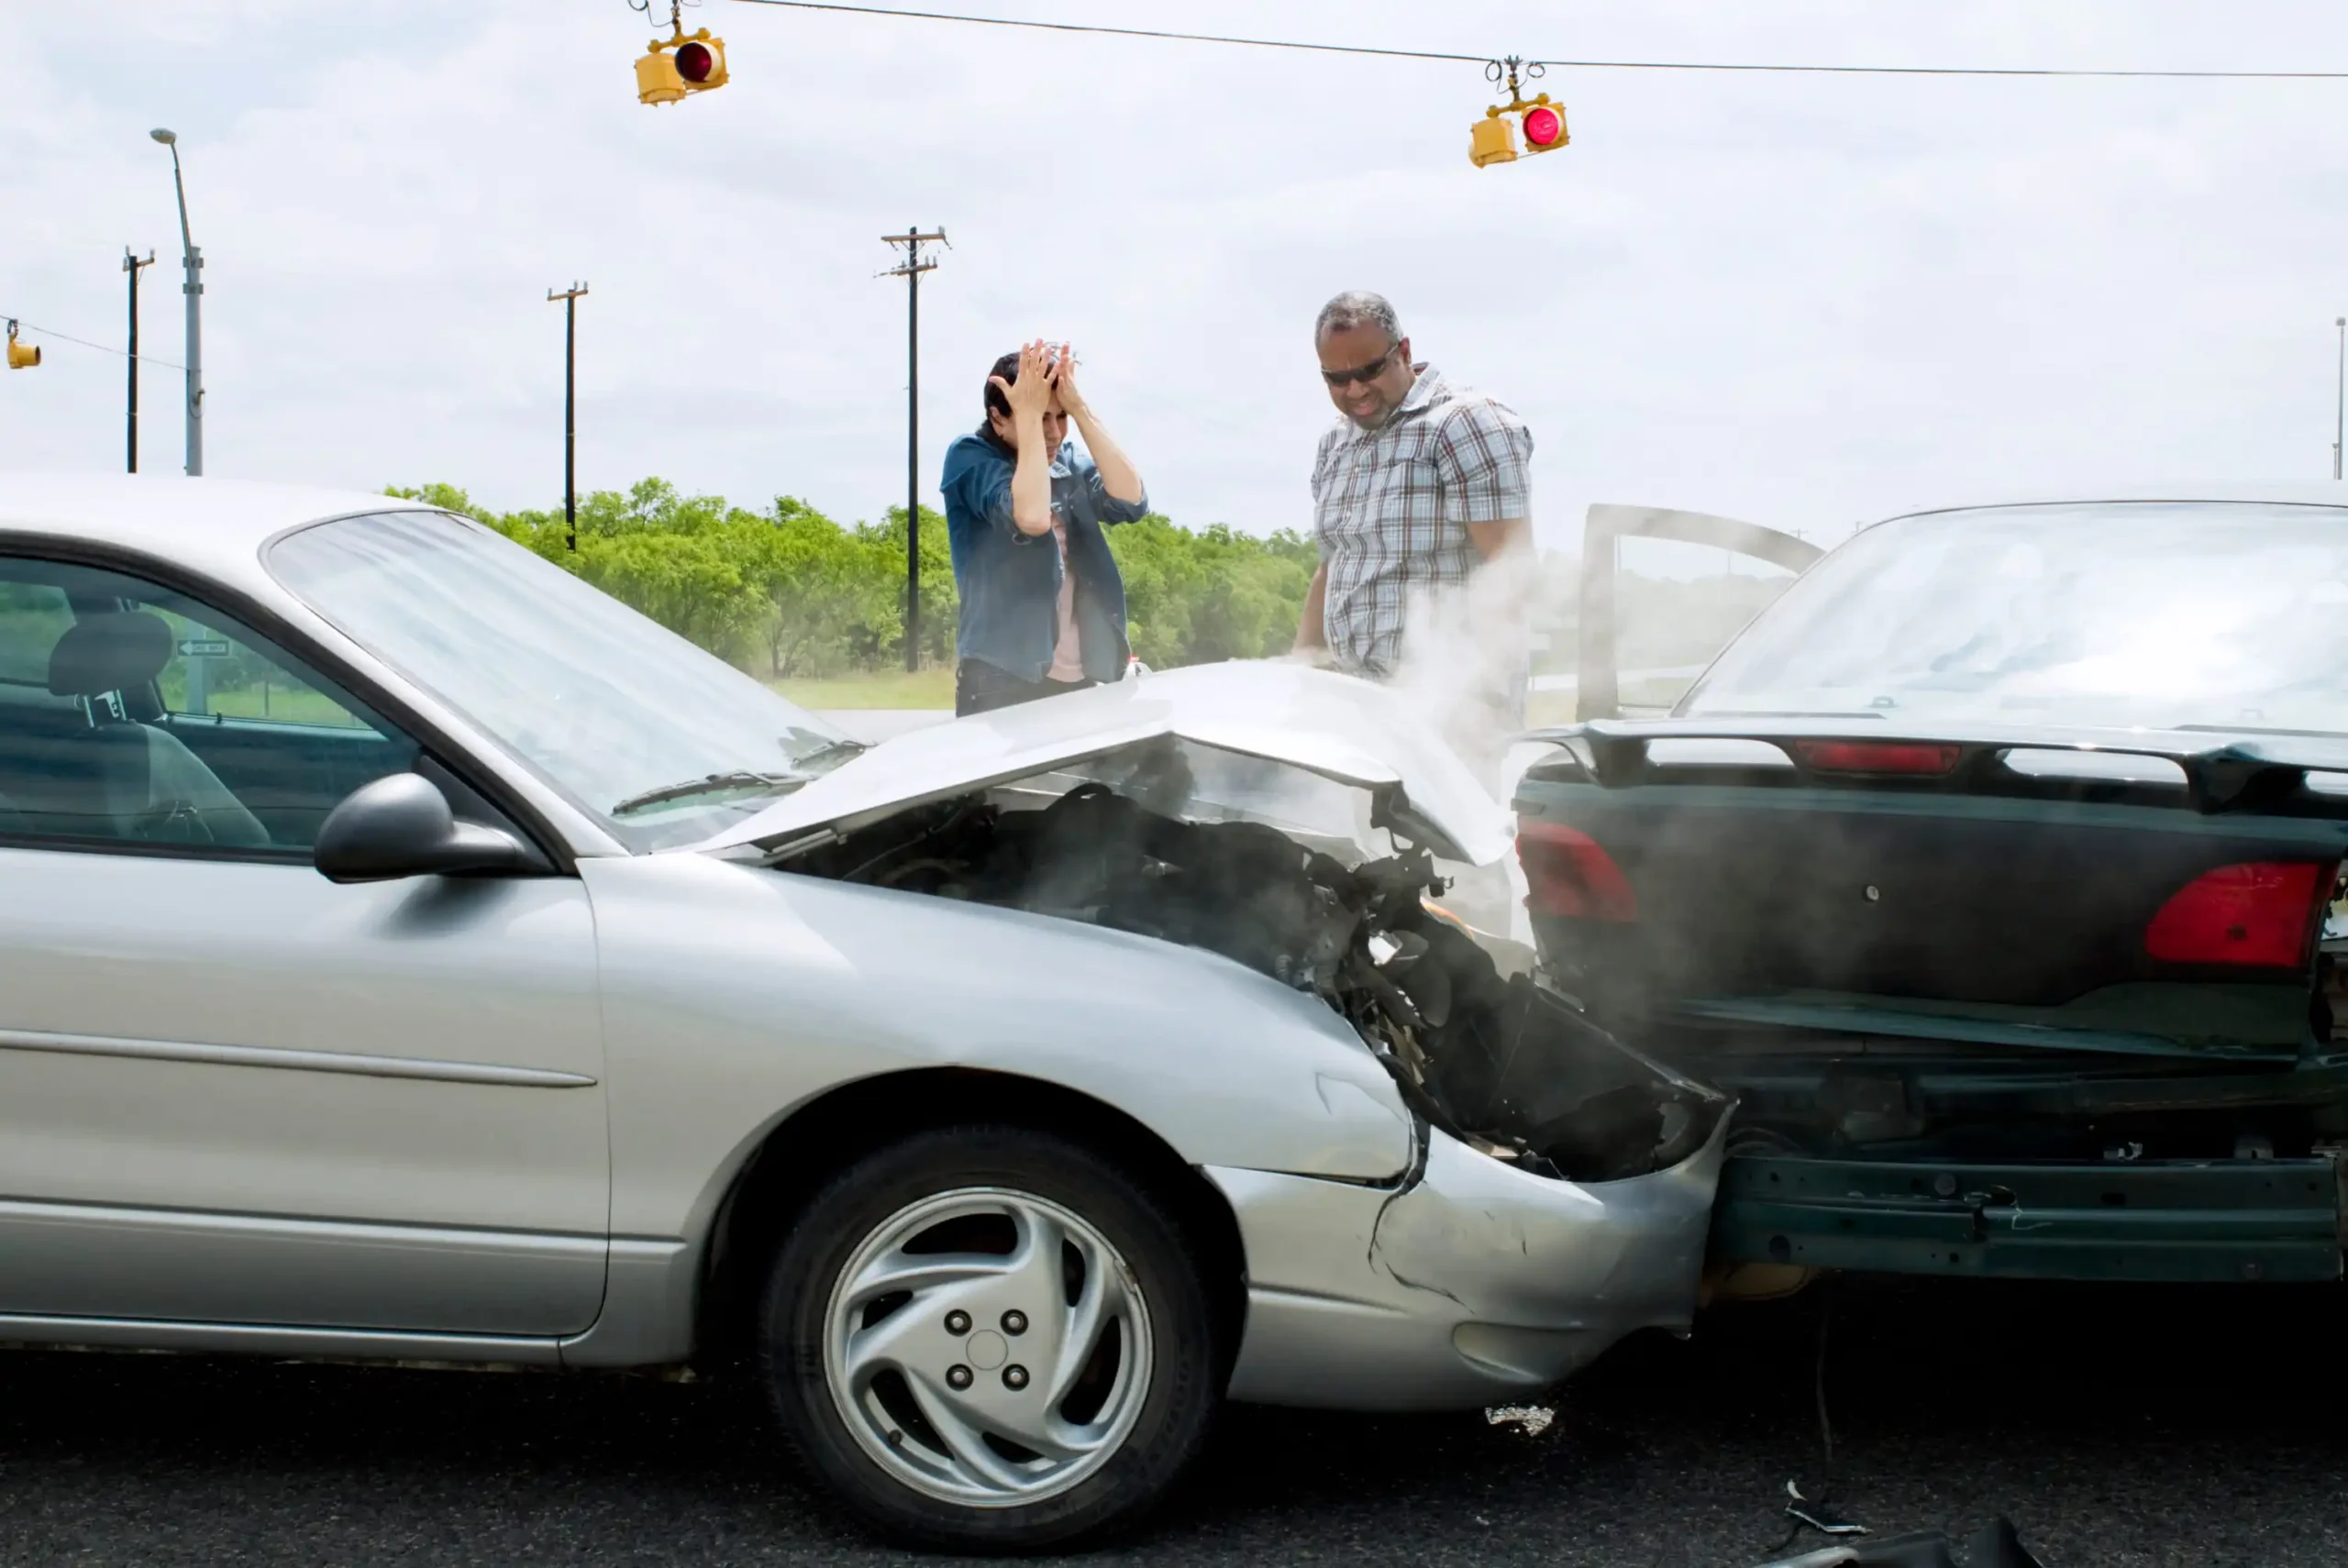
Auto insurance is primarily designed to protect drivers against the financial fallout of vehicle collisions, injuries, and property damage. While all 50 states mandate minimum liability coverage, the baseline requirements vary significantly.
Beyond legal mandates, financial realities dictate coverage levels. Drivers who finance or lease their vehicles must purchase comprehensive and collision coverage to satisfy lender requirements. Consequently, consumers face a dual challenge: complying with legal and financial obligations while keeping monthly or annual premiums manageable.
The market features a wide spectrum of providers, ranging from direct-to-consumer online giants offering streamlined efficiency to traditional insurers anchored by dedicated local agents. Choosing the right insurer requires evaluating how these different operational models align with your need for customer support, technological convenience, and competitive pricing.
Chronology: The Evolution of Modern Auto Insurance Selection
The process of shopping for and managing car insurance has undergone a radical transformation over the past two decades, shifting from manual agency visits to instant digital onboarding:
- The Traditional Era (Pre-2010s): Consumers relied almost exclusively on local independent agents to source quotes, evaluate policies, and process claims. While customer service was deeply personalized, comparing multiple rates was time-consuming.
- The Digital Aggregator Boom (2010s): Online quote comparison tools emerged, allowing drivers to view rates from multiple carriers within minutes. Insurers rushed to build direct-to-consumer websites, prioritizing speed and automation.
- The Telematics Revolution (Present): Today, telematics and mobile apps dominate the market. Insurers increasingly use behavior-based tracking devices and smartphone apps to monitor driving habits, rewarding safe drivers with steep discounts and real-time policy management.
Top Car Insurance Companies on the Market
Every major insurer excels in a specific category—whether it is rewarding loyal customers, offering low premiums, or providing valuable policy add-ons like new car replacement. Based on market evaluations, here are the top-performing car insurance companies:
1. State Farm: Best Overall
State Farm may not dominate any single metric, but it delivers undeniable, consistent value for drivers nationwide. Its extensive network, stable financial backing, and widespread availability make it the top overall pick for everyday car insurance consumers seeking reliability without complications.
2. Root Insurance: Best for Good Drivers
Root Insurance approaches the market through a telematics-first lens, monitoring driving habits directly via its mobile app to reward safe drivers. The average Root customer saves up to $900 a year. Roadside assistance comes standard with every policy, and the streamlined app allows users to onboard in under a minute.
3. Auto-Owners Insurance: Best Customer Service
Though unavailable in certain large states like California and Texas, Auto-Owners delivers legendary customer service through a network of loyal, hardworking local agents. For consumers who prefer a personalized, human-centric approach to securing coverage and handling claims, Auto-Owners remains tough to beat.
4. USAA: Best for Service Members and Their Families
USAA restricts eligibility to active-duty military, honorably discharged veterans, and their immediate families—leaving out about 95% of the general population. However, those who qualify gain access to sign-up and loyalty incentives that, according to internal data, save new customers upwards of $700 in their first year.
5. Nationwide: Best Safe-Driving Discount
Nationwide stands out for competitive pricing, broad policy choices, and a low customer complaint ratio relative to its size. Its SafeRide program is an industry leader in safe-driving incentives, offering an immediate 10% discount for installing a tracking device and up to 40% off for consistent safe-driving practices.
6. Amica: Best General Policy Discounts
Amica offers a remarkably wide array of policy discounts, including up to 30% off for bundling home and auto, and up to 25% off for multi-car households. For drivers confident in their ability to avoid filing claims, Amica also offers unique dividend policies that pay back up to 20% of premiums over time.
7. Allstate: Best for Roadside Assistance
Allstate combines strong brand recognition with robust customer service. It stands out in the marketplace for offering comprehensive roadside assistance programs comparable to dedicated club memberships like AAA. Drivers can access 24/7 towing, jump-starts, and lockout services through annual plans starting as low as $89 or flexible pay-per-use options.
8. Progressive: Best Application Process
Progressive is well-known for its abundant discounts and feature-rich policy add-ons. Its primary differentiator, however, is a frictionless onboarding process. Progressive provides an insightful, digital-first application experience backed by live agent chat support for users who need extra guidance.
9. Geico: Best for Consistently Low Premiums
Geico is a household name known for ironclad financials and aggressively competitive pricing. It is the premier choice for drivers prioritizing low premiums above all else. While it may not offer white-glove, high-touch customer service, its efficient digital infrastructure helps average switchers save up to $500 a year.
Supporting Data: Understanding Coverage Types and Cost Factors
Choosing the right policy requires a firm grasp of the various coverage components available:
- Liability Insurance: Covers damages and injuries you cause to others in an at-fault accident. Most states mandate minimum limits.
- Collision Insurance: Pays for repairs to your own vehicle following a crash with another car or stationary object.
- Comprehensive Insurance: Protects against non-collision incidents, including theft, vandalism, fire, and natural disasters.
- Uninsured/Underinsured Motorist Coverage: Steps in if you are hit by a driver who lacks adequate insurance.
- Gap Insurance: Essential for leased or financed vehicles, this covers the "gap" between what your car is currently worth and the remaining balance on your auto loan if the vehicle is totaled.
Key Factors Affecting Your Rates
Insurers calculate premiums based on risk. The primary factors influencing your costs include:
- Driving record and history of accidents or traffic violations
- Age, gender, and marital status (where permitted by state law)
- Geographic location and local vehicle theft rates
- Vehicle make, model, and safety ratings
- Credit history and credit-based insurance scores
Official Responses and Industry Methodology
Industry evaluators assess auto insurance providers using rigorous, multi-faceted methodologies to ensure consumers receive objective guidance. Key evaluation criteria include:
- Premium Range: Preference is given to direct-to-consumer online insurers offering more competitive baseline rates, though consumers are encouraged to use quote aggregators to compare options rapidly.
- Geographical Availability: Insurers offering nationwide coverage without regional discrimination score higher.
- Discounts and Loyalty Perks: Carriers that offer dynamic ways to save—ranging from safe-driving telematics to multi-policy bundles—rank higher in consumer value.
- Customer Complaints and Repair Scores: Evaluators review formal complaint volumes filed with industry associations and state insurance commissioners, while cross-referencing metrics like Crash Network Collision Repair scores to evaluate post-accident repair satisfaction.
Implications: How to Choose and Maximize Your Savings
Finding high-quality auto insurance at an affordable rate requires discernment and proactive management. To secure the best policy for your household, consider the following actionable steps:
- Evaluate State Requirements vs. Personal Risk: Do not settle for state minimums if your personal asset protection requires higher liability limits. Assess whether you need gap insurance or rental car reimbursement based on your financial situation.
- Shop Around Regularly: Insurance rates shift frequently. Using comparison tools allows you to benchmark your current provider against emerging market rates.
- Maximize Every Discount: Inquire directly about bundling policies, maintaining a clean driving record, paperless billing discounts, and telematics-based safe-driving programs.
By taking a strategic, informed approach to your auto insurance policy, you can protect your financial future, keep your monthly overhead manageable, and secure peace of mind every time you get behind the wheel.