As the real estate landscape enters a prolonged period of sluggishness and shifting momentum, housing analysts are delivering a blunt message to buyers, sellers, and investors: the ongoing housing market correction is far from over, and it is beginning to spread into regions once thought immune.
While sensationalist headlines frequently swing between predictions of an imminent market crash or a sudden price boom, industry experts argue the reality is far more nuanced. According to data and macroeconomic trends highlighted by Dave Meyer, Chief Investment Officer at BiggerPockets, the U.S. housing market is experiencing a slow, calculated correction—one that is elongating, dragging down real home values, and shifting geographic fault lines across the country.
Main Facts
The current state of the U.S. housing market is defined by several conflicting indicators. On the surface, national nominal home prices—the figures listed on contracts and tracking platforms like Zillow—appear mildly positive, hovering up roughly 1.5% year-over-year. However, economists emphasize that these headline figures obscure a deeper reality: real, inflation-adjusted home prices are steadily declining.
- Real vs. Nominal Prices: When adjusted for general inflation (which has outpaced nominal home appreciation), home prices have steadily retreated from their 2022 peaks. In inflation-adjusted terms, home prices currently sit approximately 4.8% below their 2022 highs.
- The Rise of Concessions: Sellers are increasingly abandoning strict list prices to attract scarce buyers. Recent data indicates that roughly 45% of existing homes sold feature seller concessions—such as mortgage rate buydowns or closing cost credits—while nearly 16% of listings feature both price drops and concessions.
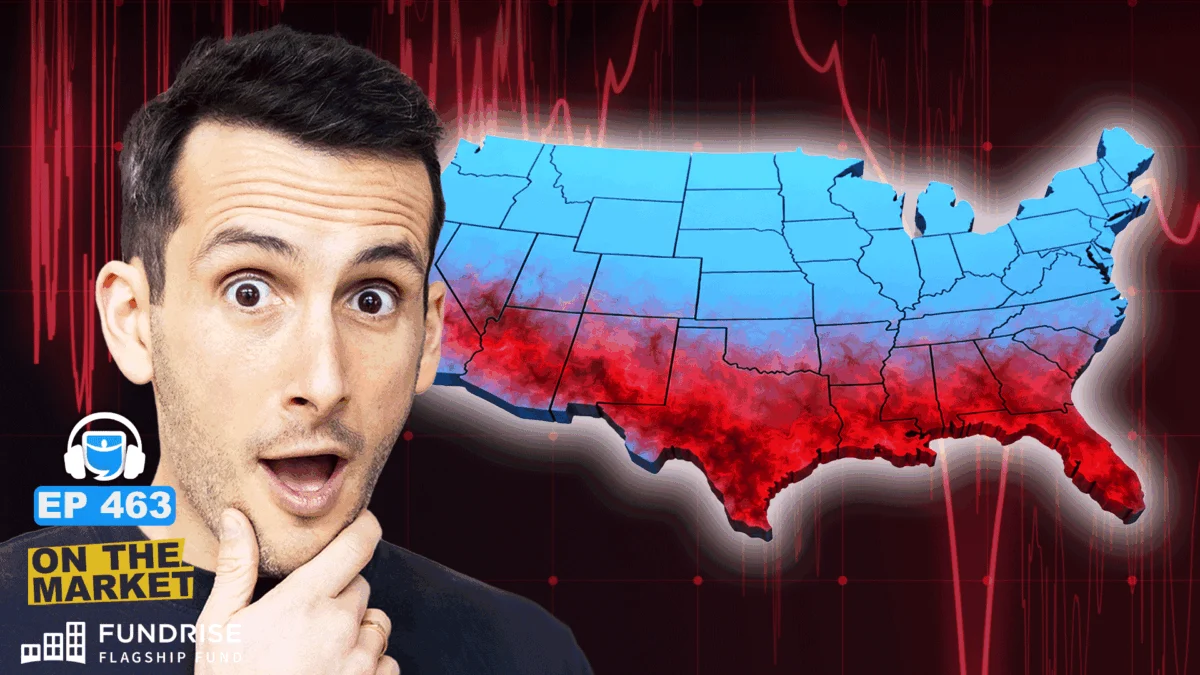
- Shifting Regional Momentum: While markets in the Sunbelt (such as Texas and Florida) have absorbed the brunt of price corrections over the last few years and are beginning to find a floor, traditionally insulated markets in the Midwest and Northeast are now seeing inventories swell and price growth decelerate.
Chronology of the Correction
To understand where the housing market is heading, analysts point to a clear timeline of events shaping the post-pandemic economic landscape:
- 2022 (The Peak): Mortgage rates began a sharp ascent, driven by aggressive Federal Reserve rate hikes to combat surging inflation. Housing demand immediately froze, marking the definitive peak of the pandemic-era housing frenzy.
- 2023–2025 (The Stagnant Plateau): For over three years, the market entered a stalemate. Sellers with locked-in mortgage rates below 4% refused to list their homes—a phenomenon known as the "lock-in effect." Meanwhile, buyers faced severe affordability constraints, leading to historically low transaction volumes.
- Early 2026 (Brief Stabilization Followed by Softening): The first half of 2026 showed minor glimmers of recovery in buyer demand before global economic pressures and sticky interest rates drove mortgage demand back down. Purchase mortgage applications plunged to nearly half of their long-term historical averages.
- Late 2026 and Beyond (The Deepening Correction): Existing inventory has begun to creep upward, surpassing 1.6 million units for the first time since late 2019. With supply ticking up and demand softening, the market is entering a phase where nominal price contractions are becoming increasingly likely on a national scale.
Supporting Data and Economic Indicators
Navigating today’s real estate climate requires looking past marketing buzzwords and examining hard economic fundamentals.
1. The Mortgage Purchase Index and Demand
According to Mortgage Bankers Association (MBA) data, the purchase index—which tracks mortgage applications for home purchases—sits around 230, a sharp drop from 386 a year prior and well below the historical average of 470. Pending home sales have similarly dropped by over 5% year-over-year, pushing existing home sales below the 4-million annual threshold.
2. Rising Inventory and Falling De-Listings
Existing home inventory has climbed roughly 6% year-over-year to 1.62 million units. Furthermore, de-listings—properties pulled off the market by frustrated sellers—have fallen 13% year-over-year. This indicates that sellers who previously held out for peak pandemic prices are finally capitulating, realizing that interest rates are unlikely to drop significantly in the near term.
3. Homebuilder Concessions
New construction data underscores the weakness in buyer demand. Approximately 40% of homebuilders are cutting prices by an average of 6%, while roughly two-thirds of new construction homes feature heavy buyer incentives and rate buydowns. Because builders typically view direct price cuts as a last resort to avoid lowering neighborhood comparable sales, this trend signals persistent downward pressure on valuations.
Official Perspectives and Market Analysis
Industry authorities stress that despite declining affordability and sluggish sales volume, this correction is fundamentally different from the 2008 financial crisis.
During the 2008 crash, home prices plummeted by roughly 19% from peak to trough, driven heavily by loose lending standards, subprime mortgages, and a massive wave of foreclosures. Today, underwriting standards remain exceptionally strict. While mortgage delinquencies have ticked up slightly from historic COVID-era lows, they remain well below 2019 pre-pandemic benchmarks.
Furthermore, historical templates for real estate corrections suggest that long, grinding adjustments can last seven years or longer. Having entered this phase approximately four years ago, analysts argue the market is simply working through a prolonged deflation of asset values via inflation rather than a catastrophic, precipitous crash.
Implications for Investors and Buyers
For real estate investors, retail buyers, and industry professionals, the evolving market landscape demands a total overhaul of purchasing strategies.
1. Ditch Appreciation Speculation
Underwriting a deal based on the assumption that market-wide property values will automatically appreciate over the next 12 to 24 months is viewed by experts as speculative and dangerous. Investors should underwrite deals assuming flat or zero market appreciation, relying instead on equity secured at purchase or active value-add strategies.
2. Exploit Buyer Leverage and Concessions
With nearly half of all transactions featuring concessions, buyers possess significant negotiating power. Experts advise disciplined purchasing:
- Demand rate buydowns or seller credits at closing.
- Target properties trading 5% to 15% below current comparable sales (comps), depending on the local economic health of the metro area.
- Walk away from deals that do not strictly align with predetermined financial parameters, even if the price discrepancy appears minor.
3. Geographic Divergence Requires Precision
Real estate remains hyper-local. While markets in the Sunbelt (such as Austin, Dallas, and parts of Florida) are seeing their price declines moderate as sellers pull back excess inventory, high-performing metros in the Midwest and Northeast (such as Detroit, Philadelphia, and Pittsburgh) are experiencing a delayed cooling-off period. Investors must tailor their acquisition strategies to local supply-and-demand dynamics rather than relying on national macroeconomic generalizations.
Conclusion
The housing market is not crashing, but it is enduring a grinding, persistent correction that is expanding into new regions. For patient, highly disciplined investors willing to hold out for motivated sellers, secure aggressive concessions, and underwrite properties conservatively, this evolving environment presents unique long-term opportunities to acquire undervalued assets.