By Financial Markets Desk
Published: April 2026
Main Facts: The Paradigm Shift in Real Estate Cash Flow
Traditional wealth-building wisdom has long championed a singular, linear path: purchase a significant, tangible asset—such as a single-family home, a portfolio of equities, or the latest heavily hyped cryptocurrency—and wait patiently for its market value to appreciate. While this capital-gains strategy can yield substantial returns over decades, it relies heavily on macroeconomic variables entirely outside an individual’s control. Interest rate fluctuations, localized market slumps, and sudden regulatory shifts can leave investors waiting far longer than anticipated to realize their gains.
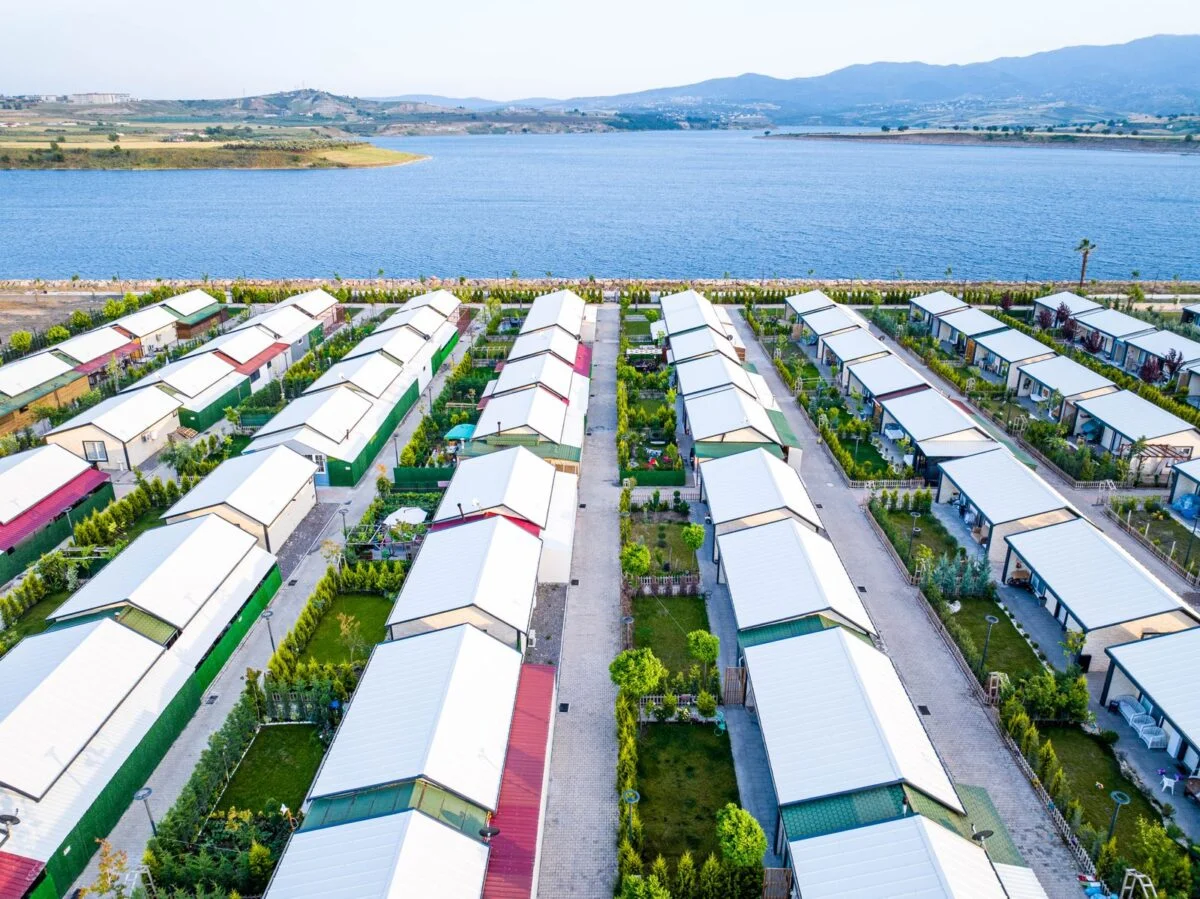
Enter an alternative philosophy rooted in operational cash flow: owning an income-generating asset that delivers predictable monthly revenue regardless of whether the broader market is surging, plunging, or flatlining. Among the most resilient, under-the-radar vehicles for this strategy are manufactured housing communities, more commonly known as mobile home parks.
While largely ignored by novice retail investors chasing high-profile tech stocks, mobile home parks have quietly become a darling of institutional investors, private equity firms, and billionaire financiers like Warren Buffett and the late Sam Zell. Driven by low operating expenditures, unusually high tenant retention rates, a structural housing shortage, and immense potential for operational turnaround, these properties offer a masterclass in modern cash-flow investing.
Chronology: From Stigmatized Suburbia to Institutional Asset Class
To understand how manufactured housing communities evolved into a premier asset class, one must examine their trajectory over the past half-century.
- The 1970s–1980s: The Era of Fragmentation and Mom-and-Pop Ownership
For decades, mobile home parks were largely developed and operated by independent, local "mom-and-pop" owners. These properties were frequently viewed through a culturally stigmatized lens, often associated with transient living and economic distress. Consequently, institutional capital avoided the sector entirely. - The Early 2000s: The Smart Money Moves In
Visionary real estate moguls—most notably Sam Zell through Equity LifeStyle Properties—recognized the fundamental math underlying the model. They realized that owning the underlying real estate while tenants owned their physical dwellings created a unique economic moat. Billionaire Warren Buffett entered the space heavily in 2003 by acquiring Clayton Homes, the nation’s largest manufactured housing builder, signaling a major endorsement of the sector’s structural stability. - The 2010s–2020s: The Affordability Crisis Accelerates Demand
As single-family housing prices outpaced wage growth following the post-2008 recovery, the affordability gap widened dramatically. Manufactured housing communities emerged as one of the last bastions of unshared-wall homeownership for working-class families. Occupancy rates steadily climbed across the United States. - 2025–2026 Outlook: Record Occupancy and Institutional Consolidation
By mid-2025, national occupancy rates in manufactured housing communities hit a staggering 94.9%, according to data compiled in Northmarq’s 2026 market outlook. Average asking lot rents surpassed $752 per month, marking a 7% year-over-year increase. Today, the sector is heavily contested by Real Estate Investment Trusts (REITs) and private syndicators looking to extract value from thousands of remaining fragmented, under-managed parks.
Supporting Data: The Core Pillars of the Mobile Home Park Model
The financial mechanics driving manufactured housing communities rely on five foundational pillars that separate them from conventional multi-family apartment complexes and single-family rental portfolios.
Secret #1: You’re Renting Dirt, Not Houses
In a standard residential rental property, the landlord is legally and financially responsible for every physical component of the structure—from the roof and foundation to the HVAC unit, plumbing, and electrical systems. A single catastrophic maintenance failure, such as a burst pipe or a dead heating system, can instantly wipe out months or even a year of net operating income.
In a manufactured housing community, the business model is inverted. The park owner retains title to the land, internal roadways, and primary utility infrastructure (water and sewer lines). However, the residents own their individual physical homes.
- If a water heater breaks inside a resident’s home, the resident bears the repair cost.
- If a roof begins to leak, the homeowner hires a contractor.
This structural divergence dramatically slashes operating expenses. Industry researcher Ferd Niemann notes that while traditional apartment buildings routinely consume upwards of 50% to 60% of their gross revenue in operating expenses, well-managed mobile home parks typically operate at an expense ratio of just 35% to 40%. That 10-to-20 percent margin difference directly expands free cash flow.
Secret #2: Extreme Tenant "Stickiness"
Tenant turnover is the silent killer of profitability in residential real estate. Every time a tenant vacates an apartment or single-family rental, the owner faces vacancy loss, cleaning fees, repair costs, marketing expenditures, and administrative overhead.
Mobile home parks experience significantly lower friction. Despite the literal nomenclature, mobile homes are rarely mobile. Transporting a manufactured home to a new location requires heavy-hauling permits, specialized transport companies, setup fees, and thousands of dollars in logistics costs. Furthermore, older homes structural integrity often cannot survive a cross-country or even inter-city move.
Consequently, residents tend to stay for years, and frequently decades. As Justin Donald, founder of The Lifestyle Investor, explains: "The stickiness of tenants—moving a mobile home is a logistical and cost-intensive experience—translates into lower turnover rates and consistent cash flow."
Secret #3: Soaring Demand Meets Stagnant Supply
Macroeconomic pressures have severely constrained housing options for middle- and lower-income families. With median starter-home prices sitting at multiples of their historical averages, manufactured housing remains virtually the only remaining avenue for independent homeownership without shared walls at an accessible price point.
Simultaneously, the supply side is frozen. Municipal zoning boards across the United States routinely block the development of new manufactured housing communities through restrictive zoning laws, while local residents frequently lobby aggressively against new park approvals during city council hearings. With demand expanding and supply effectively capped, existing parks enjoy near-perpetual high occupancy.
Secret #4: The Value-Add Playbook
A vast portion of the nation’s mobile home parks remain under the control of aging original owners who purchased properties in the 1980s or 1990s and have not updated their operational practices. These legacy parks often feature:
- Lot rents significantly below current market rates.
- Vacant or underutilized land parcels that could accommodate additional homes.
- Outdated billing structures that fail to pass utility costs back to residents.
For incoming investors willing to invest capital and sweat equity, these operational inefficiencies present prime value-add opportunities. Justin Donald advises: "If you are interested in investing in mobile home parks, it is a good idea to purchase properties that are not yet attractive to institutional investors. An investor can elevate a lower-tier park into an asset that REITs will pay a premium for by increasing occupancy, upgrading infrastructure, and improving the community’s attractiveness."
Because commercial real estate valuations are tied directly to Net Operating Income (NOI)—utilizing capitalization rates—every dollar of added monthly income exponentially increases the overall appraisal value of the property.
Secret #5: Cash Flow as a Risk Mitigator
The overarching philosophy championed by successful cash-flow investors is that operational income must always take precedence over speculative appreciation. When an asset generates robust cash flow from day one, market appreciation transitions from being a desperate financial requirement to an advantageous bonus.
Applying this risk-mitigation filter prevents investors from chasing overvalued assets that depend entirely on favorable market timing.
Official Responses and Industry Perspectives
Real estate economists, market analysts, and institutional leaders emphasize that while the sector is fundamentally sound, sustainable execution requires a balance between aggressive yield optimization and ethical stewardship.
Industry associations and consumer advocates have pointed out the risks of aggressive rent hikes. Because mobile home park residents cannot easily relocate their homes, predatory operators who implement drastic, unannounced lot-rent spikes can push families to financial insolvency. Market leaders stress that long-term asset health depends on fair, predictable, inflation-indexed rent adjustments paired with tangible infrastructure upgrades—such as paved roads, improved lighting, and upgraded utilities—that genuinely benefit the community.
Speaking on the broader investment landscape, financial strategists reiterate that high-interest consumer debt—such as credit card balances carrying 20%+ APR—must be eradicated before allocating capital to real estate syndications or direct property purchases. Eliminating toxic debt functions as an immediate, guaranteed form of high-yield cash flow by permanently reducing monthly liabilities.
Implications: How Everyday Investors Can Participate
You do not need a multi-million-dollar balance sheet or a seven-figure liquidity profile to capture exposure to the manufactured housing sector. Investment vehicles exist across the risk-reward and capital spectrum:
- Publicly Traded REITs: For retail investors seeking maximum liquidity and zero operational responsibility, publicly traded real estate investment trusts like Sun Communities (NYSE: SUI) and Equity LifeStyle Properties (NYSE: ELS) offer immediate access to institutional-grade portfolios through standard brokerage accounts, complete with regular dividend distributions.
- Private Syndications and Funds: Accredited investors can pool capital through private equity syndications managed by experienced operators. These funds typically require minimum commitments ranging from $25,000 to $50,000. Thorough due diligence regarding the operator’s historical track record, resident sentiment, and crisis management history is essential before deploying capital.
- Direct Acquisition: Purchasing a small, rural mobile home park independently is a viable path for hands-on entrepreneurs. Sellers in rural markets frequently offer owner-financing options. However, this route transforms the investor into a full-scale operator, maintenance manager, and property administrator who must be prepared for round-the-clock operational demands.
The Bottom Line
Mobile home parks may lack the glitz and speculative fervor of high-flying technology stocks or cryptocurrencies, but their structural advantages—ultra-low operating expense ratios, extreme tenant retention, systemic housing shortages, and massive value-add potential—make them one of the most reliable wealth-generation engines in modern real estate.
By prioritizing predictable cash flow, protecting downside risk, and insulating a portfolio from the whims of market timing, investors can build enduring wealth that stands resilient against economic turbulence.