Main Facts: The Hidden Vulnerability in Workplace Benefits
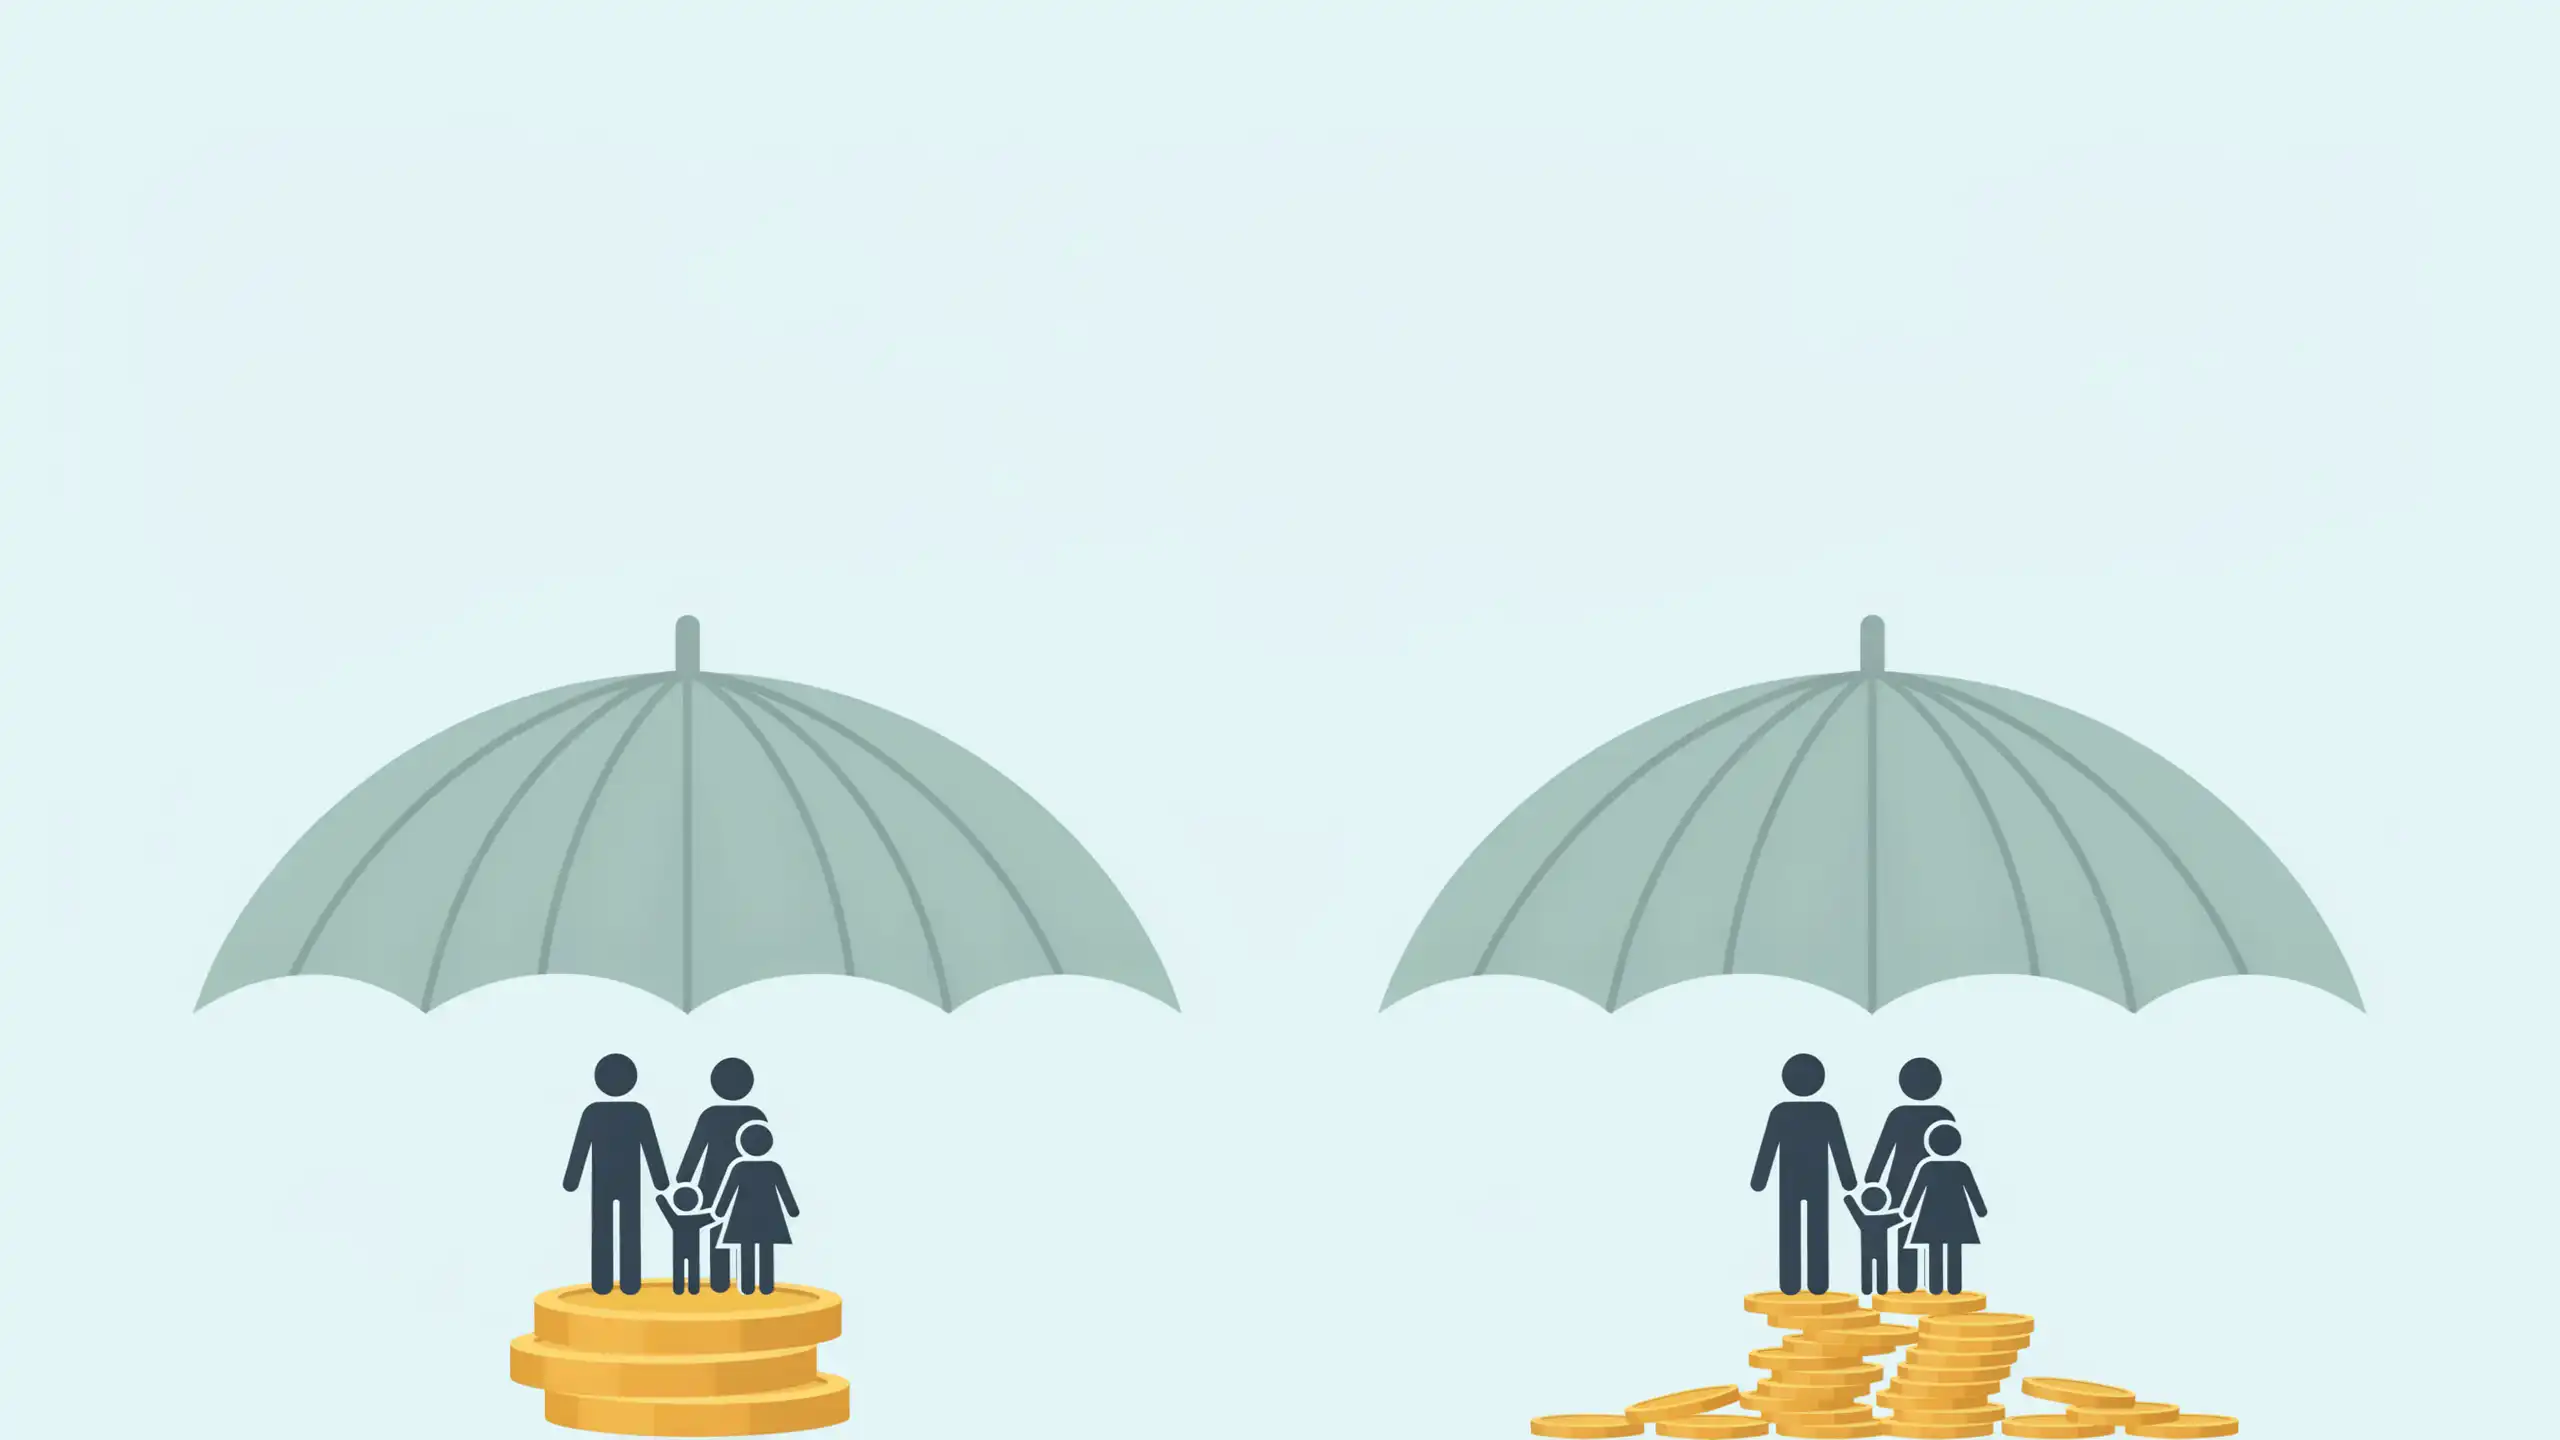
For millions of working professionals, the life insurance policy neatly tucked inside their human resources benefits portal offers a profound sense of security. Automatically enrolled and often fully subsidized by the employer, this complimentary or low-cost perk feels like a foundational box checked in a sound financial plan. However, a closer look at industry standards reveals a sobering truth: standard employer-provided life insurance—typically valued at one to two times an employee’s annual salary—falls drastically short of what a family actually needs in the event of tragedy.
Financial planners and insurance experts overwhelmingly recommend a coverage target equal to 10 to 12 times an individual’s annual income. This broader calculation is not arbitrary; it is designed to entirely replace decades of lost earnings, clear substantial household debts, cover immediate final expenses, and fund future milestone costs like childcare and higher education.
Relying solely on a corporate policy leaves a massive financial gap. Furthermore, employer-sponsored policies carry a fundamental structural risk: they are tied directly to employment. Changing careers, accepting a layoff, or retiring means the coverage vanishes overnight. If an individual’s health has deteriorated in the intervening years, securing an affordable private policy later in life can become shockingly expensive—or outright impossible.
Chronology: The Evolution of Workplace Benefits and the Modern Insurance Gap
To understand how workers arrived at such a dangerous reliance on employer-provided benefits, it helps to examine the historical trajectory of corporate compensation and risk management.
Mid-20th Century: The Rise of Paternalistic Corporate Benefits
- The Post-WWII Era: Following the Second World War, wage freezes imposed by the federal government forced American companies to compete for top talent by offering non-wage compensation. Health insurance and group life insurance rapidly emerged as standard corporate offerings.
- The "Job for Life" Mentality: During this era, workers frequently remained at a single company for decades. Group life insurance functioned effectively because employees rarely transitioned between employers, keeping their coverage stable from their twenties until retirement.
Late 20th Century: The Shift Toward Individual Responsibility
- The Decline of Traditional Pensions: The corporate landscape shifted dramatically in the 1980s and 1990s as defined-benefit pensions gave way to 401(k) plans. The onus of retirement planning shifted from the employer to the employee.
- The Rise of Portable Careers: Job hopping became the norm rather than the exception. Despite this massive shift in how people worked, group life insurance structures largely remained stagnant, continuing to tie vital risk protection directly to ongoing employment.
The Present Day: The Modern Under-Insurance Crisis
- Stagnant Coverage Multipliers: While the cost of living, housing, and higher education have skyrocketed over the past few decades, standard employer-provided life insurance has remained stubbornly anchored at the conservative "one to two times salary" benchmark.
- The Gig and Mobile Economy: Today’s workforce changes jobs more frequently than ever, increasing the frequency with which workers unknowingly forfeit their life insurance safety nets during career transitions.
Supporting Data: Crunching the Numbers on Family Protection
The math behind standard employer life insurance often comes as a harsh shock to grieving families. To visualize the discrepancy, consider a standard professional earning a median salary of $70,000 per year, utilizing a corporate policy that pays out twice their salary.
A Case Study in Under-Insurance
- The Annual Salary: $70,000
- The Employer Policy Payout (2x): $140,000
- Immediate Liabilities:
- Funeral and final medical expenses: -$15,000
- Credit card and consumer debt elimination: -$20,000
- Short-term living expenses and emergency bills: -$25,000
- Remaining Balance for Long-Term Support: $80,000
With only $80,000 remaining to support a surviving spouse and young children, the funds evaporate rapidly. The money may not even fully cover a single year of a standard household mortgage, let alone bridge a decade or more of lost income, pay for future childcare, or fund college tuitions.
The 10-to-12x Rule: Breaking Down the Target
Financial advisors arrive at the 10-to-12x income multiplier by evaluating the present value of a worker’s future earnings.
- Income Replacement: Replacing a $70,000 income over a 15-year period requires a baseline of $1,050,000 before factoring in inflation or wage growth.
- Debt Mitigation: Mortgages, auto loans, and student debt must be paid off immediately to lower the surviving household’s monthly overhead.
- Dependent Milestones: Childcare costs for infants and toddlers can easily run tens of thousands of dollars annually, compounding the need for a robust policy payout.
The Cost-Efficiency of Private Term Life Insurance
Many workers avoid purchasing private policies because they assume premiums are prohibitively expensive. In reality, term life insurance—which provides pure protection for a specified duration (such as 20 or 30 years)—is remarkably affordable for healthy individuals.
- The Benchmark: A healthy 30-year-old can frequently lock in a $500,000, 20-year level term policy for approximately $25 to $30 per month.
- Price Stability: Crucially, a level term policy guarantees that the monthly premium remains fixed for the entire duration of the contract, protecting the policyholder from age-based price spikes.
Official Responses and Industry Perspectives: What Financial Experts Say
Financial planners, consumer advocates, and insurance underwriters are nearly unanimous in their warnings regarding corporate-only insurance strategies.
The Financial Advisory Perspective
Certified Financial Planners (CFPs) frequently encounter clients who mistakenly believe their insurance needs are fully addressed by their employee benefits package.
"HR benefits departments provide a wonderful baseline, but they are designed to be a perk of employment, not a comprehensive estate plan," notes Sarah Jenkins, a fee-only financial planner based in Chicago. "When we walk clients through a holistic cash-flow analysis following the loss of a primary earner, the 1x or 2x employer multiplier routinely falls apart within the first twenty-four months."
The Insurance Underwriting Perspective
Risk analysts emphasize the dangers of waiting until later in life to secure private coverage. Because health conditions can develop rapidly—ranging from high blood pressure and cholesterol issues to more severe diagnoses—relying on work-provided insurance during your prime working years can leave you uninsurable later.
"The absolute best time to buy a private term life insurance policy is when you are young and healthy," explains insurance broker Marcus Vance. "Locking in a rate in your twenties or thirties protects you against the inevitable health changes that come with aging. If you lose your job at age 50 and your health has declined, buying a new policy can become financially crippling or completely impossible."
Implications: Building a Resilient, Independent Safety Net
The realization that workplace life insurance is insufficient demands a strategic shift in how individuals approach their personal risk management. Treating corporate benefits as a primary defense mechanism leaves families vulnerable to the unpredictable nature of modern career paths and health trajectories.
Step 1: Calculate Your True Coverage Gap
Begin by multiplying your current annual income by 10 to 12. From there, customize the figure based on your unique household liabilities:
- Add coverage if you carry a massive mortgage, have children with special needs, or are planning to fund higher education.
- Subtract coverage if your spouse earns a robust, independent income, or if your children are already financially independent adults.
- Deduct the amount provided by your employer’s baseline policy.
Step 2: Secure an Independent Term Policy
The remaining figure represents the target size for a private term life insurance policy. Look for a level-term policy—either 20 or 30 years, depending on how many years remain until your children are grown or your mortgage is paid off. By owning the policy independently, you ensure that your coverage travels with you wherever your career leads, regardless of whether you change jobs, start a business, or retire.
Step 3: Relegate Workplace Coverage to a Bonus
Do not cancel or opt out of your employer’s free life insurance policy; accept it as a welcome financial bonus that sits on top of your primary plan. However, maintain the mindset that your family’s ultimate financial security rests entirely in your own hands. By bridging the gap proactively, you transform a fragile corporate perk into an unbreakable shield for the people who matter most.