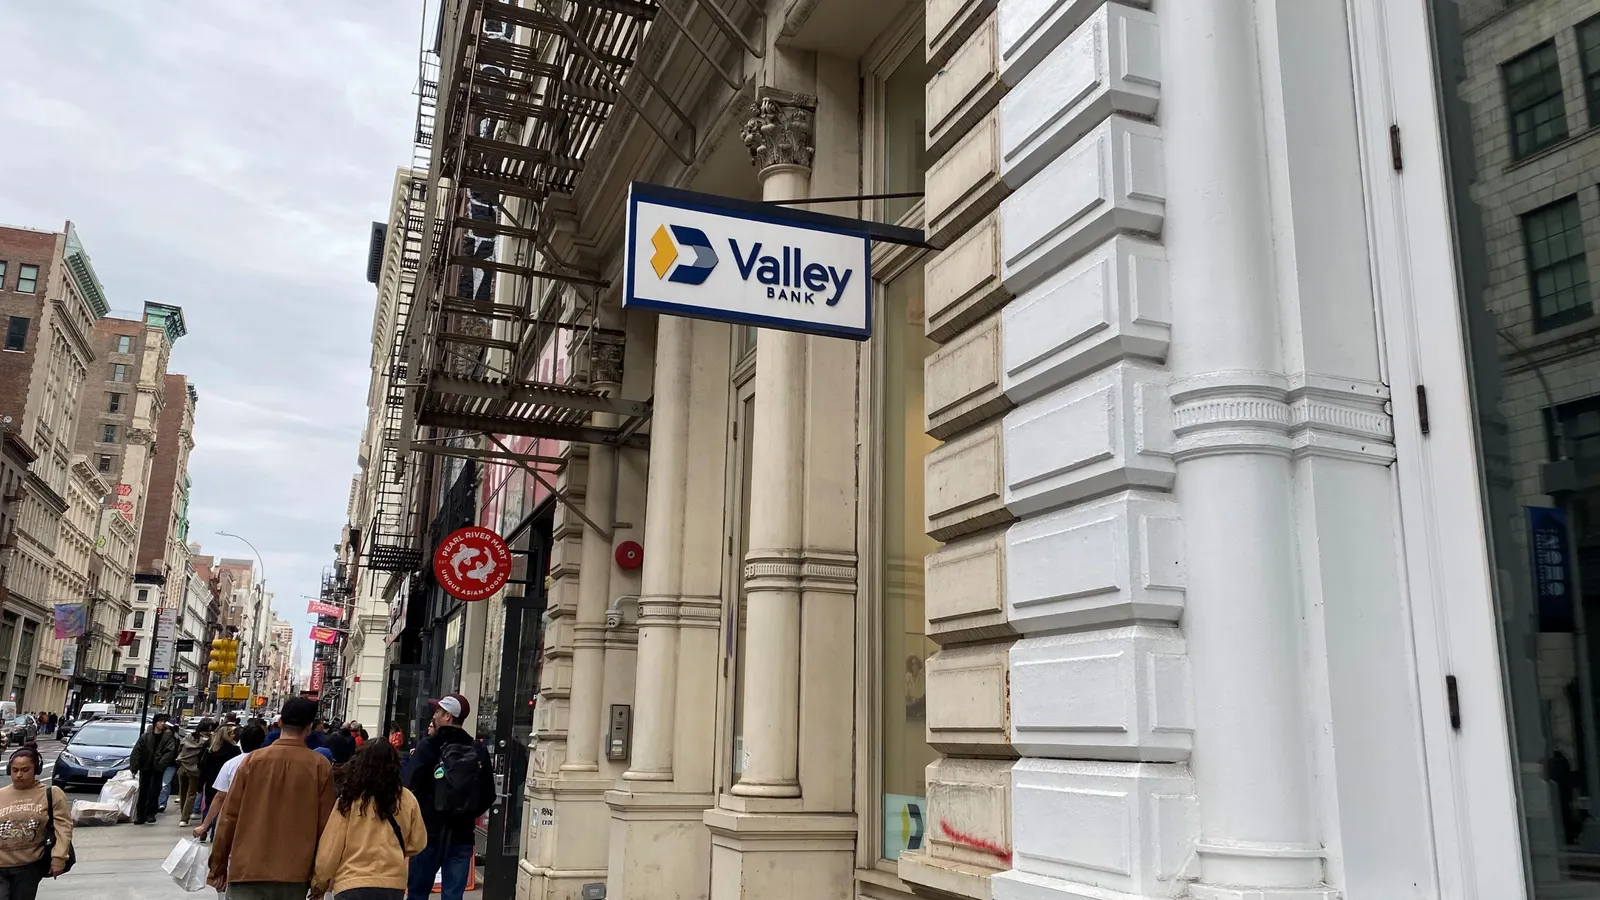
In a move that signals a seismic shift in the traditional banking landscape, $66 billion-asset Valley National Bank (Valley) has announced the acquisition of fintech powerhouse Bluevine. This strategic marriage of a legacy, relationship-focused lender and a high-growth, AI-driven financial platform marks a defining moment in the evolution of small-business banking. By absorbing Bluevine—a provider of digital banking, payments, and lending solutions—Valley aims to vault itself into a leadership position within the competitive national small-business market.
For Valley, the acquisition is more than just a purchase of assets; it is a calculated effort to modernize its funding profile, acquire top-tier technological talent, and secure a sustainable path for long-term customer acquisition.
Main Facts: The Anatomy of the Deal
The agreement to acquire Bluevine is structured as a 75% cash and 25% stock transaction. Valley leadership expects the deal to be approximately 8% accretive to earnings per share, with an estimated 5% tangible book value dilution at closing. While the financial integration will take time, with Bluevine’s deposits transitioning from partner Coastal Community Bank to Valley’s books by the first half of 2027, the impact on Valley’s operational strategy is immediate.
Under the terms of the deal, Bluevine’s co-founder and CEO, Eyal Lifshitz, will join Valley to serve as the head of its newly expanded small-business banking division. The integration brings approximately 180 research-and-development employees and engineers into the Valley fold, providing the bank with an in-house software development engine that significantly reduces its reliance on third-party vendors.
Chronology: A Season of Aggressive Expansion
Valley’s acquisition of Bluevine comes on the heels of a rapid-fire period of corporate consolidation.
- September 2026: Valley signals its intent to grow its footprint through traditional channels by announcing the $247 million acquisition of South Holland, Illinois-based Providence Financial Corp.
- Late September/Early October 2026: Following the Providence announcement, Valley moves to secure its digital future by finalizing the agreement with Bluevine.
- The Future (2027): The transition of Bluevine’s deposits from its partner bank, Coastal Community Bank, to Valley’s balance sheet is slated for completion in the first half of 2027.
Despite the back-to-back announcements, bank executives have been quick to temper expectations regarding further M&A activity. CEO Ira Robbins stated clearly during an investor conference call that these two acquisitions address the bank’s near-term strategic priorities, and the company does not anticipate pursuing additional acquisitions for the foreseeable future.
Supporting Data: Why the Economics Make Sense
The rationale for the acquisition is rooted in hard numbers. Currently, Valley faces the challenge of a high-cost funding environment. The integration of Bluevine serves as a critical lever to optimize this mix.
The Funding Advantage
According to investor presentations, Bluevine’s cost of deposits sits at an attractive 1.44%, a significant improvement over Valley’s current 2.28% cost of deposits. By transitioning these deposits onto Valley’s balance sheet, the bank expects to reduce its reliance on higher-cost wholesale funding, directly improving its net interest margin over time.
Digital Velocity
Bluevine brings to the table a highly optimized digital acquisition platform, backed by nearly $200 million in prior investment. The platform allows for account opening in approximately five minutes—a stark contrast to the often-cumbersome processes found in traditional retail banking.
AI-Driven Efficiency
Efficiency is the hallmark of the Bluevine ecosystem. Executives noted that the majority of the fintech’s code is AI-generated, and roughly 80% of all inbound client inquiries are resolved through AI-driven automation. This infrastructure provides Valley with an immediate upgrade to its customer service capabilities without a commensurate increase in headcount costs.
Official Responses: A "Cultural Fit" and Strategic Vision
The leadership at both firms expressed high levels of confidence regarding the merger, emphasizing that the deal is as much about cultural alignment as it is about technological synergy.
Ira Robbins, CEO of Valley, framed the acquisition as a proactive defensive and offensive maneuver: "Rather than waiting for chartered fintechs to compete with us for small business banking relationships, we are proactively combining Valley’s banking foundation with Bluevine’s digital growth engine."
He further emphasized the "relevancy" factor: "Bluevine adds valuable technology and AI capabilities, and significantly accelerates our path to relevancy in small business banking."
Eyal Lifshitz, co-founder of Bluevine, echoed this sentiment, suggesting that the partnership was the logical next step for the fintech’s growth. "It felt like, for us, the best option to accelerate our vision of building our small business franchise, and ultimately is a combination of complementary capabilities here, but also a strong cultural fit," Lifshitz noted during the conference call.
Implications: The Future of Small Business Banking
The acquisition of Bluevine by Valley provides a blueprint for how mid-tier banks can survive and thrive in an era of fintech disruption.
1. The Death of the "Wait and See" Approach
For years, regional banks watched from the sidelines as fintechs captured the small-business market with superior user experiences and faster lending decisions. Valley’s move marks a departure from that passivity. By buying the digital engine rather than attempting to build it from scratch—a process that is often fraught with failure—Valley has effectively compressed a decade of digital transformation into a single transaction.
2. Solving the Funding Challenge
The banking sector is currently grappling with a core funding challenge. As liquidity becomes more expensive and customer loyalty becomes more fragile, banks need reliable, low-cost deposit bases. By acquiring Bluevine’s customer base, Valley isn’t just buying technology; it’s buying a low-cost, stable deposit stream that provides the capital necessary to fuel future lending growth.
3. The Power of Cross-Selling
With 40% of Bluevine’s existing customer base already located within Valley’s physical geographic footprint, the opportunity for immediate cross-selling is immense. Valley intends to leverage its traditional banking suite—including treasury management, complex lending, and wealth management services—to deepen relationships with these digital-native small businesses. This creates a "hybrid" model where the client enjoys the ease of a fintech interface with the robustness and security of a traditional bank.
4. Market Analyst Perspective
Industry analysts have largely reacted with measured optimism. J.P. Morgan Securities analyst Anthony Elian observed that while the deals happened in quick succession, neither is likely to disrupt Valley’s organic growth profile. The relatively small size of the acquisitions suggests that Valley is being tactical rather than reckless, focusing on high-impact areas that solve specific balance-sheet issues.
Conclusion: A New Standard for Mid-Tier Banks
The acquisition of Bluevine by Valley serves as a watershed moment for the financial services industry. As the competitive landscape evolves, the line between "traditional bank" and "fintech" continues to blur. Banks that successfully integrate digital-first capabilities while maintaining the regulatory stability and relationship-focused service of a chartered institution are poised to dominate the next decade of small-business lending.
For Valley, the challenge now lies in integration. Merging a legacy banking culture with a fast-paced, AI-first fintech team is rarely simple. However, if Robbins and Lifshitz can successfully execute this transition, Valley will have successfully bypassed the most difficult hurdle in modern banking: becoming a technology company without losing its identity as a trusted financial partner. As they move toward the 2027 deposit migration, the rest of the regional banking sector will be watching closely, likely weighing whether to pursue similar acquisitions of their own.