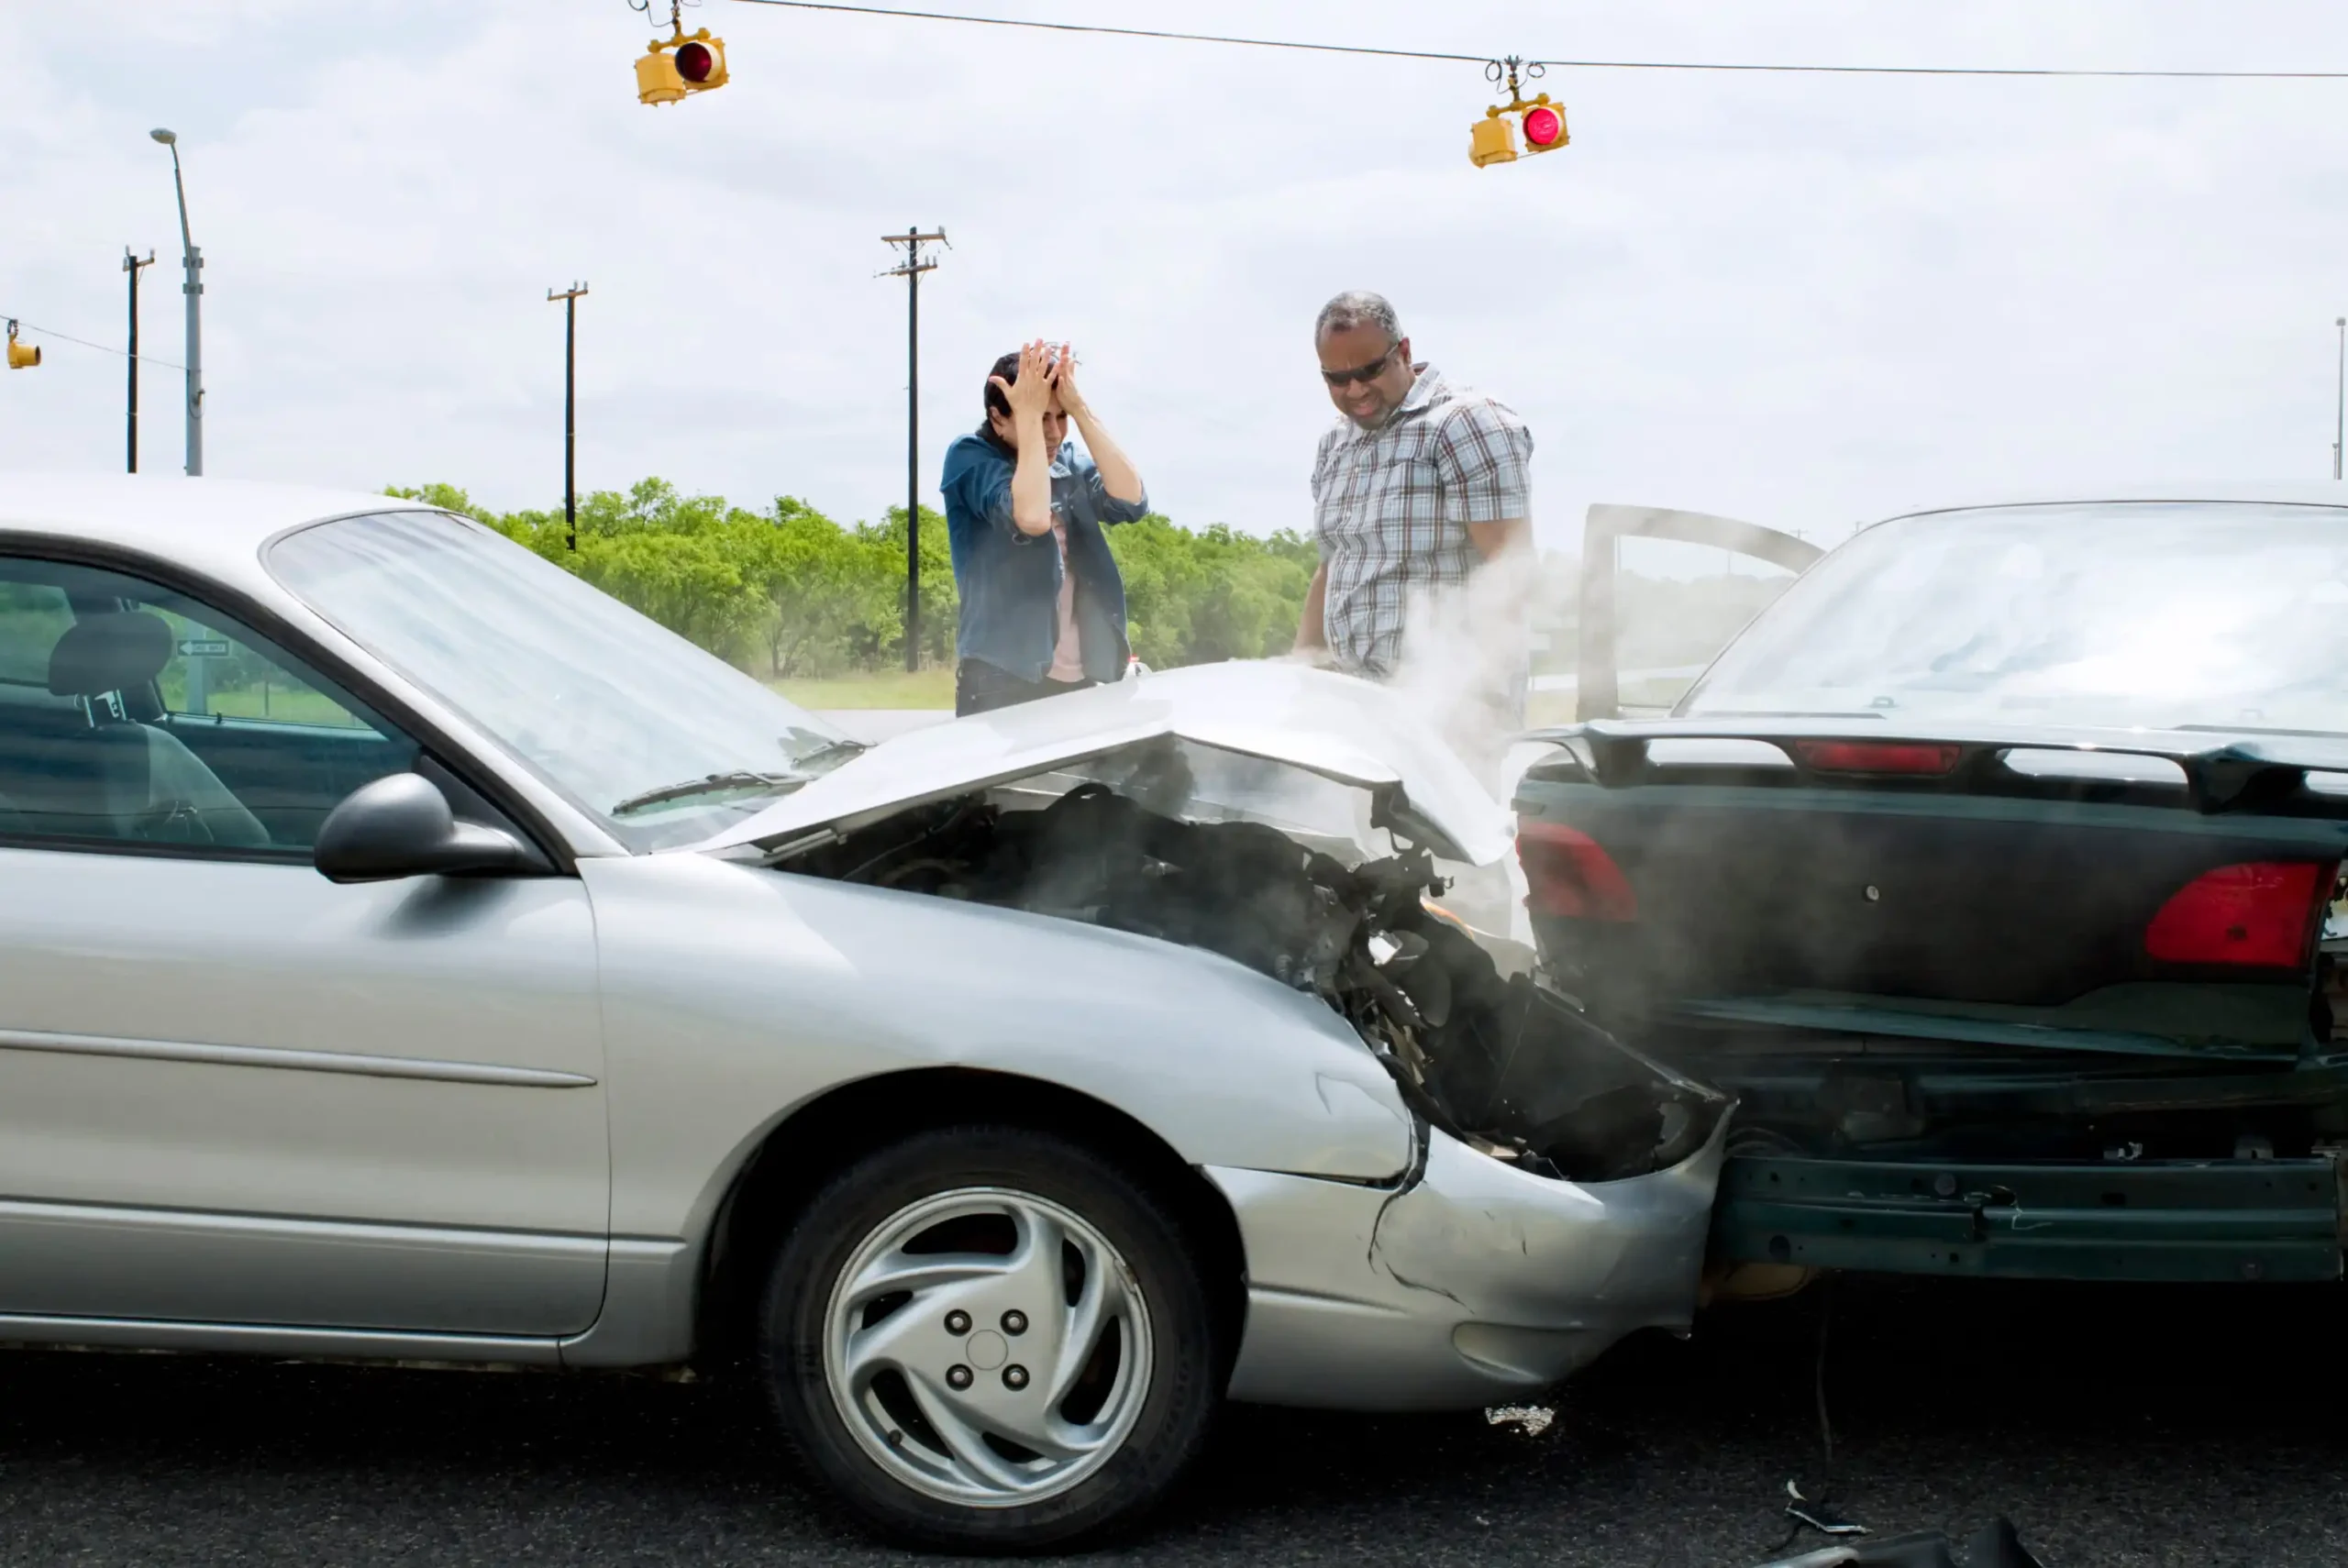
Whether you are sliding behind the wheel of a brand-new vehicle or maintaining a trusted commuter car, auto insurance remains a non-negotiable aspect of vehicle ownership. All 50 states mandate that drivers carry a baseline of car insurance—primarily to cover bodily injury and property damage resulting from vehicle collisions. Furthermore, if you finance or lease your vehicle, lenders will invariably require comprehensive and collision policies to protect their financial stake in the asset.
However, mandatory protection does not mean you have to overpay. By understanding the nuances of policy types, leveraging strategic discounts, and selecting a provider that aligns with your lifestyle, you can effectively control your costs while maximizing your coverage value.
Main Facts: The Current Landscape of Auto Insurance
The auto insurance market is intensely competitive, forcing providers to continuously tweak their rates, rewards systems, and digital onboarding platforms to attract new policyholders. While baseline state requirements remain standardized around liability, the broader marketplace offers a wide spectrum of specialized coverage tiers.
Key structural realities of the current insurance market include:
- The Cost-to-Coverage Balance: Direct-to-consumer online insurers typically offer more aggressive, lower baseline pricing than traditional agencies that rely on human brokers.
- The Rise of Telematics: Usage-based insurance (UBI) programs—which track driving habits via mobile apps or plugged-in vehicle devices—have shifted from experimental perks to primary money-saving tools.
- The Financing Factor: Gap insurance and new-car replacement add-ons have become vital financial buffers as vehicle values fluctuate and repair costs climb.
Chronology and Market Evolution: How We Got Here
The auto insurance sector has undergone a rapid digital transformation over the past decade.
- The Traditional Era: Historically, purchasing car insurance required sitting down with a local agent, poring over paper documents, and waiting days for quote approvals. Customer loyalty was built almost entirely on face-to-face relationships.
- The Aggregator Boom (2010s): The emergence of online quote comparison websites and direct-to-consumer web platforms democratized pricing data, allowing drivers to compare dozens of rates in minutes. Companies like Geico and Progressive dominated this era by prioritizing digital efficiency and constant advertising.
- The Telematics Revolution (Present Day): Today, insurance pricing is increasingly personalized. Insurers like Root and Nationwide utilize smartphone apps and vehicle-tracking hardware to monitor real-time driving metrics—such as speed, braking, and phone usage—rewarding safe drivers with discounts up to 40%.
Supporting Data: Top Car Insurance Providers Compared
To help consumers navigate the market, experts evaluate carriers across multiple vectors, including premium ranges, geographic availability, customer complaint volumes, and digital user experiences.
1. State Farm: Best Overall
While State Farm may not outprice every niche competitor on the market, it offers undeniable, consistent value for drivers nationwide. Its vast network of local agents combined with robust financial stability makes it the reliable gold standard for general drivers.
2. Root Insurance: Best for Good Drivers
Root operates on a modern, app-based model that evaluates your actual driving habits over a test period before issuing a final rate. The company reports that safe drivers save an average of $900 a year. Roadside assistance comes standard, and policy management takes place entirely within a streamlined mobile app.
3. Auto-Owners Insurance: Best Customer Service
Unavailable in certain massive markets like California and Texas, Auto-Owners excels where it is operational. Backed by a dedicated network of hardworking local agents, the company routinely wins high marks for claim satisfaction and personalized customer care.
4. USAA: Best for Service Members and Their Families
Restricted strictly to current military members, veterans, and their immediate families, USAA serves roughly 5% of the U.S. population. Those who qualify enjoy exceptional sign-up incentives, low rates, and loyalty bonuses that save new switchers an average of over $700 in their first year.
5. Nationwide: Best Safe-Driving Discount
Nationwide balances widespread availability with low consumer complaint ratios. It stands out through its SafeRide program, offering an instant 10% discount simply for installing a tracking device, with potential savings scaling up to 40% for exemplary driving behavior.
6. Amica: Best General Policy Discounts
Amica is renowned for its deep discount structure, including up to 30% off for bundling home and auto policies, and up to 25% off for multi-car households. It also offers unique dividend policies that can return up to 20% of premiums over time to claim-free drivers.
7. Allstate: Best for Roadside Assistance
Beyond competitive standard policies, Allstate distinguishes itself by offering robust, 24/7 roadside assistance programs comparable to standalone memberships like AAA. Drivers can purchase annual plans starting as low as $89 or utilize pay-per-use options.
8. Progressive: Best Application Process
Progressive is a household name known for deep discount options and an intuitive onboarding workflow. Its online quote engine and digital claims management system allow for a frictionless user experience from start to finish.
9. Geico: Best for Consistently Low Premiums
For drivers prioritizing cost above all else, Geico delivers consistently low baseline premiums without sacrificing essential coverage quality. While it may lack white-glove customer service touches, policyholders switching to Geico report average annual savings of up to $500.
Official Responses and Industry Methodology
When evaluating auto insurance providers, industry analysts look far beyond flashy commercials. The methodology behind top rankings centers on several key criteria:
- Premium Range & Competitiveness: Preference is given to carriers that maintain low baseline rates and offer genuine savings over time rather than short-term introductory teaser rates.
- Customer Complaint Volumes: Utilizing data from state insurance commissioners and consumer advocacy groups, top-tier rankings heavily penalize companies with disproportionate volumes of unresolved customer complaints.
- Collision Repair Scores: Using industry data like Crash Network’s repair scores, analysts evaluate how easily policyholders can access high-quality repair networks after a collision.
- Discounts and Add-ons: Insurers that reward safe driving, multi-policy bundling, and vehicle safety features score significantly higher in overall consumer value.
Types of Car Insurance Coverage
Before finalizing a policy, drivers must understand the distinct types of coverage available:
- Liability Insurance: Covers bodily injury and property damage you cause to others in an at-fault accident. This is legally required in almost all states.
- Collision Insurance: Pays to repair or replace your vehicle if it is damaged in a crash with another car or a stationary object like a telephone pole or guardrail.
- Comprehensive Insurance: Protects your vehicle against non-collision incidents, including theft, vandalism, weather events, and animal strikes.
- Uninsured/Underinsured Motorist Coverage: Steps in to pay your medical and repair bills if you are hit by a driver who carries insufficient insurance—or none at all.
- Gap Insurance: Essential for financed or leased vehicles. Because cars depreciate rapidly, your loan balance may exceed the car’s actual cash market value; gap insurance covers the difference if the car is totaled.
Implications: What This Means for Consumers
Choosing the right car insurance policy has direct financial implications. Driving without adequate insurance opens you up to catastrophic out-of-pocket expenses—ranging from tens of thousands of dollars in accident liability to severe legal penalties, license suspensions, and steep state fines.
Conversely, being strategic about your coverage ensures you are neither "insurance poor" (paying for unnecessary add-ons) nor dangerously under-protected. By periodically shopping your rate, maintaining a clean driving record, and maximizing safe-driving telematics discounts, you can protect both your physical safety and your household budget.