Old Glory Bank, a boutique financial institution that branded itself as the cornerstone of the "Freedom Economy," is currently navigating a precarious chapter in its short history. After the collapse of a high-profile merger earlier this year, the $279.4 million-asset lender is now contending with strict regulatory oversight, significant capital deficiencies, and the urgent necessity to secure new funding to avoid a potential wind-down of operations.
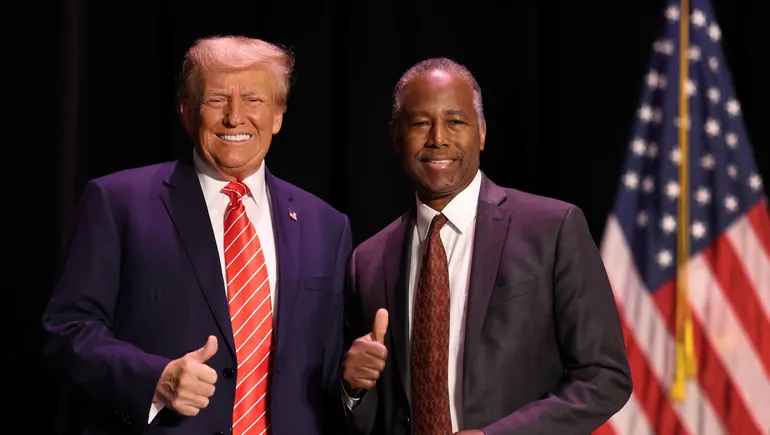
The bank, which counts former Housing and Urban Development Secretary Dr. Ben Carson and former Trump administration press secretary Sean Spicer among its co-founders, has built its reputation on a "pro-America" online banking platform. However, the veneer of ideological branding is currently being overshadowed by the cold reality of banking compliance, as the Federal Deposit Insurance Corporation (FDIC) exerts pressure on the firm to bolster its balance sheet.
The Chronology of a Failed Vision
The instability currently gripping Old Glory Bank can be traced back to the dissolution of its merger agreement with Digital Asset Acquisition Corp., a special-purpose acquisition company (SPAC).
- January 2024: Old Glory Holding Company and Digital Asset Acquisition Corp. announced a definitive merger agreement. The goal was to establish OGB Financial Company, a crypto-focused entity intended for listing on the Nasdaq exchange.
- May 2024: Following an examination of its capital levels, Old Glory Bank was placed under an FDIC consent order. The order cited "insufficient capital," highlighting the bank’s failure to maintain a Tier 1 leverage ratio of at least 14%.
- July 2024: A prospectus filed by Digital Asset Acquisition Corp. revealed the dire stakes of the merger. The bank explicitly warned that if the deal were not consummated, it might be forced into a "sale or organized wind-down" due to its inability to meet regulatory capital requirements.
- August 2024: The merger officially collapsed. A spokesperson for Old Glory confirmed that the Federal Reserve had declined to approve the transaction, effectively scuttling the plan to raise capital through the public markets.
- Post-August 2024: Following the failed merger, the bank was hit with a "prompt corrective action" (PCA) directive from the FDIC, formalizing its status as "significantly undercapitalized."
Financial Strain and Capital Deficiencies
At the heart of the regulatory intervention is a failure to maintain mandatory capital buffers. Under the FDIC consent order established in May, Old Glory was required to maintain a Tier 1 leverage ratio of 14%. In the industry, such high requirements are typically reserved for institutions deemed to be at a higher risk profile or those with aggressive growth strategies that outpace their equity base.
The bank’s leadership had initially hoped to negotiate these requirements down to a range of 7% to 9%, which they viewed as more "reasonable." However, these negotiations were predicated on the success of the SPAC merger, which was intended to inject the necessary liquidity into the bank to satisfy the FDIC’s expectations.
With the merger off the table, the bank’s financial situation has become increasingly acute. According to the June call report from the Federal Financial Institutions Examination Council (FFIEC), Old Glory sustained a loss of approximately $8 million during the first half of 2024. This loss significantly eroded the bank’s capital reserves, pushing it into the "significantly undercapitalized" category—the fourth of five regulatory tiers, one step above "critically undercapitalized."
Official Responses and Strategic Pivot
In the wake of the failed merger and the subsequent PCA directive, leadership at Old Glory Bank has attempted to maintain a posture of resilience. In a statement provided to the media, a spokesperson emphasized that the bank is actively seeking to stabilize its position.
"The Fed knocked us down by not approving our deSPAC, but we are getting back up, and we will continue on our mission of providing all of America the freedom in banking they deserve," the spokesperson said in an email. "We are doing again what we always do, which is raising capital from our great ownership group."
The spokesperson further clarified that the bank is currently engaged in discussions to raise the necessary capital to boost its Tier 1 leverage ratio above the 4% threshold required for a "significantly undercapitalized" institution to begin its climb back to adequacy. Despite the optimistic rhetoric, the bank remains under immense pressure to prove it can survive without the infusion of capital that the Nasdaq listing would have provided.
Regulatory Implications and Operational Constraints
The FDIC’s prompt corrective action directive is not a suggestion; it is a rigid framework of operational limitations designed to protect depositors and the Deposit Insurance Fund. Because Old Glory is now classified as "significantly undercapitalized," it faces a series of restrictive measures that fundamentally alter how the bank conducts business.
Restrictions on Growth and Activity
Under the PCA directive, Old Glory Bank is prohibited from accepting brokered deposits—a common tool for smaller banks to raise liquidity. Furthermore, the bank is restricted from accepting employee benefit deposits until it achieves a status of "adequately capitalized."
Compensation and Governance Controls
The directive imposes strict limitations on executive compensation. The bank is prohibited from paying bonuses or increasing the compensation of any senior executive without express prior approval from regulators. Additionally, the FDIC has mandated that the bank must ensure it is managed by "qualified senior executive officers," placing the bank’s leadership structure under the microscope.
Interest Rate Caps
To prevent the bank from engaging in "unsafe or unsound" practices, such as bidding aggressively for deposits to stay afloat, the FDIC has placed a cap on the interest rates the bank can offer to depositors. This limits the bank’s ability to attract new funds through competitive pricing, creating a "catch-22" where the bank needs capital but is restricted in its ability to offer the market rates necessary to attract it.
Reporting and Compliance
The bank is now required to submit written reports to the FDIC on a monthly basis, detailing its compliance with the directive and the specific steps being taken to correct its capital position. These provisions will remain in effect until the bank has maintained a status of "adequately capitalized" for four consecutive quarters—a high hurdle for an institution currently recording multi-million dollar losses.
The Path Forward: Survival or Exit?
The future of Old Glory Bank remains uncertain. In its July prospectus, the bank warned that "if we take neither of these alternative actions [merger or capital raise], we would expect other regulatory actions to be taken, including actions to enjoin ‘unsafe or unsound’ practices."
The "Freedom Economy" branding, which focuses on providing banking services to a demographic that perceives traditional banking as ideologically compromised, has garnered a loyal, albeit niche, customer base. However, the regulatory reality is indifferent to the political positioning of the institution. Banking is a business of margins and regulatory compliance; when a bank falls significantly below its capital requirements, the focus shifts entirely to the protection of depositors and the stability of the financial system.
For Old Glory, the road ahead involves convincing its existing ownership group to provide a substantial infusion of capital while simultaneously convincing federal regulators that the bank has a sustainable, long-term business model. The losses sustained in the first half of 2024 suggest that the bank’s current operational costs may be unsustainable relative to its revenue generation.
As the bank works to satisfy the monthly reporting requirements and navigate the restrictions imposed by the PCA, observers in the banking sector will be watching closely. Whether Old Glory can secure the necessary capital to satisfy the FDIC or if it will be forced into the "organized wind-down" it previously mentioned remains the central question for the firm. For now, the "Freedom Economy" bank finds itself in a fight for its very existence, constrained by the same regulatory machinery it once hoped to navigate through the public markets.