Main Facts: Redefining Real Estate Access
The traditional narrative of real estate investing often gatekeeps the industry behind high-barrier requirements: a specialized finance degree, a substantial inheritance, corporate wealth, or a pristine high-paying salary. However, a growing movement of grassroots investors is completely upending this misconception. Proof of this shift can be found in the inspiring journey of Arden Williams and his wife, who proved that financial freedom is accessible to anyone willing to embrace short-term discomfort for long-term gain.
Starting their professional lives earning a modest $12 to $14 an hour as a teaching assistant and a firefighter in training, Williams and his partner built a thriving real estate portfolio from the ground up. Through a disciplined combination of house hacking, strategic live-in flips, and Accessory Dwelling Unit (ADU) development, the couple accumulated three single-family rental properties and an additional building lot by 2026. Most remarkably, the passive income generated by these properties allowed them to quit their traditional jobs and fund a life-changing, year-long trip around the world.
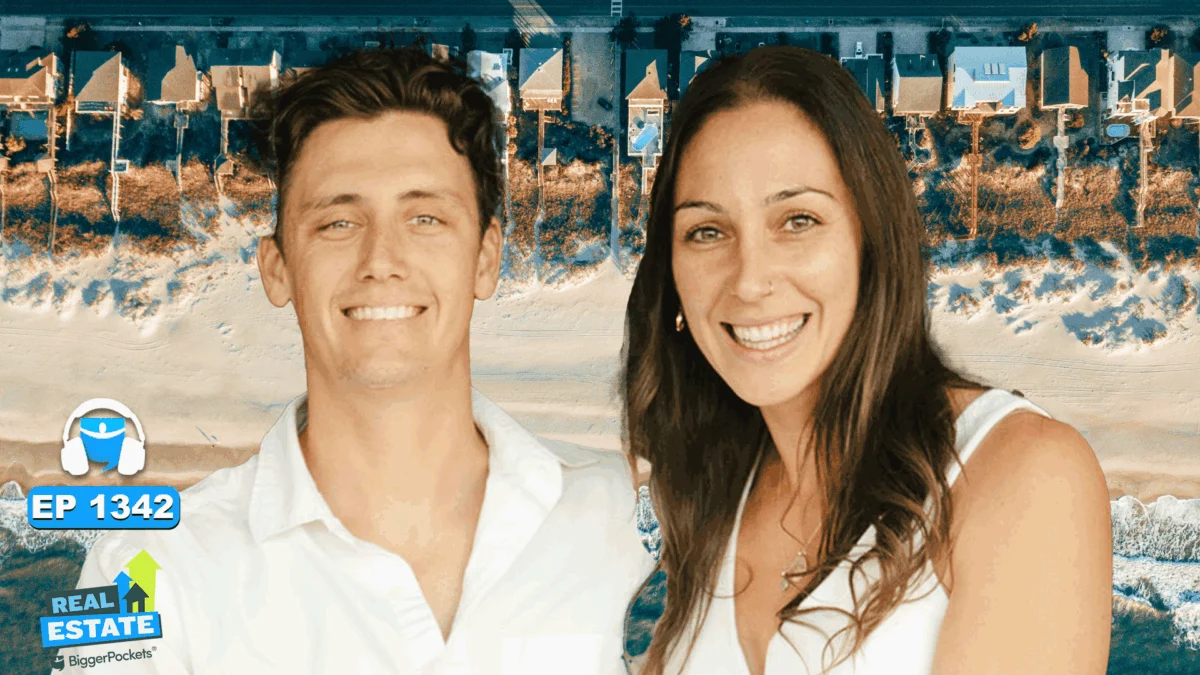
Appearing on an episode of the BiggerPockets Podcast hosted by Henry Washington, Williams detailed the exact, repeatable blueprint they used to transform entry-level wages into a portfolio that commands financial independence.
Chronology: The Step-by-Step Evolution of a Portfolio
The path from minimum-wage earners to self-sufficient real estate investors did not happen overnight. It was executed through a methodical, multi-year timeline of calculated risks and deliberate lifestyle choices.
Phase 1: Breaking into the Market (November 2021)
Following a stint living in Hawaii and the U.S. Virgin Islands, Williams and his wife relocated to Wilmington, North Carolina, where Williams began his career as a firefighter. Earning roughly $12 to $14 an hour, they purchased their first property: a 3-bedroom, 2-bathroom single-family home for $285,000—paying $20,000 over asking price in a competitive 2021 market.
To offset the financial strain, they deployed a classic house-hacking strategy, renting out the spare rooms to two fellow firefighters for $700 each per month. Utilizing a conventional 30-year fixed mortgage with a 3% interest rate and a $30,000 down payment saved from their time in the islands, their monthly housing costs plummeted. Their roommates’ rent nearly covered the entire $1,300 monthly mortgage, allowing Williams and his wife to essentially live for free.
Phase 2: Scaling Through Repetition (July 2023)
Armed with equity and lessons learned from their first venture, the couple executed their second house hack a year and a half later. Purchased in July 2023 for $325,000, this historic 123-year-old home in downtown Wilmington came with an unexpected bonus: an additional adjacent lot.
Despite facing a higher interest rate of 6.8% and putting down $52,000, Williams maintained the house-hacking model. They brought in a friend and a Zillow-sourced tenant, collecting $1,500 combined in monthly rent against a roughly $1,900 mortgage. Though they faced a minor out-of-pocket expense each month, the acquisition of the extra lot—which they later split off—created massive hidden equity. Today, empty lots of that size in the area command upwards of $70,000.
Phase 3: The Live-In Flip and ADU Expansion (2024–Present)
Moving away from standard house hacking for their third property, Williams and his wife transitioned to a live-in flip strategy. They purchased a 3-bedroom, 2-bathroom home sitting on a rare half-acre lot in Wilmington for $270,000, funding a $25,000 cosmetic and structural renovation out of pocket.
Recognizing regulatory changes in Wilmington that welcomed Accessory Dwelling Units (ADUs), Williams leveraged the property’s expansive lot. After securing a HELOC (Home Equity Line of Credit) and navigating the municipal permit process, Williams broke ground on a 570-square-foot, one-bedroom, one-bathroom detached ADU projected to cost $128,000.
Supporting Data: The Financial Breakdown
Understanding the math behind Williams’ portfolio highlights how micro-sacrifices compound into macro-wealth. Below is a snapshot of the properties that fuel his financial freedom:
- Property 1 (Acquired Nov 2021):
- Purchase Price: $285,000 (3% interest rate)
- Down Payment: $30,000
- Initial Setup: House hacked with two roommates paying $700/month each.
- Current Performance: Now fully rented to a single tenant group at $2,450/month against a $1,550 mortgage (including taxes, insurance, and wind/hail coverage), yielding a steady $900 monthly surplus.
- Property 2 (Acquired July 2023):
- Purchase Price: $325,000 (6.8% interest rate, came with an extra lot)
- Down Payment: $52,000
- Initial Setup: House hacked with two roommates paying $1,500 combined.
- Current Performance: Rented out to long-term tenants for $2,500/month after a lot-split and subsequent mortgage adjustments.
- Property 3 & ADU Project (Current):
- Purchase Price: $270,000
- Renovation Cost: $25,000
- ADU Build Cost: $128,000 (financed partially via a $45,000 HELOC)
- Projected ADU Rent: $1,200 to $1,500/month.
Official Responses and Expert Insights
During his appearance on the BiggerPockets Podcast, Williams engaged in a deep-dive conversation with co-host Henry Washington regarding the psychological and mechanical hurdles of starting small.
Washington praised Williams’ ability to execute multiple owner-occupied investment strategies—ranging from traditional house hacking to live-in flipping—without relying on inherited wealth or high corporate salaries.
"What I love about your story is it is such an achievable path. Anybody can go down this route," Washington noted during the interview. "You should be proud of what you built. Real estate is not a short-term gain; it’s a long-term play."
Addressing critics who might feel intimidated by rising interest rates or higher property values, Williams emphasized that tactical adjustments—such as putting down larger chunks of capital to manufacture equity and cash flow—can bridge the gap when market conditions shift unfavorably.
Williams also highlighted the value of professional flexibility. After earning his real estate license in February, he not only saved on transaction costs for his own portfolio but also positioned himself to guide peers through similar wealth-building trajectories.
Implications: The Blueprint for Modern Financial Freedom
The journey of Arden Williams carries significant implications for a generation of prospective buyers grappling with high inflation, elevated interest rates, and soaring housing costs.
1. The Death of Lifestyle Creep
Williams attributes much of his success to aggressive frugality and hyper-awareness of spending habits. Alongside his wife—who acted as the household’s spreadsheet manager—Williams avoided lifestyle inflation. For four years, despite cold weather and grueling shifts as a firefighter, Williams commuted exclusively on a motorcycle to minimize auto-related expenses. By consciously rejecting unnecessary expenditures like frequent dining out, they preserved capital for down payments.
2. Redefining "Uncomfortable" Living
House hacking requires sharing personal living spaces with roommates or tenants. While initially daunting, Williams frames this inconvenience as a minor trade-off for generational wealth. Living for free or minimal cost during early adulthood eliminated housing expenses, allowing their entry-level wages to be funneled directly into investment capital rather than landlord pockets.
3. Scalable Self-Management
Many aspiring real estate moguls feel pressured to build massive portfolios consisting of dozens or hundreds of units. Williams intentionally capped his long-term goal at six to ten properties. By choosing to self-manage his assets, he maintains control over his time, ensuring that real estate serves his lifestyle—funding global travel and early retirement—rather than chaining him to a full-time property management job.
Ultimately, Williams’ story serves as a masterclass in resourcefulness. By trading short-term comfort for sustainable assets, everyday earners can dismantle the myth that real estate is exclusively reserved for the affluent, proving instead that anyone with discipline, a budget, and a willingness to house hack can rewrite their financial future.