Author: Holly Welles
Updated: July 23, 2026
Main Facts: The Reality of Drained Savings and the Path Forward
Facing a financial emergency is a destabilizing experience. Whether it is an unexpected medical emergency, catastrophic car repairs, or the sudden loss of primary employment, the immediate aftermath often leaves individuals staring at a zeroed-out bank account.
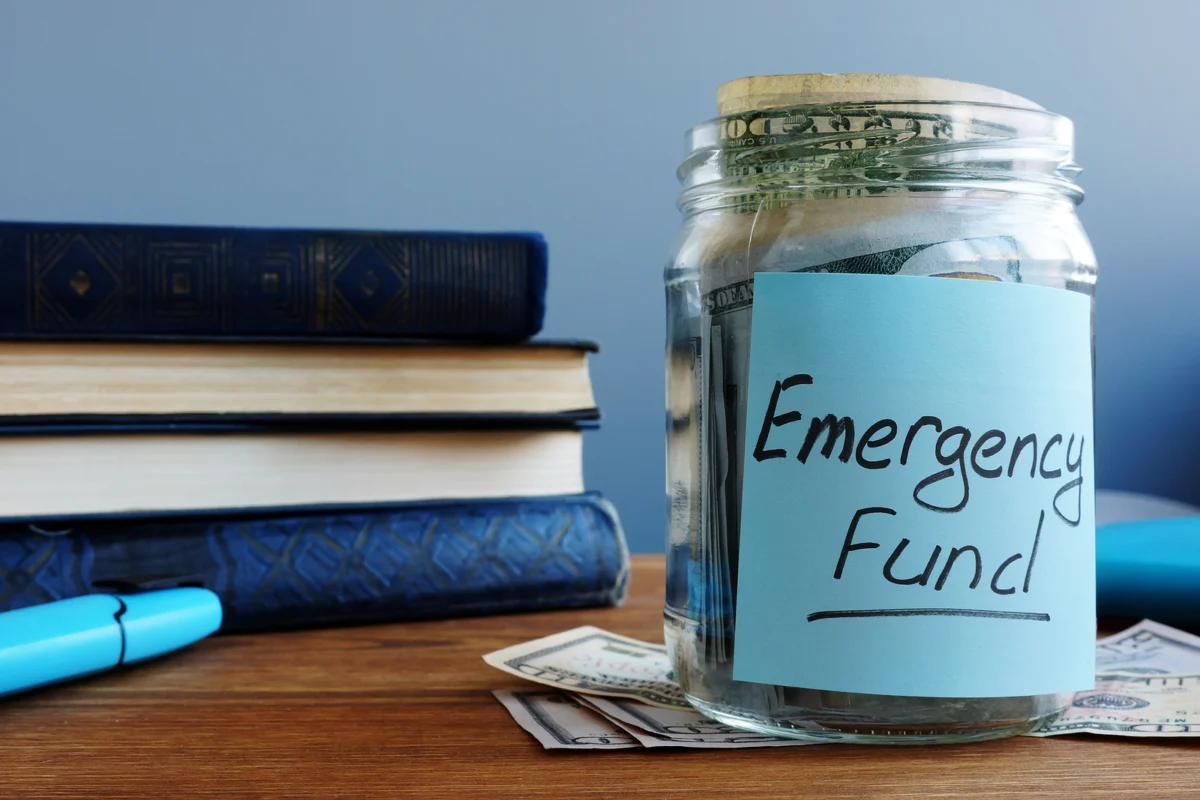
However, financial experts emphasize a foundational truth: seeing an emergency fund evaporate is not a failure of financial planning; it is the exact reason the fund exists. Cash reserves are not meant to sit untouched in perpetuity; they are liquid insurance policies designed to be deployed during life’s unpredictable moments.
Yet, once the acute phase of a crisis passes, a new vulnerability sets in. Living without a financial safety net exposes households to secondary shocks, where even a minor unexpected expense can trigger a cascade of high-interest debt. Rebuilding an emergency fund is not merely a matter of accumulating numbers in a ledger—it is the cornerstone of psychological resilience and long-term economic stability.
While rebuilding a fully funded emergency account—typically recommended to cover three to six months of essential living expenses—can feel like an insurmountable mountain, recovery is achieved through incremental, structured steps.
Chronology: The Step-by-Step Lifecycle of Financial Recovery
Rebuilding financial health requires a deliberate sequence of operations. Moving haphazardly often leads to burnout or prolonged vulnerability. The recovery timeline can be categorized into distinct phases:
Phase 1: The Immediate Aftermath and Assessment (Weeks 1–2)
Once the immediate crisis has resolved (e.g., the medical bill is paid or the car is repaired), resist the urge to immediately panic about savings. Instead, spend the first two weeks taking stock of the damage. Review account balances, list remaining debts, and determine the exact baseline required to survive month-to-month.
Phase 2: Budget Realignment (Month 1)
Income and expense parameters rarely remain static after a major life event. Phase 2 involves constructing an updated monthly budget. By documenting every incoming dollar and fixed expense, households can identify the exact surplus—or deficit—they are working with under current conditions.
Phase 3: Cash Flow Enhancement and Strategic Cuts (Months 2–6)
With a realistic budget established, the focus shifts to widening the gap between income and expenses. During this middle phase, individuals aggressively pursue temporary side hustles, explore avenues for career advancement, and strip away nonessential spending to funnel maximum capital toward the rebuilding effort.
Phase 4: Long-Term Stabilization and Goal Realignment (Month 6 and Beyond)
Once a basic starter emergency fund (e.g., $1,000 to one month of expenses) is secured, broader financial goals—such as aggressive debt payoff or homeownership savings—can be safely reintroduced. Concurrently, monthly reviews are institutionalized to ensure lifelong financial hygiene.
Supporting Data: The Vulnerability Gap in Modern Households
Economic data consistently highlights the precarious nature of personal finance and the vital role liquid savings play in preventing long-term financial ruin.
- The Savings Deficit: According to recurring consumer financial surveys, nearly half of all adults lack sufficient liquid savings to cover a sudden $1,000 emergency without resorting to credit cards or borrowing from family.
- The Debt Trap: Households that deplete their savings and subsequently face a second emergency within a 12-month window are nearly three times more likely to default on unsecured debt or enter formal debt management programs.
- Mental Health Correlations: Financial psychologists note that chronic financial insecurity—stemming directly from a lack of emergency reserves—is a leading contributor to stress-related health issues, lost workplace productivity, and relational strain.
- The Bounce-Back Metric: Data tracking consumer recovery curves indicates that individuals who systematically update their budgets within 30 days of a financial shock rebuild their savings reserves 40% faster than those who attempt to "wing it" without formal adjustments.
Official Perspectives: Expert Insights on Financial Rehabilitation
Financial counselors and consumer advocacy organizations stress that recovery is as much a behavioral challenge as it is a mathematical one.
The Role of Certified Professionals
Representatives from organizations such as the National Foundation for Credit Counseling (NFCC) frequently highlight that individuals do not need to navigate the recovery landscape alone. Certified credit counselors provide objective, non-judgmental evaluations of household budgets, helping consumers distinguish between temporary cash-flow problems and systemic overspending.
"An emergency fund is your primary line of defense against the unexpected," notes a senior credit counselor with the NFCC. "When that fund is gone, your margin for error drops to zero. Working with a professional allows you to triage your expenses, restructure your mindset, and create a realistic runway back to financial security without falling into the trap of shame or deprivation."
Furthermore, behavioral finance experts emphasize that financial recovery requires shielding oneself from societal pressures to maintain pre-crisis consumption levels. Recognizing that a temporary lifestyle contraction is a temporary tactical retreat—not a permanent downgrade—is essential for mental well-being during the rebuilding process.
Implications: Strategic Actions for Long-Term Resilience
To successfully transition from survival mode back to prosperity, households must implement five core strategies derived from financial best practices.
1. Update Your Budget with Granular Precision
An emergency often alters income streams, fixed costs, or both. Rebuilding mandates a freshly minted monthly budget.
- Audit Income and Fixed Expenses: Document current, reliable income sources and tally non-negotiable monthly expenses (housing, utilities, baseline groceries, debt minimums).
- Account for Irregular Costs: Use historical data to average out sporadic expenses. For instance, if annual travel or auto maintenance totals $1,200, allocate $100 per month into a dedicated ledger item so these costs never blindside your recovering savings again.
2. Aggressively Boost Your Income Streams
Cutting expenses has a mathematical floor—you can only cut down to zero—but income has an infinite upward ceiling.
- Leverage the Gig Economy: Short-term side hustles (babysitting, pet-sitting, freelance digital work) can accelerate emergency fund accumulation.
- Maximize Primary Earning Power: Evaluate current market rates for your skill set. Schedule a performance conversation with your manager to explore pathways to a promotion, or test the broader job market for higher-paying opportunities.
3. Implement Tactical, Temporary Expenditure Cuts
Drastic measures can backfire if they feel like permanent punishment, but temporary lifestyle trimming speeds up recovery exponentially.
- Identify Low-Priority Outlays: Pause nonessential entertainment subscriptions, reduce dining out, and defer luxury purchases.
- Maintain Balance: Avoid extreme deprivation. Cutting out every small joy often triggers "financial bingeing," where frustration leads to impulsive, high-dollar spending sprees that undo months of hard work.
4. Temporarily Pause Secondary Financial Goals
Human psychology loves the satisfaction of checking off major goals—such as paying down student loans early or saving for a down payment on a home. However, prioritizing these goals over an empty emergency fund is a high-risk gamble.
- Put First Things First: Acknowledge that your safety net is your most important short-term goal. Once your emergency fund is restored to a healthy level, you can redirect those funds toward long-term wealth-building with absolute peace of mind.
5. Institutionalize Monthly Progress Reviews
Financial health is an ongoing maintenance project, not a one-time destination.
- Conduct End-of-Month Audits: Review your actual spending against your budget every 30 days. This habit allows you to course-correct minor variances before they derail your progress, while also providing positive reinforcement as you watch your savings account balance grow.
Conclusion: Securing Your Future Peace of Mind
Rebuilding an emergency fund requires patience, discipline, and a willingness to adapt to changing circumstances. While the journey from a depleted account to a robust safety net demands sacrifice, the psychological dividends are immeasurable.
When a fully funded emergency reserve sits in your account, future financial shocks lose their power to terrorize. You are no longer one flat tire or unexpected medical bill away from crisis; instead, you possess the autonomy to handle life’s uncertainties with confidence. If the path forward feels overwhelming, reach out to an NFCC-certified credit counselor to gain personalized guidance, structured budgeting support, and a clear roadmap toward lasting financial wellness.