By Sarah Brady, National Foundation for Credit Counseling (NFCC)
Published: September 14, 2026
Main Facts
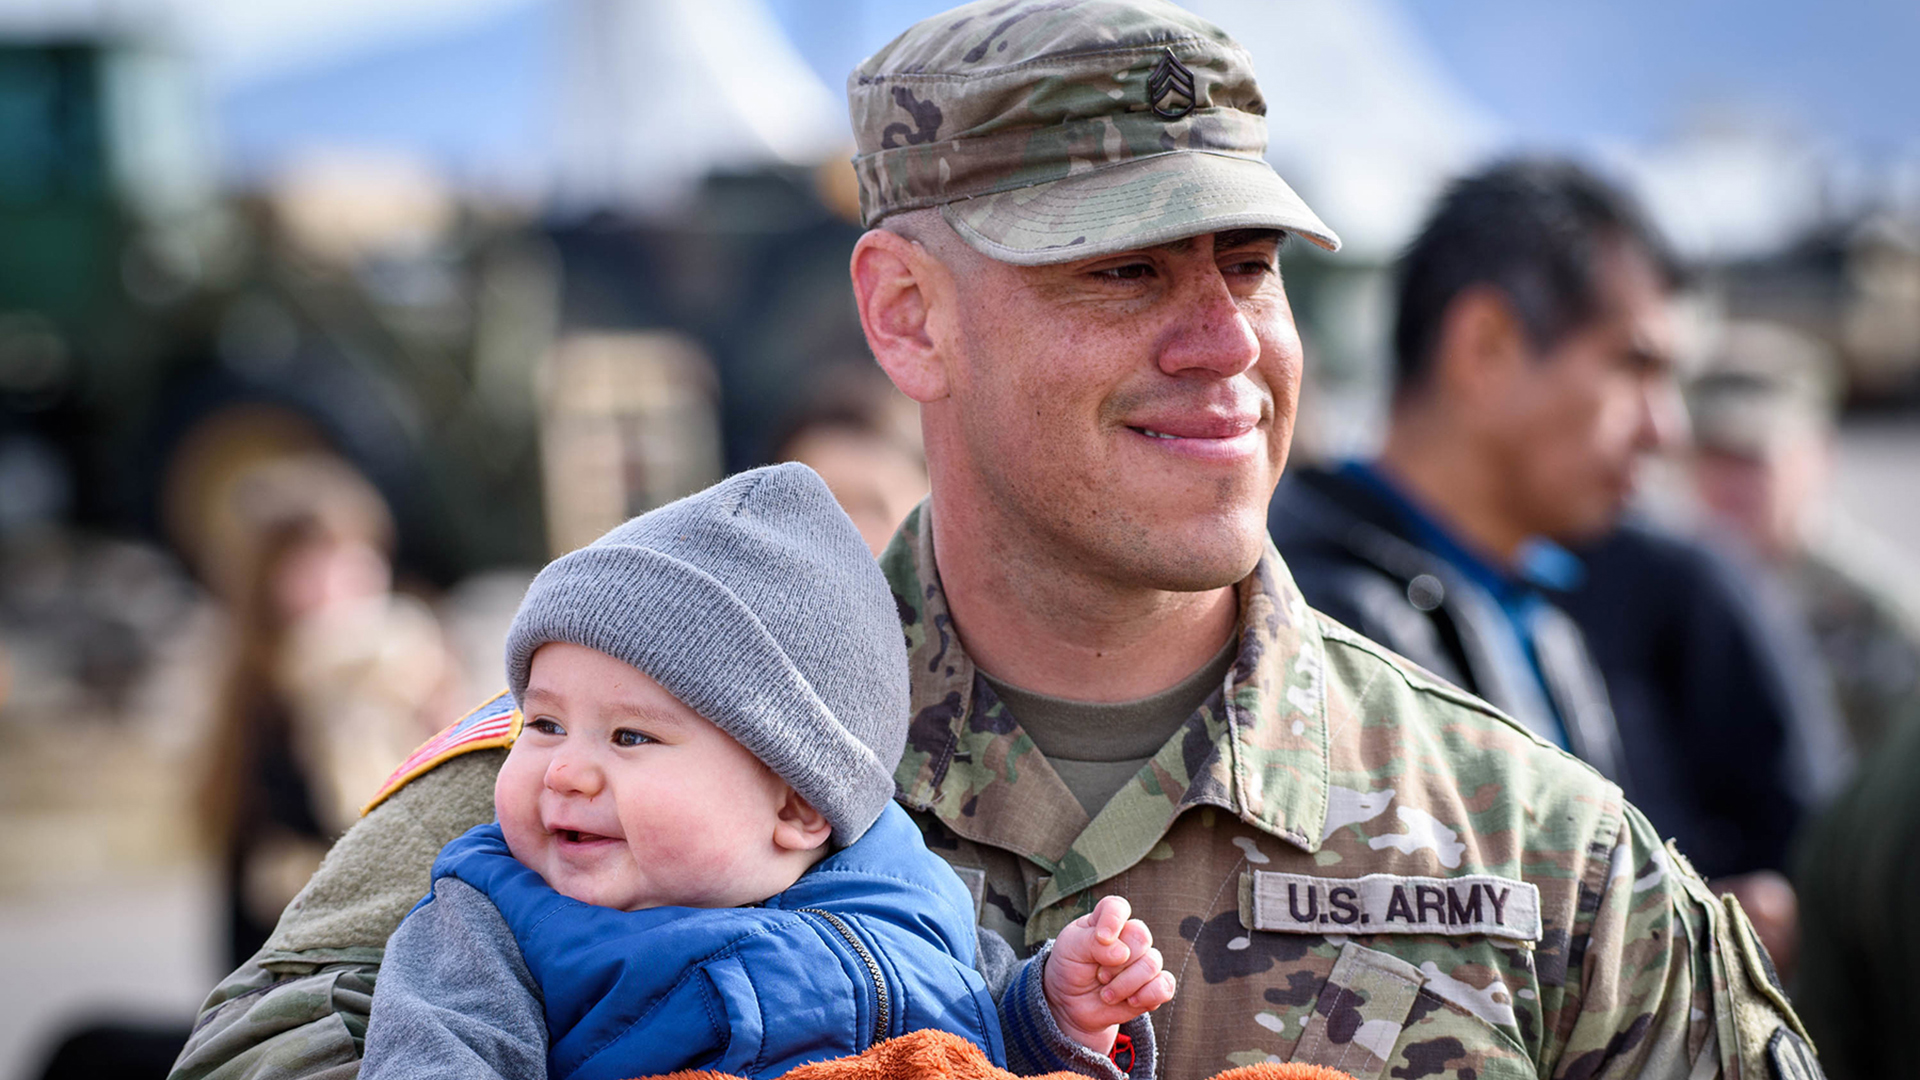
As the broader American populace continues to grapple with persistent inflation and a volatile cost-of-living index, military households frequently bear the brunt of these economic pressures. Frequent relocations, unique employment barriers for military spouses, and the complexities of transitioning back into civilian life create a distinct set of financial vulnerabilities for those who wear the uniform.
Recent data underscores the urgency of these challenges. According to the 2025 Financial Literacy and Preparedness Survey conducted by the National Foundation for Credit Counseling (NFCC) and The Harris Poll, a striking 50% of active-duty service members reported that they were merely "just getting by financially." Furthermore, the survey revealed that 42% of veterans feel they lack adequate information regarding the expansive network of financial resources, grants, and support systems theoretically available to them.
To bridge this information gap, a wide array of federal agencies, nonprofit networks, and military-specific organizations offer robust relief mechanisms. From branch-specific emergency grants and innovative Department of Veterans Affairs (VA) foreclosure-prevention initiatives to targeted spouse-employment pipelines and specialized credit counseling, the architecture for financial stability exists. However, navigating these disjointed programs remains a primary hurdle for service members, veterans, and their families.
Chronology of Modern Military Financial Assistance
The framework supporting military financial readiness has evolved significantly over the past century, transitioning from informal unit-level benevolence to sophisticated, institutionalized federal and nonprofit programs.
- Early 20th Century: The establishment of branch-specific relief societies (such as the Army Emergency Relief in 1942) laid the groundwork for institutionalized, emergency financial aid funded largely by service members for service members.
- Post-WWII Era: The introduction of the original G.I. Bill fundamentally transformed veteran economic security, tying military service to long-term wealth building through education and homeownership.
- The 21st Century Transition Era: As deployments spiked following 2001, federal agencies and non-governmental organizations recognized the compounding economic stress on families, leading to the creation of targeted family-readiness centers on bases worldwide.
- June 2026: In a major modern policy update, the Department of Veterans Affairs officially launched the VA Partial Claim Program, giving struggling homeowners an advanced tool to avoid foreclosure by shifting overdue mortgage amounts to the end of the loan lifecycle.
- Present Day (Late 2026): Organizations like the NFCC continue to scale digital and in-person financial counseling infrastructures, integrating specialized credit management with comprehensive federal benefit mapping to address post-pandemic economic strains.
Supporting Data & Economic Realities
The economic landscape for military families is defined by specific structural challenges that distinguish their financial profiles from civilian counterparts. While military compensation includes base pay, allowances for housing and subsistence (BAH and BAS), and healthcare through TRICARE, these safety nets are frequently outpaced by localized inflation spikes during Permanent Change of Station (PCS) moves.
Key Survey Indicators (NFCC & Harris Poll)
- 50% of active-duty service members state they are "just getting by financially."
- 42% of veterans express a critical need for better information regarding available financial resources and legal protections.
- 1 in 3 military spouses report facing underemployment or career stagnation due to frequent interstate or international relocations.
These statistics illuminate a paradox: while military service guarantees steady employment and healthcare, the transient nature of the lifestyle creates systemic vulnerabilities in emergency savings, trailing spouse income, and long-term asset accumulation.
Official Responses and Available Resources
Faced with mounting economic pressures, federal and nonprofit entities have deployed multi-layered intervention strategies. Service members and veterans who find themselves in financial distress have access to several distinct pillars of relief.
1. Branch-Specific Military Relief Organizations
Each branch of the United States Armed Forces maintains a dedicated, non-profit relief organization designed to provide rapid, confidential financial assistance. These entities offer interest-free loans, outright grants, and educational scholarships for qualified service members (active and retired) and their dependents:
- Army Emergency Relief (AER)
- Navy-Marine Corps Relief Society (NMCRS)
- Air Force Aid Society (AFAS)
- Coast Guard Mutual Assistance (CGMA)
These organizations routinely step in during emergency situations—such as vehicle repairs, unexpected medical bills, or travel expenses for family emergencies—preventing families from turning to predatory payday lenders.
2. VA Mortgage Assistance and Foreclosure Prevention
Housing instability remains a major stressor for veterans. The VA oversees several foreclosure-prevention programs aimed at keeping veterans in their homes when they fall behind on VA-backed mortgages. These include specialized loan modification protocols designed to adjust monthly obligations.
The crown jewel of recent federal housing interventions is the VA Partial Claim Program, launched in June 2026. This program operates on a structured timeline:
- Trial Period: The homeowner completes a mandatory three-month trial payment plan to demonstrate sustained capacity to cover future, ongoing mortgage payments.
- Arrearage Resolution: Once the trial is successfully completed, the loan servicer covers the overdue mortgage amount via a partial claim.
- Deferred Repayment: The accumulated balance is converted into a zero-interest, subordinate lien that is only repaid when the primary mortgage is fully satisfied, refinanced, or the home is sold.
3. Employment and Career Programs for Military Spouses
Because frequent relocations disrupt career trajectories, targeted employment pipelines have been established to stabilize household income.
- SpouseWorks: A government-backed initiative offering specialized career coaching, remote work opportunities, and educational support tailored to the unique realities of military life.
- Hiring Our Heroes (HOH): Operated by the U.S. Chamber of Commerce Foundation, HOH provides comprehensive career counseling, digital networking events, corporate fellowships, and resume-building workshops explicitly designed for veterans, transitioning service members, and military spouses.
4. Student Loan Benefits and Legal Protections
Service members managing higher education debt can leverage unique statutory protections under federal and state laws, most notably the Servicemembers Civil Relief Act (SCRA) and the Higher Education Act.
- Interest Rate Caps: Under the SCRA, active-duty service members can cap the interest rates on pre-service debts—including student loans—at 6%.
- Public Service Loan Forgiveness (PSLF): Active-duty military service counts toward the 120 qualifying monthly payments required for federal student loan forgiveness.
- Private Loan Forbearance: Private lenders are frequently mandated or encouraged to offer military service forbearance options during active deployment periods.
5. Supplemental Relief Agencies and Local Support
When standard military channels do not fully cover an emergent need, a vast ecosystem of non-governmental organizations stands ready to assist. Organizations such as the American Red Cross, United Service Organizations (USO), and various veterans service organizations (VSOs) provide localized aid. Additionally, visiting a local Veterans Service Center (VSC) remains one of the most effective ways for veterans to conduct a comprehensive audit of their benefits and file for disability compensation, pension adjustments, or educational stipends.
Implications: The Role of Nonprofit Credit Counseling
While grants, loans, and structural programs offer vital stopgap measures, long-term financial health requires proactive debt management and budgeting literacy. This is where nonprofit credit counseling plays a transformative role for military families experiencing chronic financial stress.
The National Foundation for Credit Counseling (NFCC) oversees a nationwide network of accredited agencies that specialize in equipping service members and veterans with tools to regain control of their financial lives. Core services include:
- Certified Financial Reviews: One-on-one sessions with NFCC-certified counselors who analyze income-to-debt ratios and build personalized household budgets.
- Debt Management Plans (DMPs): In complex cases, counseling agencies negotiate directly with creditors to lower interest rates, waive late fees, and consolidate multiple unsecured debt payments into a single, manageable monthly deposit.
- Credit Report Navigation: Helping veterans understand how to read, protect, and repair credit scores that may have been damaged during turbulent transitions or medical emergencies.
Crucially, many of these nonprofit services are provided free of charge or at a nominal, sliding-scale cost, ensuring that military families do not fall victim to commercial debt-settlement scams that can worsen their financial standing.
Looking Ahead
As the economic environment continues to test American households, the systems supporting military readiness and veteran well-being must remain adaptable. By proactively leveraging branch-specific relief, modern VA housing programs, spouse employment pipelines, and certified nonprofit credit counseling, service members and veterans can insulate their families against economic shocks and build a foundation of lasting financial security.
Service members and veterans seeking guidance can schedule an appointment through the NFCC agency locator to connect with a certified counselor today.