By PYMNTS
Published: October 2, 2026
Main Facts
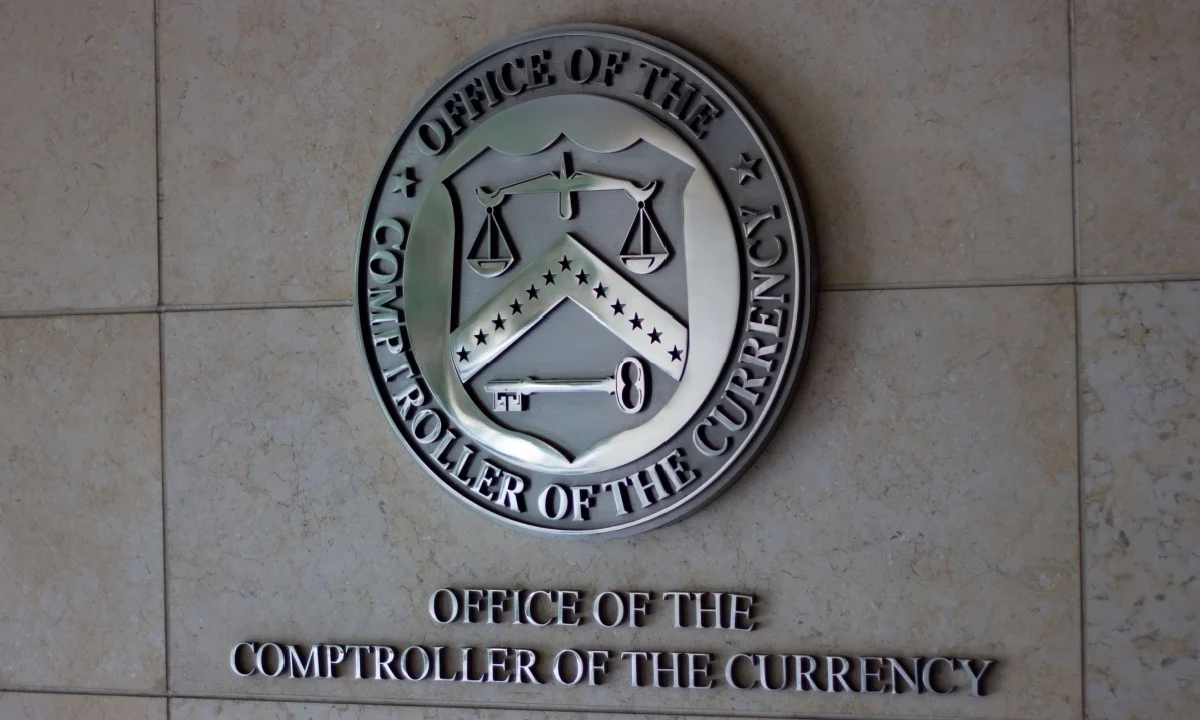
The Independent Community Bankers of America (ICBA) has filed a federal lawsuit against the Office of the Comptroller of the Currency (OCC). The legal challenge, lodged on Friday, October 2, 2026, targets the regulatory agency’s March 2 final rule and Interpretive Letter No. 1176.
According to the ICBA, the OCC has overstepped its statutory boundaries by allowing digital asset and cryptocurrency firms to acquire national trust bank charters. The association argues that these rules act as a "side door" into the heavily regulated U.S. banking system, enabling non-traditional entities to bypass the rigorous oversight, compliance standards, and consumer obligations that traditional community banks must follow.
At the heart of the dispute is whether the OCC possesses the authority under the National Bank Act to charter national trust banks that engage in substantial non-fiduciary activities. The ICBA is asking a federal court to declare both the final rule and the associated interpretive letter unlawful, effectively halting what it views as an unchecked regulatory expansion favoring the fintech and crypto sectors.
Chronology of Events
The friction between traditional banking advocates and federal regulators regarding national trust charters has evolved over several years through a series of key policy shifts, rulemakings, and legal escalations:
- Pre-2026 Guidance Era: The OCC historically supervised national trust banks, many of which engaged in limited non-fiduciary custody and safekeeping services alongside traditional fiduciary responsibilities. However, ambiguity in regulatory texts began to surface as digital asset firms and fintechs sought federal charters to legitimize their operations.
- March 2, 2026 (The Final Rule): The OCC issued a final rule regarding National Bank Chartering, amending its regulations to clarify the "longstanding authority of national banks limited to the operations of trust companies and activities related thereto to engage in non-fiduciary activities in addition to their fiduciary activities." The agency maintained that the rule merely eliminated historical confusion and aligned agency texts with the National Bank Act without expanding its statutory chartering authority.
- March 2, 2026 (Immediate Industry Reaction): Financial technology and banking policy analysts immediately flagged the rule’s implications, noting that explicit references to "operations of a trust company and activities related thereto" provided a regulatory runway for trust-chartered entities to pursue an expanded scope of non-fiduciary commercial activities.
- October 2, 2026 (The Lawsuit): Citing existential concerns over regulatory arbitrage and unequal playing fields, the ICBA officially filed its lawsuit in federal court against the OCC, seeking to vacate the March 2 final rule and Interpretive Letter No. 1176.
- October 2, 2026 (Industry Endorsements): Major traditional banking groups, including the Bank Policy Institute (BPI), stepped forward to voice support for increased regulatory scrutiny on novel entities seeking trust charters, echoing concerns that trust frameworks are being misapplied for full-service banking ambitions.
Regulatory Framework and Background Data
To fully understand the gravity of the ICBA’s lawsuit, it is necessary to examine the structural differences between traditional insured depository institutions (IDs) and national trust banks under federal law.
Traditional Community Banks vs. National Trust Banks
Traditional commercial and community banks operate under rigorous federal oversight. They are bound by:
- The Community Reinvestment Act (CRA): Mandates that banks help meet the credit needs of the communities in which they operate, including low- and moderate-income neighborhoods.
- Federal Deposit Insurance Corporation (FDIC) Insurance: Protects consumer deposits up to statutory limits, backed by strict capital, liquidity, and risk-management standards.
- Consolidated Supervision: Comprehensive oversight by federal regulators (such as the OCC, Federal Reserve, and FDIC) covering every aspect of safety, soundness, and consumer compliance.
Conversely, national trust banks historically focused on fiduciary duties—such as managing estates, administering trusts, and providing custody services—without necessarily taking traditional consumer deposits or participating in commercial lending on a mass scale.
The Regulatory Argument for the Rule
When the OCC published its final rule in March 2026, it defended its position by stating that the text was designed to streamline regulations and clear up inconsistencies. The agency asserted that national banks limited to trust operations have always possessed the inherent authority to conduct related non-fiduciary activities. According to the OCC’s framing, the rule did not grant any novel powers, nor did it expand the agency’s overarching authority to charter national banks.
The Critics’ Counter-Argument
The ICBA and supporting trade organizations view this interpretation as a dangerous loophole. By allowing crypto firms to secure national trust charters, the OCC allegedly permits these technology-driven companies to project the credibility and trust associated with a federal bank charter while evading the costly obligations of the CRA, FDIC insurance premiums, and comprehensive consolidated supervision. Critics argue this creates a two-tiered system where traditional institutions bear heavy regulatory burdens while digital asset startups enjoy streamlined, lower-cost access to the federal banking perimeter.
Official Responses and Stakeholder Perspectives
The legal challenge has drawn sharp reactions from key figures across the American banking and regulatory landscape.
ICBA Leadership
Rebeca Romero Rainey, President and CEO of the ICBA, pulled no punches in her public statements regarding the lawsuit:
"The OCC’s decision to allow companies to obtain national trust bank charters to conduct substantial non-fiduciary activities exceeds the authority Congress granted the agency," Romero Rainey stated. "Congress did not create the national trust charter as a side door into the banking system for crypto firms seeking the credibility of a federal bank charter without the Community Reinvestment Act obligations, consolidated supervision, capital and liquidity standards, and FDIC insurance that apply to insured depository institutions."
Bank Policy Institute (BPI)
The BPI echoed the ICBA’s sentiment, emphasizing that innovative business models should not be granted regulatory shortcuts. Paige Pidano Paridon, Executive Vice President and Co-Head of Regulatory Affairs at BPI, released a statement highlighting the institute’s position:
"As we’ve said in comments filed on numerous national trust bank charter applications, BPI supports efforts to bring innovative new products and services into the regulated banking ecosystem, provided that the entities engaging in those activities are subject to the same rules and responsibilities as every other chartered institution engaging in the same activities," said Paridon. "Companies should not receive trust charters unless they plan to limit their operations to genuine trust activities. If they want to engage in traditional banking activities, they should seek full-service banking charters."
The OCC’s Stance
As of press time, the Office of the Comptroller of the Currency had not immediately responded to requests for comment from financial news outlets regarding the specifics of the active litigation. However, the agency’s historical and rulemaking posture maintains that its guidance is fully consistent with the National Bank Act and provides necessary clarity for evolving market participants.
Broader Implications for the Financial Sector
The outcome of ICBA v. OCC could redefine the boundaries of American banking regulation for decades to come, carrying profound implications for fintechs, cryptocurrency businesses, community banks, and federal regulators alike.
1. The Future of Fintech and Crypto Regulation
If the federal courts side with the ICBA and strike down the OCC’s rule and Interpretive Letter No. 1176, digital asset firms and non-bank fintechs seeking federal banking integration will face a major roadblock. They would likely be forced to pursue traditional, full-service banking charters—complete with all associated compliance costs, capital requirements, and CRA mandates—or rely exclusively on state-level chartering frameworks (such as New York’s BitLicense or state trust company charters). This would effectively slam shut what critics label a regulatory workaround.
Conversely, if the OCC prevails, it will validate a more flexible, agency-driven approach to chartering specialized financial institutions. This could encourage further migration of digital asset activities into the federal regulatory perimeter under tailored oversight frameworks, potentially accelerating institutional adoption of blockchain and crypto-financial products.
2. Competitive Equity for Community Banks
Community banks have long complained that they face disproportionate regulatory and compliance burdens compared to non-bank competitors and specialized tech-driven entities. A victory for the ICBA would reinforce the principle of "same activity, same risk, same regulation," helping to level the playing field. It would assure traditional community lenders that federal regulators cannot unilaterally carve out preferential licensing pathways for well-funded technology startups.
3. Judicial Scrutiny of Agency Authority
Beyond banking policy, the lawsuit fits into a broader national conversation regarding administrative law and the limits of federal agency discretion. As courts increasingly scrutinize executive agency rulemaking under modern interpretations of statutory authority, the judiciary’s review of the OCC’s powers under the National Bank Act will serve as an important test case for how far financial regulators can go in adapting century-old banking statutes to modern digital innovations.
As the litigation proceeds through the federal court system, financial services leaders, legal experts, and policymakers will be watching closely to see how the judiciary balances the imperatives of financial innovation against the statutory guardrails of traditional American banking law.