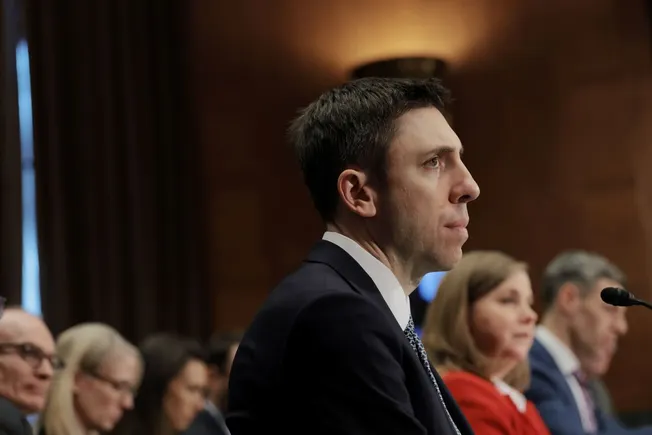
In a significant move to reshape the landscape of American banking oversight, the Federal Deposit Insurance Corporation (FDIC) has introduced a comprehensive proposal aimed at streamlining the notoriously cumbersome bank merger application process. Led by Chairman Travis Hill, the agency’s latest initiative seeks to inject speed, predictability, and logical consistency into a regulatory framework that industry leaders have long criticized as antiquated and unnecessarily restrictive.
The proposal, unveiled this past Thursday, marks the culmination of a strategic shift Hill initiated shortly after taking the helm of the agency in January 2025. By targeting the bureaucratic bottlenecks that have historically plagued consolidation efforts, the FDIC is signaling a departure from previous eras of oversight, prioritizing institutional efficiency and market competitiveness over the "artificial constraints" that many argue have hampered the U.S. banking sector.
The Core Objectives of the FDIC Reform
At the heart of the FDIC’s proposal is the desire to replace what many critics call a "black box" review process with a transparent, risk-based approach. The agency aims to fundamentally reform how it evaluates merger applications, moving away from a one-size-fits-all model toward a framework that scales requirements based on the size and risk profile of the institutions involved.
Chairman Hill has been vocal about the damage caused by prolonged regulatory uncertainty. "A long process is damaging in many ways," Hill stated. "It creates uncertainty for employees and customers, it constrains long-term planning and investment, it makes post-merger integration more challenging and costly, and it potentially leaves the merging entities in a vulnerable position."
Under the proposed rules, the FDIC would establish clearer parameters for its review process, including stricter limitations on its own authority to remove an application from expedited processing. Furthermore, the agency intends to implement a "before-and-after" analytical requirement that will specifically assess how a proposed merger might bolster financial stability, shifting the focus toward the long-term health of the surviving entity.
Chronology: From Strategy to Proposal
The path to this week’s announcement began in the early days of 2025. Upon assuming his role, Chairman Hill identified 15 key priorities for the agency, with the modernization of the merger review process sitting near the top of the list.
- January 2025: Chairman Hill establishes the modernization of merger reviews as a primary strategic pillar for the FDIC.
- 2023–2024 (The Baseline): During this period, the FDIC averaged 107 days from the receipt of an application to a final regulatory decision.
- 2025–2026 (The Shift): Through internal process improvements, the FDIC reduced the average turnaround time to 64 days year-to-date, providing empirical evidence that a faster process is operationally feasible.
- Thursday, [Current Date]: The FDIC officially releases its proposed rule to comprehensively reform the framework, opening a 60-day public comment period.
This steady acceleration of the application pipeline suggests that the agency has been testing these efficiencies internally before codifying them into law, a strategy designed to build institutional confidence in the faster timelines.
Supporting Data: The Case for Efficiency
The data provided by the FDIC serves as a powerful argument for the necessity of these reforms. By dropping the average review time from 107 days to 64 days in less than two years, the agency has demonstrated that the "bottlenecks" were largely procedural rather than substantive.
The proposed rules are not merely about speed, however; they are about sophistication. By requiring a structured comparison of financial stability, the FDIC is moving toward a quantitative-heavy evaluation that allows regulators to justify approvals or denials based on empirical outcomes rather than abstract policy preferences. This shift is designed to align the agency with the current reality of a digital-first, fast-moving financial sector, where capital requirements and competitive dynamics evolve far more quickly than traditional regulatory cycles.
Official Responses and Industry Perspectives
The banking industry has reacted to the news with a mix of cautious optimism and strategic pragmatism. Randy Benjenk, a partner at the law firm Covington & Burling, highlighted that the proposal addresses long-standing requests from the industry, particularly the need for a more realistic assessment of competitive landscapes.
"The industry is looking for a realistic look at who actually competes with banks in local markets," Benjenk noted, suggesting that the FDIC’s acknowledgment of modern banking realities is a welcome change.
However, the industry remains wary of the "silo" effect of the U.S. regulatory system. Because most significant bank mergers require the approval of the Federal Reserve—which typically follows a much more rigorous and time-consuming review process—the FDIC’s improvements may be tempered by the Fed’s timeline. "Unless the Fed adopts parallel reforms, the FDIC’s changes will not shorten transaction times by that much," Benjenk cautioned.
Despite this, Benjenk pointed out that for "housekeeping" transactions—such as internal corporate reorganizations—the FDIC’s faster turnaround could provide immediate, tangible relief. These smaller, non-public restructurings are often held up by administrative hurdles; a faster path would allow institutions to clean up their corporate structures, which in turn improves operational agility.
Implications for Market Dynamics and State Parity
Beyond merger reviews, the FDIC’s simultaneous proposal regarding state-chartered bank parity represents a significant step toward modernizing the dual banking system.
As digital banking has evolved, the distinction between a "local" bank and an "out-of-state" competitor has blurred. In the current environment, state-chartered banks frequently serve customers across state lines without maintaining a physical branch network. This has led to legal confusion regarding which state laws apply to these digital interactions.
The FDIC’s proposal aims to ensure that if a specific state law does not apply to a national bank, it should not apply to an out-of-state chartered bank either, regardless of whether that bank has a physical retail presence. Hill described this as a necessary step to prevent "competitive imbalance" and to ensure that regulation reflects the realities of modern, non-branch financial services.
Strategic Implications
- Increased M&A Activity: If these rules are adopted, the decreased regulatory risk and shorter timelines could encourage mid-sized banks to seek mergers that were previously deemed "too slow" or "too uncertain."
- Increased Focus on Compliance: By making the review process more transparent, the FDIC is effectively shifting the burden of proof back to the banks to demonstrate their financial stability and competitive benefits. Banks that can clearly articulate their case will likely find the process much easier to navigate.
- Pressure on the Federal Reserve: The FDIC’s move creates a de facto competitive pressure on the Federal Reserve to evaluate its own, often slower, merger review process. If the FDIC can maintain a 64-day average, the Fed will face increasing scrutiny from lawmakers and the industry to explain why its own timelines remain significantly longer.
- Modernizing the Dual Banking System: By clarifying the rules on state-chartered bank parity, the FDIC is signaling that the regulatory environment must be "technology-neutral." This is a major win for fintech-forward regional banks that have struggled with the fragmented nature of state-by-state regulation.
Conclusion: A New Era of Oversight?
Chairman Hill’s vision for the FDIC is clear: the regulator should be a facilitator of a robust, competitive, and stable banking system rather than a gatekeeper that imposes artificial constraints. By combining faster merger reviews with a clearer mandate on regulatory parity, the FDIC is positioning itself as a leader in the modernization of the U.S. financial system.
Whether these reforms can survive the transition from proposal to finalized rule depends on the feedback received during the upcoming 60-day comment period. However, the intent is unmistakable. The agency is moving to align its framework with the 21st-century realities of global finance, where time-to-market and regulatory certainty are as vital to a bank’s health as its capital ratios.
For the banking sector, the next few months will be a period of careful observation. If the FDIC successfully implements these changes, the U.S. banking industry may see a surge in strategic consolidation, driven by institutions finally able to plan for the future without the specter of years-long regulatory limbo. The ball is now firmly in the court of the industry to provide the feedback needed to finalize these potentially transformative rules.