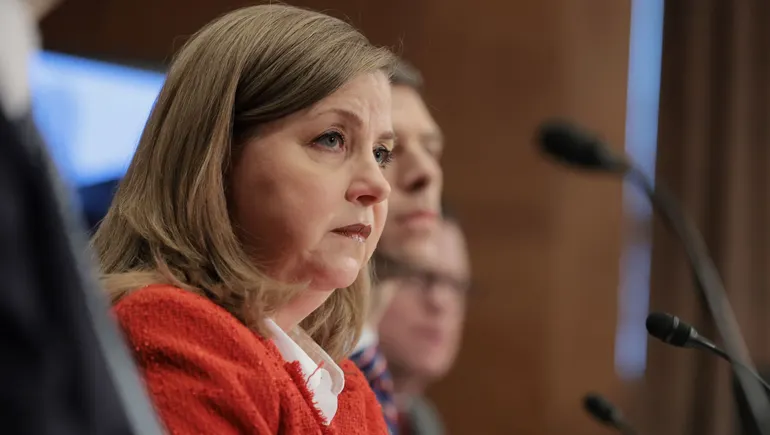
In a significant address delivered at a London luncheon this past Friday, Federal Reserve Governor Michelle Bowman outlined a transformative vision for the future of bank supervision and stress testing. Her remarks, which synthesized upcoming policy revisions with a sobering retrospective analysis of the Silicon Valley Bank (SVB) collapse, signaled a shift toward a more transparent, diagnostic, and proactive regulatory framework.
As the Federal Reserve navigates a complex landscape of legal challenges and post-crisis introspection, Bowman’s comments provide the clearest roadmap yet for how the central bank intends to refine the tools used to measure the health of the nation’s largest financial institutions.
I. Main Facts: A Pivot Toward Transparency
At the heart of Bowman’s message is a commitment to ending what she termed an "opaque and unnecessarily unpredictable" regulatory environment. Her speech focused on three primary pillars: the impending finalization of stress testing frameworks, the integration of new risk-modeling methodologies, and a structural critique of the supervisory failures that preceded the 2023 banking crisis.
Governor Bowman confirmed that the Federal Reserve is currently in the "final stages" of revising its stress-testing framework, with finalized rules expected to be released in the coming weeks. These updates are poised to impact not only the annual stress tests themselves but also broader risk-based capital requirements and the surcharges applied to global systemically important banks (G-SIBs).
However, these efforts are occurring against a backdrop of mounting friction. The Federal Reserve is currently navigating a lawsuit filed by the advocacy group Better Markets, which alleges that the Fed’s process regarding proposed capital requirements lacks the necessary transparency and that meetings between regulators and bank CEOs have potentially compromised the integrity of the rulemaking process. Despite this legal pressure, Bowman emphasized that the focus remains on closing the book on an outdated era of supervision.
II. Chronology of Regulatory Evolution
The path to these reforms has been paved by years of evolving financial conditions and a series of high-profile supervisory failures.
- March 2023: The collapse of Silicon Valley Bank (SVB) sends shockwaves through global financial markets, exposing significant gaps in regulatory oversight and risk assessment.
- Late 2023 – Early 2024: The Federal Reserve initiates a series of internal and independent reviews to identify why supervisors failed to intervene as SVB’s interest rate risk mounted.
- March 2025: The Fed proposes new capital-requirement changes, sparking immediate debate among industry stakeholders and consumer advocacy groups.
- September 2026 (Last Week): An advocacy group files a lawsuit against the Fed and Governor Bowman, alleging procedural improprieties in the rulemaking process.
- Friday, September 18, 2026: Governor Bowman delivers her London address, confirming that the Fed will finalize stress test reforms in the coming weeks and laying the groundwork for a revamped 2027 testing cycle.
III. Supporting Data: Reforming the Stress Test Mechanics
Bowman’s proposals for the stress test go beyond mere administrative changes; they represent a fundamental rethink of how the Fed models bank performance.
Proposed Operational Shifts
One of the most notable proposals involves a "frozen balance sheet" approach. Under current rules, banks are tested against a variety of hypothetical macroeconomic scenarios, but the fluidity of balance sheets can sometimes mask the impact of those shocks. By implementing a specific date on which balance sheets are frozen for the duration of the test, the Fed aims to provide a clearer, more static picture of institutional vulnerability.
Enhancing Market Shock Scenarios
Furthermore, Bowman is considering a two-pronged "global market shock" model. Under this proposal, the Fed would run two distinct scenarios for market volatility, with the institution’s stress capital buffer determined by the scenario that yields the higher loss. This "worst-case-first" approach is designed to ensure that capital buffers are truly sufficient to withstand tail-risk events.
The 2027 Noninterest Income Model
Looking further ahead, Bowman announced that the Fed is soliciting public comment on a new model to evaluate noninterest income. As banks increasingly rely on fee-based revenue—such as wealth management, investment banking, and market making—the volatility of these income streams has become a critical variable in bank stability. Refining the modeling of these revenues is a priority for the 2027 testing cycle.
IV. Official Responses and Supervisory Critique
Perhaps the most striking portion of Bowman’s speech was her unvarnished assessment of the Fed’s own role in the 2023 SVB crisis. She argued that the catastrophe was not a result of "unforeseeable" market forces, but rather a failure of existing supervisory mechanisms.
The Failure of Intervention
According to Bowman, the Fed’s supervisory staff was aware, or should have been aware, of SVB’s precarious position as early as March 2022. Despite this, "the central bank’s supervisory staff did not take prompt, decisive action to encourage or require SVB to reduce its interest rate risk or concentration of vulnerabilities."
The "Culture of Risk Aversion"
Bowman pointed to an internal culture of hesitation at the Federal Reserve. She noted that staff members often operated under the belief that taking no action was safer than taking the "wrong" action—a phenomenon that led to systemic paralysis. Furthermore, she highlighted a lack of clear accountability, where supervisory staff members were often unclear on who possessed the final authority to mandate corrective actions for failing firms.
"The Fed’s stress tests should do more for our supervisors than calculate a single capital requirement," Bowman asserted. "They should identify a firm’s vulnerability to various material financial and nonfinancial risks before those risks emerge."
V. Implications for the Banking Industry
The implications of Bowman’s proposed reforms are profound for the banking sector, both in terms of compliance and operational strategy.
Increased Communication
Bowman advocated for moving away from a "one-way exercise" model. By encouraging more robust dialogue between the Fed and the institutions it supervises, she hopes to turn stress testing into a collaborative diagnostic tool rather than a punitive exam. This approach acknowledges that large banks often possess a more granular understanding of their own internal risks than external regulators.
Strengthening Market Confidence
The broader implication of these reforms is a concerted effort to restore public confidence in the US banking system. Bowman acknowledged that the SVB collapse "fundamentally shook public confidence in the effectiveness of bank supervision." Her promise to use these lessons to avoid future repetition is a signal to investors and the public that the Fed is moving toward a more rigorous, accountability-based framework.
The Challenge of Implementation
While the industry generally welcomes more transparency, the path to implementation remains fraught. Banks must now prepare for a more rigorous testing environment that is less predictable in its volatility modeling but more predictable in its regulatory standards. The ongoing litigation by Better Markets also suggests that any final rule will face intense scrutiny, with the Fed needing to demonstrate that its rulemaking process is both robust and impartial.
Conclusion
As Governor Bowman concluded, the goal of these reforms is not to assign blame for past errors, but to learn from them. By tightening the mechanics of stress tests, addressing the cultural stagnation within the supervisory ranks, and embracing a more transparent dialogue with the institutions they regulate, the Federal Reserve is attempting to fortify the banking system against the next inevitable cycle of economic stress. For the nation’s large banks, the next few weeks will be a critical period of adjustment as the "final book" on the current supervisory framework is closed and a new, more diagnostic chapter begins.