By PYMNTS
October 7, 2026
Main Facts: The Current State of the Artificial Intelligence Buildout
The global artificial intelligence (AI) infrastructure buildout remains firmly in its early-to-middle stages, according to a comprehensive market analysis released Wednesday (Oct. 7) by Citi Wealth. However, this unprecedented technological expansion is navigating a more complex macroeconomic and regulatory environment than it did during its initial breakout phase.
As enterprises, hyperscalers, and governments pour hundreds of billions of dollars into compute power, data centers, and specialized silicon, the broader AI investment cycle is facing intense scrutiny. According to Citi Wealth’s latest quarterly report, several compounding factors are forcing a more rigorous evaluation of AI projects:
- Higher interest rates: Sustained elevated borrowing costs globally have raised the hurdle rate for capital-intensive technology projects.
- Open-weight model proliferation: The rapid emergence of highly capable open-weight models is changing the competitive landscape, challenging proprietary software moats.
- Regulatory pressures: Global policymakers are increasingly scrutinizing data privacy, anti-competitive market concentration, and the societal impacts of advanced generative AI systems.
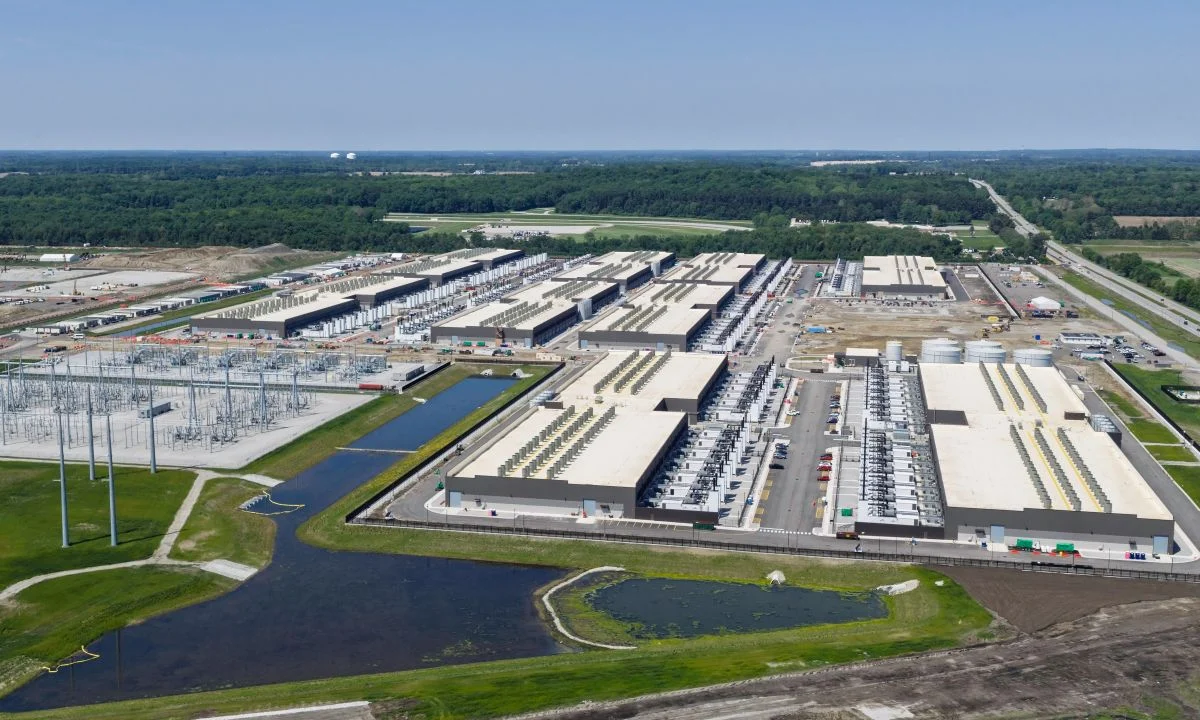
- Escalating infrastructure costs: Constructing, powering, and cooling next-generation AI data centers requires staggering capital outlays, putting pressure on corporate balance sheets.
Despite this "growing noise" and mounting market skepticism, Citi Wealth emphasizes that foundational economic indicators supporting the AI ecosystem remain remarkably robust. Core semiconductor demand continues to aggressively outpace near-term supply chains. Furthermore, U.S. core capital goods orders registered solid growth through the first half of the year, while AI-related exports remain a primary growth engine for export-heavy economies like South Korea and Taiwan.
"We continue to favor diversified semiconductor exposure as a core holding and a key pillar of our U.S. large cap overweight," Citi Wealth noted in the report. "We also favor hyperscalers, which enter the next phase from a position of strength. Their vertical integration across large language models (LLMs), compute infrastructure (data centers) and chips strengthen their competitive advantage."
Chronology: The Evolution of the AI Investment Boom and Its Critics
To understand where the market stands in October 2026, it is vital to trace the rapid escalation of the AI capital expenditure cycle and the corresponding rise in regulatory and institutional warnings:
- Late 2022 – 2023 (The Generative AI Inflection): The public launch of breakthrough generative AI models triggers a historic rush for enterprise compute power. Tech giants and specialized startups initiate massive capital expenditure programs to secure graphics processing units (GPUs) and specialized tensor chips.
- 2024 – 2025 (The Infrastructure Scramble): Supply chain bottlenecks dominate headlines. Demand for high-bandwidth memory (HBM) and advanced packaging outstrips global manufacturing capacity, leading to soaring profit margins for key hardware suppliers like Nvidia, Taiwan Semiconductor Manufacturing Company (TSMC), and Samsung Electronics.
- July 2026 (Institutional Warnings Emerge):
- The Bank for International Settlements (BIS) releases a stern warning cautioning that excessive, debt-fueled AI investment risks creating an unsustainable market bubble. The BIS compares the current trajectory to historical technology booms that ultimately "ended in sharp corrections" with severe economic fallout.
- The U.S. Department of the Treasury drafts an internal report—leaked to media outlet NOTUS—warning that a potential AI market collapse could trigger macroeconomic shockwaves reminiscent of the dot-com bubble crash a quarter-century prior.
- October 7, 2026 (Citi Wealth Q4 Report): Citi Wealth publishes its fourth-quarter strategy document, acknowledging rising structural scrutiny while reassuring investors that underlying demand for hardware and cloud infrastructure remains fundamentally sound.
- October 8, 2026 (Samsung Earnings Anticipation): Financial markets anxiously await preliminary third-quarter earnings reports from Samsung Electronics to gauge whether memory chip pricing momentum is finally peaking or if the AI spending spree retains its durability.
Supporting Data: Semiconductor Demand, Supply Constraints, and Macro Signals
The debate over the sustainability of the AI boom hinges on hard economic and operational data. While skeptics point to the immense capital expenditures required to train and run massive foundation models, optimists look to persistent supply-demand imbalances in the semiconductor supply chain.
1. Semiconductor Demand vs. Supply
Global demand for specialized AI hardware—including advanced accelerators, high-performance networking gear, and high-bandwidth memory (HBM)—continues to outstrip production capacity. While manufacturing yields have improved across major foundries, lead times for enterprise-grade AI clusters remain extended. However, recent indicators point to a slight cooling in the rate of price increases for certain memory products during the third quarter of 2026, sparking intense debate among Wall Street analysts over whether profit margins for memory chipmakers have peaked.
2. Macroeconomic Indicators
- U.S. Core Capital Goods Orders: Orders for non-defense capital goods excluding aircraft—a primary proxy for business capital investment—posted healthy gains through the first half of 2026, signaling that enterprise digital transformation spending has not ground to a halt despite higher macroeconomic hurdles.
- Asia-Pacific Export Engines: Economies heavily reliant on high-tech manufacturing, particularly South Korea and Taiwan, continue to ride a wave of AI-driven export demand. Semiconductor shipments remain the primary driver of industrial production growth in these regions.
Official Responses and Industry Perspectives
Financial institutions, international regulatory bodies, and major technology stakeholders hold widely divergent views on the long-term trajectory of the AI market.
Citi Wealth: Positioned for Strength
Citi Wealth maintains an optimistic yet pragmatic view of the tech sector. By favoring diversified semiconductor exposure and integrated hyperscalers, the bank argues that the market leaders possess the balance sheet strength and operational moats necessary to weather a tightening credit cycle. Because hyperscalers control the entire stack—from foundational LLMs and proprietary silicon to hyperscale data centers—they are uniquely positioned to monetize AI deployments effectively.
The Bank for International Settlements (BIS) and the U.S. Treasury: Cautionary Notes
In stark contrast to commercial wealth managers, policy-focused institutions have raised alarms regarding systemic financial risk.
- The BIS report released in July emphasized that the sheer volume of capital being funneled into physical AI infrastructure carries inherent risk. If enterprise adoption fails to generate sufficient return on investment (ROI) to justify multi-billion-dollar data center builds, lenders and investors could face severe write-downs.
- The U.S. Treasury’s internal findings, as reported by NOTUS, highlighted the danger of speculative overbuilding. Regulators are increasingly concerned that interconnected financial markets could transmit localized tech sector corrections into the broader banking and lending ecosystem.
Implications: What the Future Holds for Markets and Enterprises
As the AI buildout transitions from its initial gold-rush phase into a more mature, highly scrutinized infrastructure cycle, several critical implications emerge for investors, enterprises, and policymakers:
1. Shift Toward Proven ROI and Vertical Integration
For enterprise buyers, the era of experimenting with AI simply for the sake of adoption is coming to a close. Chief Information Officers (CIOs) are now demanding clear, quantifiable business value, productivity gains, and cost efficiencies. Consequently, tech providers that offer tightly integrated solutions—combining secure infrastructure, domain-specific models, and seamless enterprise software integration—will capture market share at the expense of point-solution vendors.
2. Margin Pressures and Valuation Discipline
For public market investors, the days of indiscriminate tech stock rallies are fading. As demonstrated by the intense market focus on Samsung’s upcoming earnings and memory chip pricing trends, Wall Street is demanding granular visibility into corporate margins. Companies that fail to demonstrate sustainable earnings growth commensurate with their capital expenditures risk severe valuation corrections.
3. Regulatory and Geopolitical Realities
With regulatory scrutiny intensifying across North America, Europe, and Asia, compliance will become a major operational cost for AI developers. Issues surrounding intellectual property, data sovereignty, and energy consumption (particularly the immense power grid demands of modern AI data centers) will heavily influence where and how infrastructure is deployed in the years leading toward 2027 and beyond.
Ultimately, the AI supercycle is entering a crucible of financial and operational maturity. While institutional watchdogs warn of speculative excess and systemic debt risks, major financial institutions like Citi Wealth assert that the underlying economic foundations—anchored by indispensable silicon and hyperscale infrastructure—remain fundamentally sound. Navigating this landscape will require acute risk management, strict valuation discipline, and a sharp focus on real-world utility over speculative hype.