For many Physician Assistants (PAs), stepping out of the clinical training environment and into the workforce brings an unexpected companion: crippling educational debt. Earning a respectable six-figure salary feels like a monumental achievement until it is juxtaposed against a lingering balance of $150,000 to $200,000 in student loans. This financial reality plunges many PAs into what financial experts call "loan repayment purgatory"—a state of indecision where choosing the right repayment strategy becomes a complex, high-stakes guessing game.
Main Facts: The PA Debt Dilemma
The fundamental challenge for modern PAs lies in the friction between their income and their debt load. While a standard 10-year repayment plan offers a definitive path to debt freedom, the monthly payments can strain a newly minted clinician’s budget. Conversely, income-driven repayment (IDR) plans lower the monthly barrier to entry, but they typically stretch timelines, elevate overall interest accumulation, and can result in significant long-term costs.
Caught between these extremes, many PAs resort to a dangerous "murky middle" strategy: enrolling in an income-driven plan while haphazardly throwing extra cash at the principal whenever possible. According to financial analysis, this compromise is often the costliest path of all. Borrowers risk paying off the entire principal balance before any forgiveness can take effect, effectively neutralizing the benefits of IDR while still shouldering years of accumulated interest and administrative hurdles.
Chronology and Evolution of Repayment Options
Understanding how to tackle PA school debt requires looking at the historical and structural evolution of federal and private repayment frameworks.
- The Early Career Phase (Years 1–2): Graduates typically face a grace period followed by the immediate pressure of selecting a repayment vehicle. With starting salaries averaging around $100,000 and debt burdens often scaling past $170,000, the initial choice dictates cash flow for the next decade or more.
- The Policy Landscape (Present–2026): Regulatory shifts, such as targeted updates to federal loan consolidation and temporary flexibilities for older loan types (like FFEL, Perkins, and Parent PLUS loans), have changed the calculus. Notably, the deadline for specific consolidation advantages—such as retaining access to the Income-Contingent Repayment (ICR) plan for Parent PLUS loans—arrives on June 30, 2026. Failing to navigate these administrative windows can permanently shut the door on valuable forgiveness pathways.
- The Long-Term Horizon (Years 10–25): Depending on whether a borrower chooses aggressive refinancing or a 20-to-25-year forgiveness track, the financial journey culminates either in mid-career debt freedom or a potential "tax bomb" when forgiven balances are treated as taxable income.
Supporting Data: A Case Study in Real Numbers
To understand the mathematical reality behind these choices, consider the profile of "Kristin," a composite example representative of many modern PA graduates:
- Age: 26
- Time Since Graduation: 1 year
- Total Student Loan Debt: $170,000 at a 6.5% interest rate
- Current Annual Salary: $100,000
When comparing an aggressive refinancing approach against a passive Income-Based Repayment (IBR) strategy, the numbers reveal striking trade-offs:
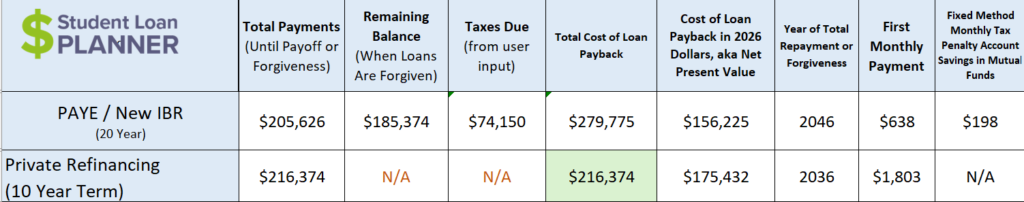
1. The Refinancing Route (Aggressive Paydown)
- Monthly Payment: ~$1,803 for 10 years
- Total Out-of-Pocket Cost: ~$216,374
- Timeline: Debt-free in 10 years.
- Trade-off: Higher monthly strain on the budget, but zero lingering debt and minimal total interest paid.
2. The IBR Route (Passive / Forgiveness Track)
- Starting Monthly Payment: ~$638
- Timeline: 20 years to forgiveness.
- Projected Forgiven Balance: ~$185,374
- The "Tax Bomb": Assuming a 20-year tax rate of 40%, the forgiven balance generates a tax liability of ~$74,150.
- Total Out-of-Pocket Cost: ~$279,775 (approximately $63,400 more expensive than refinancing overall, despite lower initial payments).
3. The Public Service Loan Forgiveness (PSLF) Alternative
If Kristin secures full-time employment at a 501(c)(3) non-profit hospital or government entity, she may qualify for PSLF.
- Outcome: Remaining balances are forgiven tax-free after 10 years (120 qualifying payments).
- Total Cost Comparison: PSLF can reduce the total cost of education by roughly 60% compared to private refinancing over the same window, saving her nearly $129,000.
- The Opportunity Cost: Non-profit positions sometimes offer lower base salaries than private practices. However, calculations show that a private employer would need to offer a pre-tax salary roughly $20,000 higher just to offset the massive tax-free savings provided by PSLF.
Official Guidelines: Choosing Your Path
Financial planners generally categorize optimal repayment strategies using a debt-to-income (DTI) ratio benchmark:
- The Aggressive Approach (1.5x DTI Ratio or Lower): Borrowers whose debt is roughly 1.5 times their annual income are often best served by refinancing to the lowest possible interest rate and aggressively paying down the balance within 10 years. Note that refinancing federal loans into private loans strips away federal protections, income-driven options, and public forgiveness eligibility, requiring strong credit and a stable debt-to-income profile.
- The Passive / Forgiveness Approach (2.0x DTI Ratio or Higher): Borrowers facing debt loads double their income or higher typically benefit from maximizing federal IDR plans or pursuing Public Service Loan Forgiveness.
- The Danger Zone: PAs whose ratios sit awkwardly in the middle face the hardest decisions, as moderate compromises often result in paying tens of thousands of dollars more to financial institutions than necessary.
Implications for the Future of the PA Workforce
The burden of educational debt extends far beyond individual balance sheets; it has systemic implications for the healthcare labor market. When PAs are forced to weigh loan repayment structures against career choices, financial survival can steer them away from high-need rural clinics, non-profit community health centers, or public hospitals in favor of higher-paying private sector roles.
Conversely, awareness and proper navigation of programs like PSLF and strategic IDR enrollment can empower clinicians to pursue mission-driven healthcare without sacrificing their financial futures. As lending regulations, tax codes, and forgiveness programs continue to evolve, proactive planning and expert consultation remain the most reliable shields against the hidden traps of student loan purgatory.