WASHINGTON — For millions of prospective homebuyers, real estate investors, and industry professionals, the persistent hope has been that the American housing market is merely enduring a temporary rough patch—a cyclical speed bump that will soon give way to historical norms.
According to comprehensive financial modeling and housing market data, however, that expectation is largely a delusion. The U.S. housing market is not returning to "normal" anytime soon. In fact, a deep-dive analysis into the three pillars of housing affordability—mortgage rates, home prices, and wage growth—reveals that a return to historically healthy affordability metrics could take anywhere from half a decade to multiple generations, barring a severe economic catastrophe.
The Main Facts: The Affordability Crisis Explained
The root cause of the current sluggish, high-friction housing market is simple: a profound collapse in housing affordability.
To measure this, analysts look at the payment-to-income ratio, which compares a homebuyer’s monthly mortgage payment to their gross income. Historically, looking at data stretching from 1989 to the present, Americans have spent an average of 18.5% of their gross income on mortgage payments. Back in 2019—the last truly stable, functioning housing market before pandemic-era disruptions—that figure sat even lower, at roughly 15.5%.
Today, that metric has skyrocketed. Driven by mortgage rates hovering around 7.5% and a national median home price near $446,000, the average payment-to-income ratio has surged to approximately 24.5% (and approaches 27% when accounting for peak interest rate environments).
The divergence between earnings and housing costs over the last half-decade underscores the depth of the crisis:
- Home Prices: Up an average of 63% since 2019.
- Family Incomes: Up only 37% over the same period.
- Monthly Mortgage Payments: Up a staggering 116%—more than doubling in just a few years.
Chronology: How the Market Reached This Impasse
To understand how the housing market arrived at its current state of paralysis, it is necessary to examine the timeline of economic shifts over the past several decades:
- The Pre-2008 Era & Historical Norms: For decades, the housing market operated within a predictable band where the average mortgage consumed less than one-fifth of a household’s gross earnings. Interest rates followed broader macroeconomic cycles, but borrowing costs remained manageable.
- The 2010s Recovery: Following the Great Financial Crisis, the Federal Reserve maintained near-zero interest rate policies for years. This era birthed an extended period of relative housing stability, culminating in 2019 as a balanced market where affordability remained favorable.
- The Pandemic Boom (2020–2022): Unprecedented fiscal stimulus, remote work migrations, and rock-bottom mortgage rates (touching historic lows near 3%) triggered a historic surge in demand. Home prices spiked aggressively, far outpacing historical appreciation rates.
- The Rate Shock (2022–Present): To combat runaway inflation that peaked near 9%, the Federal Reserve aggressively hiked the federal funds rate. Mortgage rates more than doubled, jumping from historic lows into the 7% range. While home price growth cooled in nominal terms and turned flat to negative when adjusted for inflation, high borrowing costs effectively locked the market in place.
Supporting Data: Testing the Three Levers of Affordability
Housing affordability is a three-legged stool composed of wages, mortgage rates, and home prices. To understand when the market might recover, analysts must isolate each lever while holding the other two constant. The mathematical realities of each scenario reveal why a quick fix is mathematically impossible.
1. The Wage Growth Scenario
If mortgage rates and home prices remain completely flat, how much would incomes need to rise to restore historical affordability?
- To reach the long-term average (18.5% payment-to-income ratio), real wages would need to jump 33%.
- To return to 2019 affordability levels (15.5%), real wages would need to surge 57%.
The Reality: Historical data shows that since 1968, real (inflation-adjusted) median wage growth has averaged a meager 0.8% per year. Achieving a 57% increase purely through historical wage growth would take 59 years. Furthermore, real wage growth has recently turned negative as inflation outpaces average pay raises, and the rise of automation and artificial intelligence threatens high-paying white-collar sectors. Wage growth will not bail out the housing market.
2. The Mortgage Rate Scenario
If home prices and wages remain stable, how low must mortgage rates fall to restore affordability?
- To return to the long-term average affordability, mortgage rates would need to drop to 4.0%.
- To return to 2019 affordability levels, mortgage rates would need to plummet to an improbable 2.7%.
The Reality: While borrowing costs in the 2s and 3s were celebrated during the pandemic, analysts point out that those rates were an anomaly born of zero-interest-rate policy emergencies. Because mortgage rates track the bond market—which is heavily dictated by inflation—getting back to 4% mortgage rates requires core inflation to drop well below the Federal Reserve’s 2% target, potentially down to 1%. While rates may ease down toward the high 5% range in an optimistic future, a return to sub-3% or even 4% rates is exceptionally unlikely barring an extreme economic crisis.
3. The Home Price Crash Scenario
If wages and mortgage rates remain at current levels, how far would home prices have to fall to restore balance?
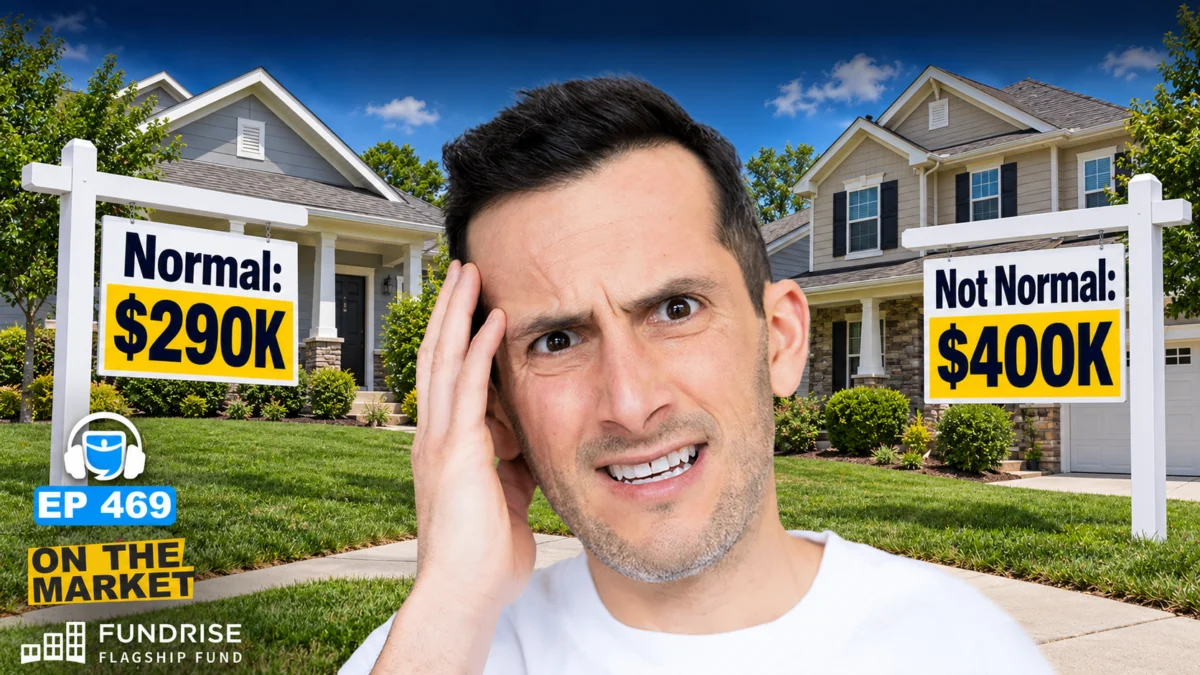
- To hit the long-term affordability average, home prices would need to crash 25% (bringing the national median price from roughly $446,000 down to $335,000).
- To hit 2019 affordability levels, prices would need to collapse 36% (down to roughly $284,000).
The Reality: The largest national home price crash in modern history occurred during the Great Financial Crisis of 2007–2008, when prices dropped roughly 20% to 22% amid rampant financial speculation, loose lending standards, and forced liquidations.
Today’s market fundamentals are fundamentally different. Crucially, the market is insulated by the "lock-in effect." Roughly 80% of existing mortgages feature interest rates below 6%, 50% are below 4%, and 20% are below 3%. Homeowners have immense equity and zero financial incentive to sell and trade their ultra-low mortgage for a 7.5% loan. Consequently, inventory remains constrained, distress rates (foreclosures and delinquencies) are historically low, and a sweeping 35% national price crash is mathematically and structurally improbable.
Official Perspectives and Industry Implications
Industry analysts, real estate economists, and housing market experts broadly agree that because no single lever can fix the market in isolation, recovery will require a slow, multi-year combination of modest wage growth, slight price corrections, and gradual interest rate stabilization.
The Combined Outlook
When running models that combine realistic improvements—such as mortgage rates easing to 6%, annual wage growth stabilizing at 2% above inflation, and home prices experiencing a controlled, prolonged correction of 2% annually—financial models indicate it will still take approximately five to seven years for the national housing market to return to healthy affordability metrics.
Implications for Homebuyers, Sellers, and Investors
- For Transaction Volume: Real estate agents, loan officers, and title companies face a sustained period of low transaction volume. Until affordability meaningfully improves, market velocity will remain sluggish.
- For Homebuyers: Waiting passively on the sidelines for a market crash or a return to 3% mortgage rates is a high-risk strategy. Buyers entering the market must adjust expectations regarding monthly expenditures.
- For Real Estate Investors: Appreciation cannot be relied upon as the primary engine for returns over the next several years. Investors must adapt by adopting the classic downturn playbook: securing deep discounts on the buy-side (purchasing 15% to 20% below current market comps) and focusing aggressively on value-add properties to manufacture equity and ensure positive cash flow.
Ultimately, while the math behind the modern housing market is sobering, acknowledging these realities allows buyers, sellers, and investors to navigate the coming years with clear eyes, realistic expectations, and sound financial strategy.