By Financial Desk
Published: June 2026
Main Facts: The Balancing Act Between Premiums and Deductibles
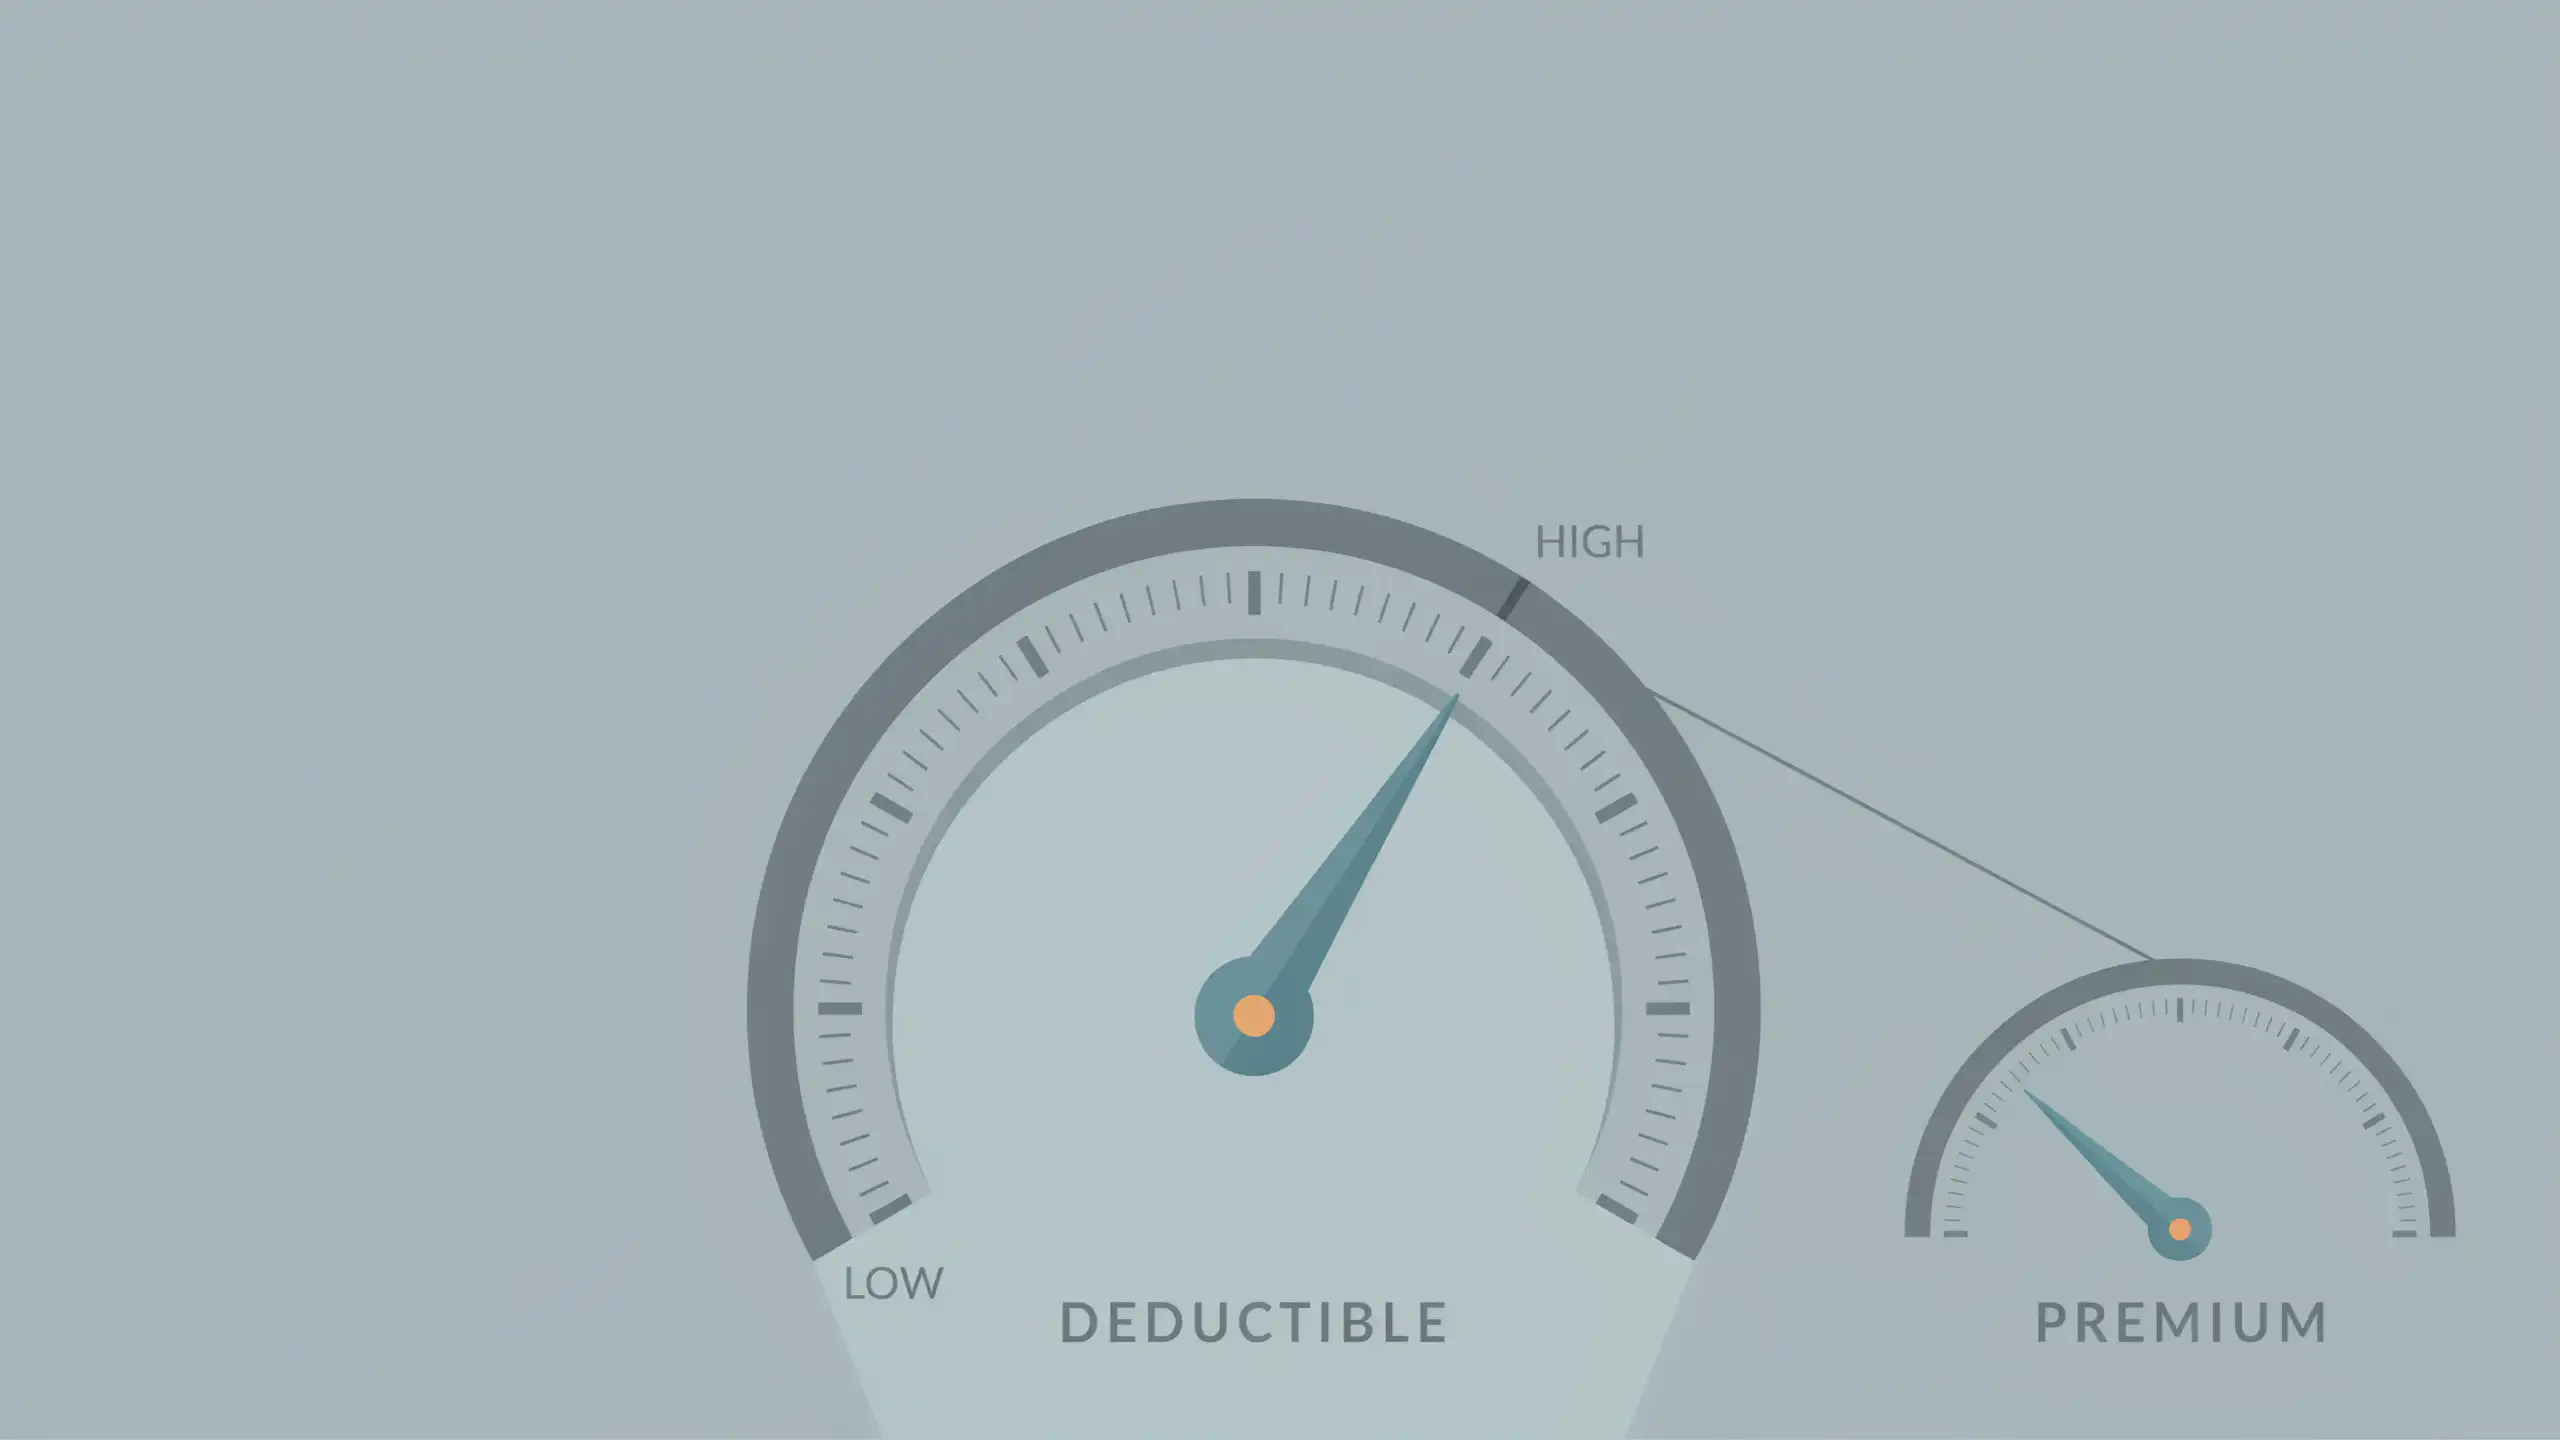
In an era defined by persistent inflation, rising cost-of-living pressures, and soaring insurance rates across both the auto and property markets, consumers are aggressively looking for ways to trim their monthly overhead. One of the most effective—yet frequently misunderstood—levers policyholders can pull is adjusting their insurance deductibles.
Raising auto and homeowners insurance deductibles guarantees immediate, annual reductions in your premium payments. According to industry metrics from organizations like the Insurance Information Institute (III), shifting a collision and comprehensive auto deductible from a modest $200 to $500 can slash the cost of that specific coverage by 15% to 30%. Taking that leap further to a $1,000 deductible can yield savings of 40% or more. Similarly, on the homeowners insurance side, moving from a standard low deductible to a $1,000 threshold can reduce annual property insurance premiums by up to 25%.
However, these guaranteed savings come with a fundamental structural catch: risk displacement. While premium savings accrue incrementally—collected month by month or year by year—the financial obligation of a higher deductible strikes instantaneously on the exact day you file a claim.
Financial advisors and insurance experts universally stress that this strategy should never be treated as a blind shortcut to saving money. Instead, it is a calculated financial trade-off that is entirely dependent on an individual’s liquid cash reserves. If you raise your deductibles without the corresponding emergency fund to back them up, a single stroke of bad luck can instantly force you into high-interest debt, entirely erasing years of cumulative premium savings.
Chronology: Understanding the Lifecycle of an Insurance Claim and Premium Savings
To fully grasp whether raising your deductible makes financial sense, it is critical to look at the timeline of how insurance policies function over a multi-year horizon.
Phase 1: The Decision at Policy Renewal
The lifecycle begins during your annual or semi-annual policy review. Faced with a steep rate hike sent by your carrier, you log into your insurer’s portal or call an agent to explore ways to lower the bill. You examine quotes for shifting your auto comprehensive/collision and homeowners deductibles from $500 to $1,000. You note that the change will drop your combined annual premium by $500.
Phase 2: The Accumulation Period (Years 1 to 3)
For the next three years, you experience no major accidents, storms, or property damage. You faithfully pay your lower monthly or semi-annual premiums. Over this 36-month period, you have successfully banked $1,500 in total premium savings. You feel confident that your strategy is paying off.
Phase 3: The Inciting Incident
In the fourth year, a severe summer storm rolls through your neighborhood. A violent hailstorm pummels your area, denting the body panels and shattering the windshield of your parked car, while simultaneously tearing shingles off your roof. You are suddenly facing two distinct insurance claims: an auto claim and a property claim.
Phase 4: The Financial Reckoning
Because you raised both deductibles to $1,000, you are now required to pay $1,000 out of pocket for the car repairs and another $1,000 out of pocket for the roof repairs before your insurance coverages kick in. Total immediate out-of-pocket cost: $2,000.
When weighed against the $1,500 you saved over the previous three years, you find yourself facing a net deficit of $500 for that single catastrophic afternoon. Had you kept your original $500 deductibles, your immediate out-of-pocket exposure would have been $1,000, leaving you net positive overall. This chronological reality underscores why emergency fund readiness is the single most important factor in the decision-making process.
Supporting Data: The Hard Numbers Behind Deductible Scaling
To help consumers navigate these choices, industry actuaries and consumer finance researchers have compiled extensive data illustrating the relationship between risk retention and cost reduction.
Auto Insurance Breakdown
- $200 Deductible (Baseline): Offers maximum immediate coverage protection in the event of an accident, but commands the highest possible premium rates.
- $500 Deductible: Typically reduces collision and comprehensive coverage costs by 15% to 30%. For a driver paying $1,200 annually for full coverage, this can mean a savings of $180 to $360 per year.
- $1,000 Deductible: Accelerates savings, cutting collision and comprehensive costs by 40% or more. On the same policy, annual savings can easily scale past $480.
Homeowners Insurance Breakdown
- Low/Standard Deductible ($500): Common in older legacy policies, but increasingly rare or expensive in modern underwriting environments.
- Standard Higher Deductible ($1,000): Can reduce the baseline policy premium by up to 25%.
- Percentage-Based Wind/Hail Deductibles: A critical data point often overlooked by policyholders is the presence of specialized deductibles. In hurricane-prone coastal regions or tornado-heavy Midwestern states, insurers frequently mandate percentage-based deductibles for wind, hail, or named tropical storms. Rather than a flat dollar amount (e.g., $1,000), these deductibles range from 1% to 5% of the total insured value of the home. If a home is insured for $400,000, a 2% windstorm deductible means the homeowner is personally responsible for the first $8,000 of damage—completely independent of whatever standard deductible they selected for fire or theft.
Official Responses & Industry Perspectives: What Insurance Carriers and Consumer Advocates Say
Insurance providers and consumer protection agencies hold distinct viewpoints on how policyholders should approach deductible adjustments.
The Insurance Industry Perspective
Major carriers generally support consumers raising their deductibles, viewing it as a mutually beneficial mechanism. From an actuarial standpoint, higher deductibles filter out "attritional" or micro-claims—such as minor bumper scrapes or small property repairs costing slightly more than a low deductible.
Processing a claim involves administrative overhead, adjusting fees, and payout logistics. When policyholders handle minor incidents out of pocket, insurance companies save significantly on operational costs. Furthermore, fewer filed claims mean the policyholder maintains a clean loss history, reducing their statistical likelihood of being flagged as high-risk or facing non-renewal.
Consumer Advocacy and Financial Planning Perspectives
Financial experts and consumer watchdogs, however, urge caution. Organizations like the National Association of Insurance Commissioners (NAIC) emphasize that insurance should fundamentally serve as a backstop against catastrophic financial loss, not as a maintenance account for minor expenses.
Certified Financial Planners (CFPs) routinely advise that no consumer should adjust their insurance metrics based solely on the desire to lower their monthly bills. The consensus advisory rule of thumb is straightforward: Do not raise your auto and homeowners deductibles unless you maintain a fully funded, highly liquid emergency savings account that can comfortably cover both maximum out-of-pocket expenses simultaneously, without forcing you to rely on credit cards, personal loans, or liquidating retirement accounts.
Implications: Strategic Takeaways for Policyholders
As insurance markets continue to experience upward pricing pressure, evaluating your deductible structure is a prudent exercise—provided it is done with eyes wide open to the underlying risks.
- Audit Your Emergency Savings First: Before touching your policy declarations page, look closely at your bank account. If an unexpected $2,000 bill (covering a simultaneous auto and home deductible) would force you to swipe a credit card and accumulate interest, you are financially unready for high deductibles. Maintain lower deductibles until your savings buffer grows.
- Account for Specialized Riders: Never assume a standard $1,000 deductible covers all perils. Review your policy for regional exclusions, such as earthquake, flood, or percentage-based windstorm deductibles, which can dramatically inflate your true out-of-pocket exposure.
- Run the Break-Even Math: Calculate the annual premium savings of moving to a higher deductible and divide it by the difference in out-of-pocket costs to determine how many claim-free years are required to break even. If the break-even window exceeds three to four years, weigh whether the risk aligns with your personal risk tolerance.
- Time Your Review with Policy Renewals: Do not wait for a crisis to evaluate your coverage. Use your annual renewal window to run quotes, speak with your insurance agent, and align your risk parameters with your current financial reality.