By PYMNTS
October 3, 2026
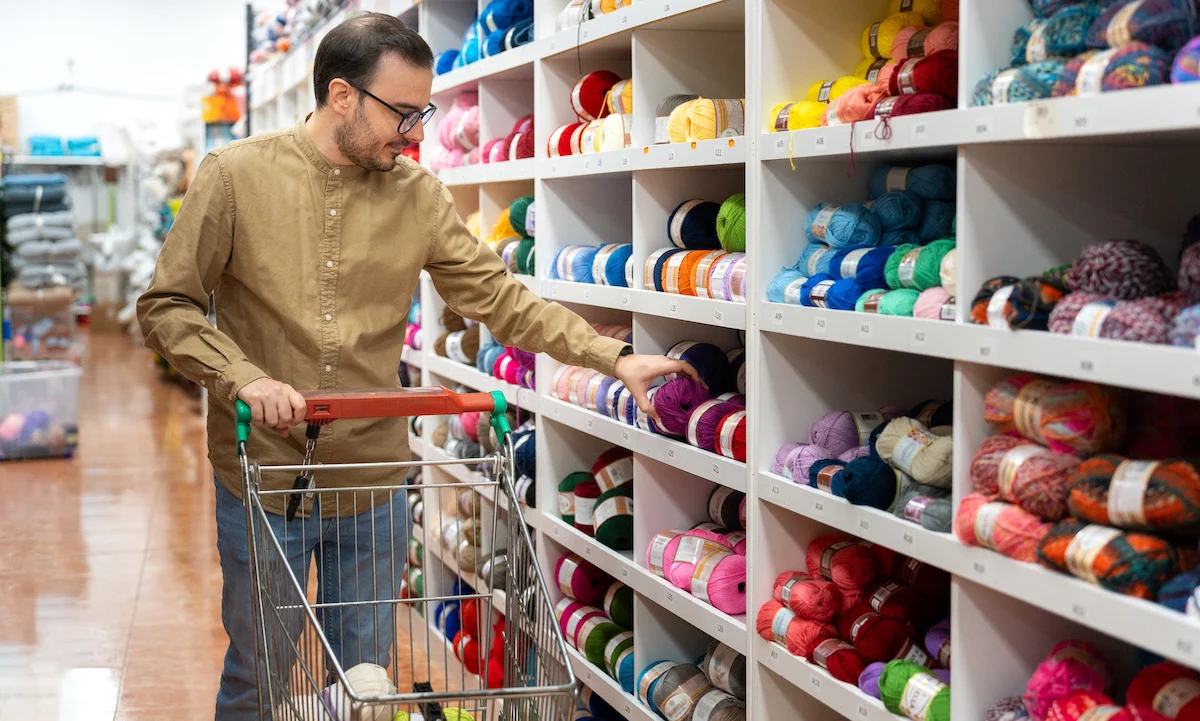
The modern consumer landscape is increasingly populated by a colorful array of quirky, internet-born acronyms and micro-demographics. In today’s economy, you are no longer just defined by your age or zip code. Instead, you might find yourself categorized as a DINKWAD—a dual-income couple with no kids, but a dog—or a HENRY, representing those who are high earners, but "not rich yet." You could equally fall into the bracket of the "elder millennial," a cohort old enough to remember the agonizing whine of dial-up internet, yet apparently young and financially liquid enough to drive a massive boom in the craft and hobby supply market.
While these labels often invite a knowing smile or a dismissive chuckle on social media, their underlying purchasing patterns offer a crucial, highly actionable reminder for merchants, financial institutions, and economists alike: individuals of ostensibly similar ages can possess vastly different claims on, and priorities for, their disposable income.
As traditional broad-stroke generational marketing loses its edge, understanding the nuances of these micro-segments has become essential for businesses trying to capture consumer wallet share in an increasingly fragmented economic climate.
Main Facts: The Anatomy of Modern Micro-Demographics
To understand how contemporary consumer behavior is evolving, one must look past traditional markers like the baby boomer, Generation X, or Gen Z divides. The real movement in retail and finance is happening within specific lifestyle and financial sub-groups that defy standard demographic categorizations.
At the center of this trend are three distinct populations driving outsized retail, luxury, and leisure trends:
- Elder Millennials: Generally defined by financial researchers as individuals born between 1978 and 1988, this group sits awkwardly on the generational fence. Someone born in 1978 might reasonably object to the "millennial" tag altogether—a minor border dispute that highlights the arbitrary nature of demographic boundaries. Yet, despite having some of the most constrained schedules in the workforce, this group is spending heavily on hobbies and personal enrichment.
- DINKWADs (Dual-Income, No Kids, With a Dog): Representing a modern evolution of the traditional DINK household, this demographic factors canine companions into major life milestones, spending decisions, and capital allocations, treating pets as full-fledged family members.
- HENRYs (High Earners, Not Rich Yet): Typically ranging from their early 20s to age 45, HENRYs pull in substantial annual incomes but have yet to accumulate significant net wealth or long-term assets. Their spending habits lean heavily toward experiential purchases, luxury goods, and alternative asset collections.
- Solo Agers: Perhaps the most economically consequential group without a humorous acronym, solo agers are older adults navigating life without a spouse or domestic partner at home. Their unique financial, healthcare, and estate-planning needs are fundamentally reshaping the wealth management and advisory sectors.
Chronology: The Evolution of Niche Marketing and Consumer Segmentation
The shift from macro-demographics to hyper-niche consumer profiling did not happen overnight. It is the result of compounding economic pressures, shifting social norms, and the digital economy’s granular data collection capabilities.
- The 2010s — The Rise of the DINK: Following the 2008 financial crisis, economic data began showing a distinct rise in married and cohabitating couples intentionally delaying or forgoing parenthood. According to historical Pew Research Center tracking, dual-income households without children began climbing steadily as housing costs rose and career flexibility became a priority.
- The Early 2020s — The Pandemic Pivot and Hobby Economy: Lockdowns and remote work changed how consumers viewed their immediate living spaces and free time. As burnout soared, demographic researchers began noting a surge in adult hobbyism. By the mid-2020s, institutions like the Bank of America Institute began tracking the "hobby economy," discovering that older cohorts were investing heavily in crafting, gardening, and creative pursuits despite shrinking leisure windows.
- Mid-2023 to 2025 — The Canine Economy and Luxury Collecting Go Mainstream: Market research firms like OnePulse began explicitly polling subsets like DINKWADs, uncovering that a staggering percentage of child-free couples were making major financial choices—such as purchasing specific automobiles or planning international vacations—entirely around the needs and comfort of their pets. Concurrently, luxury insurers like Chubb began tracking an influx of younger, high-earning collectors pouring disposable income into alternative stores of value, such as watches, fine jewelry, and rare art.
- 2026 — Convergence and Reality Check: By late 2026, financial services firms, retail giants, and payment providers have realized that these overlapping categories cannot be treated as isolated novelty trends. Birth years and cute acronyms tell only part of the story; merchants must now decode the deeper emotional and financial motivations driving these purchases.
Supporting Data: What the Numbers Tell Us
The economic footprint of these specialized consumer groups is backed by robust data from major financial institutions, insurers, and demographic research centers.
The Elder Millennial Time and Money Crunch
According to a comprehensive study published by the Bank of America Institute, older millennials currently spend more per customer on hobbies and creative supplies than any other living generation. Paradoxically, this same study revealed that older millennials possess the least amount of daily leisure time, averaging just four hours and 15 minutes a day.
Furthermore, Bank of America noted that hobby spending across its broader customer base rose by 7.9% in August compared to the same period a year prior, while the total volume of transactions grew by 3.4%. This divergence indicates that even modest pastimes are subject to inflationary pressures; a family opting for an afternoon of crafting over an expensive vacation quickly realizes that recreational supplies have grown markedly more expensive. Bank of America suggests that older millennials are likely purchasing these materials not just for themselves, but to entertain and educate their children as well.
The DINKWAD Lifestyle: Pets as Primary Beneficiaries
The DINKWAD phenomenon represents a dramatic shift in family planning and household expenditure. A survey conducted by OnePulse across 250 DINKWADs in the United Kingdom revealed the profound financial sway held by household pets:
- 44% of respondents stated they had planned an entire holiday or vacation specifically around their dog.
- Nearly one-third (approx. 33%) chose their primary personal vehicle based on how comfortably and safely their dog could fit inside.
While these survey metrics originated in the U.K., the underlying economic logic travels seamlessly across the Atlantic. The four-legged passenger directly influences automotive sales, travel and hospitality bookings, and specialized pet insurance policies.
This lifestyle is part of a broader structural shift documented by the Pew Research Center, which found that 12% of married couples in the U.S. with at least one spouse in their 30s or 40s fit into the dual-income, no-kids category in 2023, rising significantly from 8% a decade earlier. While Pew did not track how many of these couples owned dogs, the DINKWAD label successfully captures the hyper-indulgent spending behavior of a rapidly expanding sub-segment.
HENRYs and the New Era of Luxury Collecting
High Earners, Not Rich Yet (HENRYs) bridge the gap between upper-middle-class income and long-term asset accumulation. Data published by insurer Chubb from a survey of 1,000 self-identified HENRY collectors aged early 20s to 45 highlights their unique spending habits:
- 64% of these young high earners actively own luxury watches or fine jewelry.
- 51% collect fine art or rare antiques.
Crucially, many of these collectors view their acquisitions not merely as sources of aesthetic pleasure, but as tangible stores of value in an uncertain economic climate. Chubb noted that 47% of these collectors had insured their items, illustrating how a high salary funds the initial purchase, while asset protection and wealth preservation create secondary financial touchpoints.
Solo Agers: The Wealth Management Frontier
Perhaps the demographic shift carrying the weightiest long-term implications for financial services is the rise of the "solo ager." According to research from AARP, millions of older adults are deliberately or circumstantially living without a spouse or domestic partner at home. While many solo agers deeply value the autonomy and personal freedom this lifestyle provides, their circumstances require a complete reimagining of traditional financial advisory services. Solo agers must proactively plan for long-term care, guard aggressively against sophisticated financial scams, and designate trusted proxies to act on their behalf—services that retail banks and wealth managers are rushing to adapt to.
Official Responses and Industry Perspectives
Financial institutions, insurers, and market analysts are actively responding to the reality that broad generational generalizations are failing.
Industry analysts point out that these demographic labels are only useful when they point to concrete financial decisions and distinct behavioral motivations, rather than serving as hollow buzzwords for superficial marketing campaigns.
"A birth year tells only part of the story," notes retail strategy consultants observing the intersection of consumer debt and discretionary spending. "For merchants, banks, and payment providers, the better clue is what a customer is fundamentally trying to support—whether that is a child’s creative hobby, a beloved dog, a valuable alternative asset collection, or an independent, self-directed life."
Insurance executives, such as those at Chubb, emphasize that the financial needs of emerging affluent segments like HENRYs require specialized products that acknowledge their dual identity: individuals enjoying high present cash flow who are simultaneously trying to secure future asset stability.
Similarly, aging advocacy groups like AARP continue to lobby financial institutions to build more inclusive, flexible banking products that cater to solo agers, ensuring that single-person households are not penalized or overlooked by legacy mortgage, credit, and estate-planning frameworks.
Implications: What This Means for Retail, Banking, and Payments
The proliferation of DINKWADs, HENRYs, elder millennials, and solo agers carries profound operational and strategic implications for the commercial sector.
1. For Retailers and Brands
Merchants can no longer rely on targeting "Millennials" or "Gen Z" as monoliths. An elder millennial who is also a DINKWAD has radically different purchasing triggers than an elder millennial managing a multi-child household. Retailers must leverage advanced first-party data and AI-driven analytics to identify lifestyle markers—such as pet-friendly product browsing or high-end hobby material purchases—to tailor their product assortments and promotional messaging.
2. For Banks and Financial Institutions
Financial service providers must overhaul their customer segmentation models. HENRYs require wealth management strategies that bridge the gap between immediate lifestyle spending and long-term capital accumulation. Meanwhile, solo agers require specialized advisory services focused on autonomy, scam protection, and non-traditional estate planning. Banks that offer modular, lifestyle-aligned financial products will successfully capture loyalty from these lucrative sub-sectors.
3. For Payment Providers and Insurers
As spending habits become more specialized, the products supporting those purchases must adapt. Insurers must continue to innovate around alternative asset classes (for HENRY collectors) and pet-inclusive travel/lifestyle risks (for DINKWADs). Payment providers, on the other hand, must ensure their checkout infrastructures seamlessly support flexible, digital-first financing options for everything from high-end luxury collectibles to recurring hobby subscription boxes.
Conclusion
Ultimately, the growing alphabet soup of consumer labels—from DINKWADs and HENRYs to solo agers and hobby-obsessed millennials—is more than a linguistic trend. It is a reflection of a diversifying economic reality. By looking past rigid generational birth years and focusing on the underlying emotional and financial commitments driving consumer behavior, businesses can better serve a marketplace where no two wallets are quite alike.