As the workweek draws to a close, the financial markets are taking a breather, and mortgage rates are following suit. Following a week dominated by pivotal economic announcements and shifting bond yields, borrowing costs for prospective homeowners are holding remarkably steady, giving buyers and refinancers a brief moment of stability to evaluate their next steps.
According to rate data provided to NerdWallet by Zillow, the average interest rate on the benchmark 30-year fixed-rate mortgage remained unmoved at 7.05% APR. This flat line matches yesterday’s figures and sits just four basis points lower than this time last week. (A basis point, for context, is equal to one one-hundredth of a percentage point.) With markets closed over the weekend, Friday’s rates are expected to serve as the baseline heading into next week.
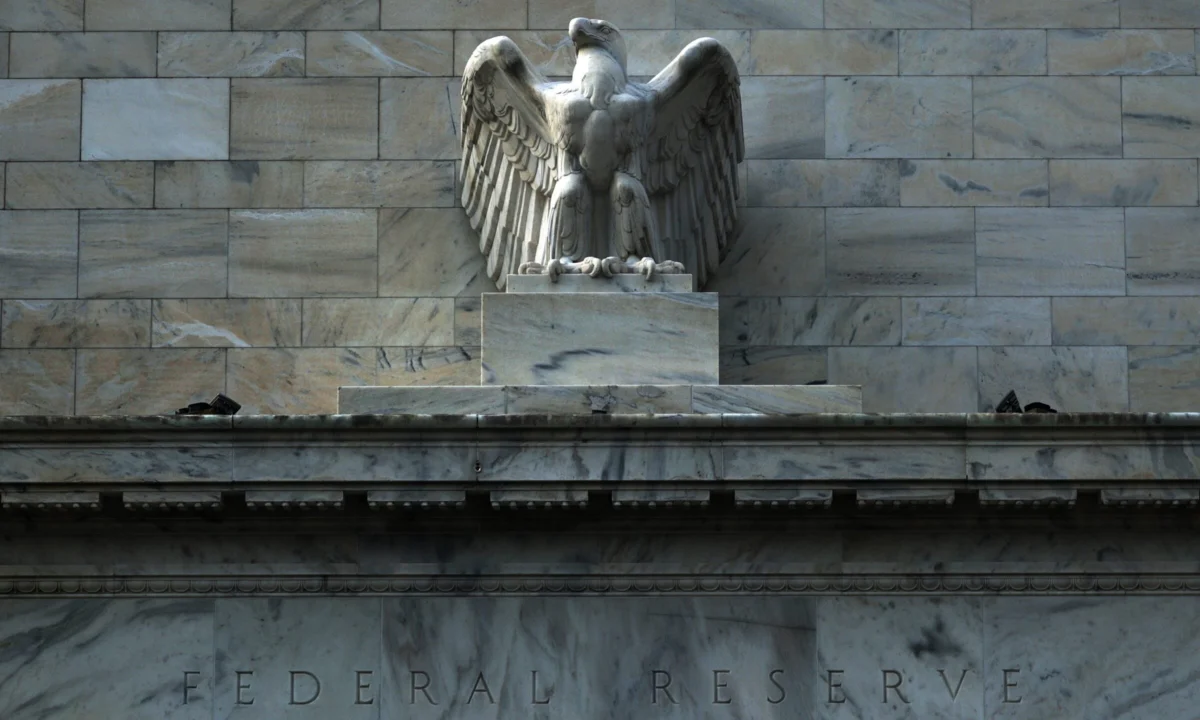
While the headline numbers appear calm, the underlying macroeconomic landscape is anything but quiet. The recent stability in the mortgage sector is tied directly to the fallout from this week’s Federal Reserve meeting, shifting bond yields, and growing signals that borrowing costs could remain elevated for the foreseeable future.
Main Facts: Where Mortgage Rates Stand Today
The current housing market is operating in a "higher-for-longer" interest rate environment, and today’s data reinforces that reality.
- 30-Year Fixed-Rate Mortgage: Holding steady at an average of 7.05% APR.
- Weekly Trend: Down marginally by 4 basis points compared to the previous week.
- Primary Driver: Mortgage rates are fundamentally pegged to the yield on the 10-year U.S. Treasury. As longer-term bond yields have cooled slightly, they have taken some of the upward pressure off mortgage pricing.
- Market Outlook: Weekend market closures mean today’s rates will likely remain locked in place until Monday morning.
While a 7.05% rate remains a significant hurdle for buyers accustomed to the historic lows of the pandemic era, the recent stabilization offers a welcome reprieve from the sharp upward spikes triggered by late-summer inflation reports.
Chronology: The Road to the September Fed Meeting
To understand why mortgage rates are behaving the way they are, it helps to retrace the sequence of economic indicators and policy decisions that shaped the market over the last several weeks.
Late Summer: Inflation Pressures Mount
Throughout the summer, a flurry of economic reports—including Consumer Price Index (CPI) and Producer Price Index (PPI) data—showed that inflation was proving stubbornly persistent. These readings unnerved the bond market, which reacted negatively to the Federal Reserve’s perceived inaction. As bond market anxiety grew, yields climbed, dragging mortgage rates upward alongside them.
Wednesday: The Fed Decision and Expected Hike
Heading into this week’s highly anticipated Federal Open Market Committee (FOMC) meeting, financial markets had already priced in a high likelihood of a move. Odds calculated by the CME Group’s FedWatch tool put the probability of a 25-basis-point rate hike at over 92%.
When the Federal Reserve officially raised the target for the federal funds rate by 25 basis points on Wednesday, it came as virtually no surprise. However, the subsequent release of the Fed’s economic projections and Chair remarks sent ripples through the financial ecosystem.
Thursday and Friday: Digesting the "Dose of Accommodation"
In the days following the announcement, analysts and investors parsed every word of the post-meeting press conference. Markets quickly realized that Wednesday’s rate hike might not be a one-off event, prompting adjustments in short-term rate probabilities and solidifying a cautious outlook across the board. By Friday, the initial volatility settled into the steady 7.05% baseline we see today.
Supporting Data: The Fed’s Dot Plot and Economic Projections
The most revealing information to emerge from the September Fed meeting wasn’t the universally anticipated rate hike itself, but rather the updated Summary of Economic Projections (SEP)—specifically, the infamous "dot plot."
The dot plot tracks anonymized predictions from committee members regarding where the federal funds rate should stand at the end of future years.
- The September Outlook: The majority of meeting participants indicated they believe the federal funds rate should be 25 basis points higher than its current target by the end of 2026. This signals anticipation for at least one more small hike down the road.
- A More Aggressive Contingent: A notable minority of officials project that rates should climb by a full 50 basis points before year’s end. This increase could materialize either as a pair of quarter-point adjustments during the October and December meetings or as a single larger hike in December.
- Shifting Market Odds: According to CME Group’s FedWatch tool, market pricing reflects growing conviction. The probability of another 25-basis-point hike in October has risen to roughly 55%, while the odds of a follow-up move in December hover just under 43%—up significantly from weeks prior.
Official Responses: Parsing Chair Kevin Warsh’s Statements
Federal Reserve leadership has long maintained that monetary policy should be driven strictly by incoming economic data rather than market speculation—though market watchers routinely hang on every syllable uttered by Fed officials.
During the post-announcement press conference, Fed Chair Kevin Warsh made it clear that recent inflation trends continue to heavily influence the central bank’s mindset, despite his stated preference for long-term policy independence.
"This summer’s inflation readings do not tell me that underlying trends have meaningfully improved," Warsh remarked during his opening statement. "Based on the most recent CPI and PPI data, the 12-month change in total PCE prices likely was around 3.6% in August. Core PCE and CPI prices are running at about 3.2% and 2.4% respectively."
Furthermore, Warsh introduced a phrase that immediately captured the attention of Wall Street analysts: "dose of accommodation."
Explaining the committee’s rationale for tightening policy, Warsh noted: "I would be hard-pressed to describe broad financial conditions as restrictive. This view was widely shared by the committee. So, we removed a dose of accommodation."
He repeated the phrase twice more during the Q&A session. To market participants, the wording signaled that the central bank views current financial conditions as still somewhat loose, heavily implying that further tightening measures could be deployed if inflation fails to cool to the Fed’s 2% target.
Implications: What This Means for Homebuyers and Owners
The interplay between the Federal Reserve’s inflation fight and the bond market has created a complex environment. While the Fed’s aggressive posture has successfully calmed bond market anxieties—temporarily halting the rapid ascent of mortgage rates—it also guarantees that borrowing costs will remain high.
If you are navigating the real estate market today, here is how these developments impact your strategic decisions:
Should I Refinance?
Generally speaking, refinancing becomes financially viable if current market rates drop at least 0.5 to 0.75 of a percentage point below your current rate, provided you plan to stay in your home long enough to recoup closing costs through monthly savings.
With the 30-year fixed rate hovering around 7.05%, homeowners with legacy rates of 7.55% or higher should seriously evaluate their refinancing options. Beyond simply lowering your monthly payment, consider your broader financial goals:
- Are you looking to shorten your loan term?
- Do you need to execute a cash-out refinance to consolidate higher-interest debt or fund home renovations?
- Do the overall costs of a cash-out refi outweigh the alternative of keeping your original mortgage and taking out a Home Equity Line of Credit (HELOC)?
Should I Start Shopping for a Home?
There is no universally "perfect" time to buy a home. The fundamental question is whether you can comfortably manage a monthly mortgage payment under today’s prevailing interest rates.
If your budget allows for it, experts advise against sitting on the sidelines waiting for a dramatic drop in rates that may take years to materialize. Remember the classic real estate mantra: "Marry the house, date the rate." You can always refinance your mortgage down the road if rates eventually decline. In the interim, focus on getting preapproved, shopping around with multiple lenders, and ensuring your debt-to-income ratio is in a healthy place.
If buying right now is out of reach, use this period to strengthen your buyer profile by paying down existing debt and expanding your down payment savings. Doing so will improve your creditworthiness and secure you a better rate when you are ready to jump into the market.
Should I Lock My Rate?
If you have already received a competitive mortgage quote that fits your budget, locking your rate is strongly recommended, especially if your lender offers a "float-down" option. A float-down provision protects you against unexpected market spikes while still allowing you to capture a lower rate if market conditions improve before your loan closes. Given how volatile the bond market has been in response to economic data, locking in a rate provides invaluable peace of mind.
Summary: Navigating the Market Today
Today’s flat mortgage rates offer a temporary calm amidst a turbulent economic backdrop. With the Federal Reserve signaling a resolute commitment to subduing inflation—and leaving the door open for additional rate adjustments later this year—borrowers must adjust their expectations for a higher-for-longer rate environment.
Whether you are shopping for your first home, considering a refinance, or preparing to lock in a loan quote, success in today’s housing market depends on a clear-eyed assessment of your personal budget, thorough comparison shopping among lenders, and a long-term perspective on real estate wealth.