In an era of rising litigation, multimillion-dollar court verdicts, and increasing liability risks, standard auto and homeowners insurance policies may no longer offer sufficient protection. While most Americans rely on traditional insurance packages to safeguard their wealth, experts warn that these policies often harbor a dangerous blind spot: liability caps. When a catastrophic accident or lawsuit exhausts standard policy limits, the remaining financial burden falls directly on the policyholder, threatening personal savings, real estate, and future earnings.
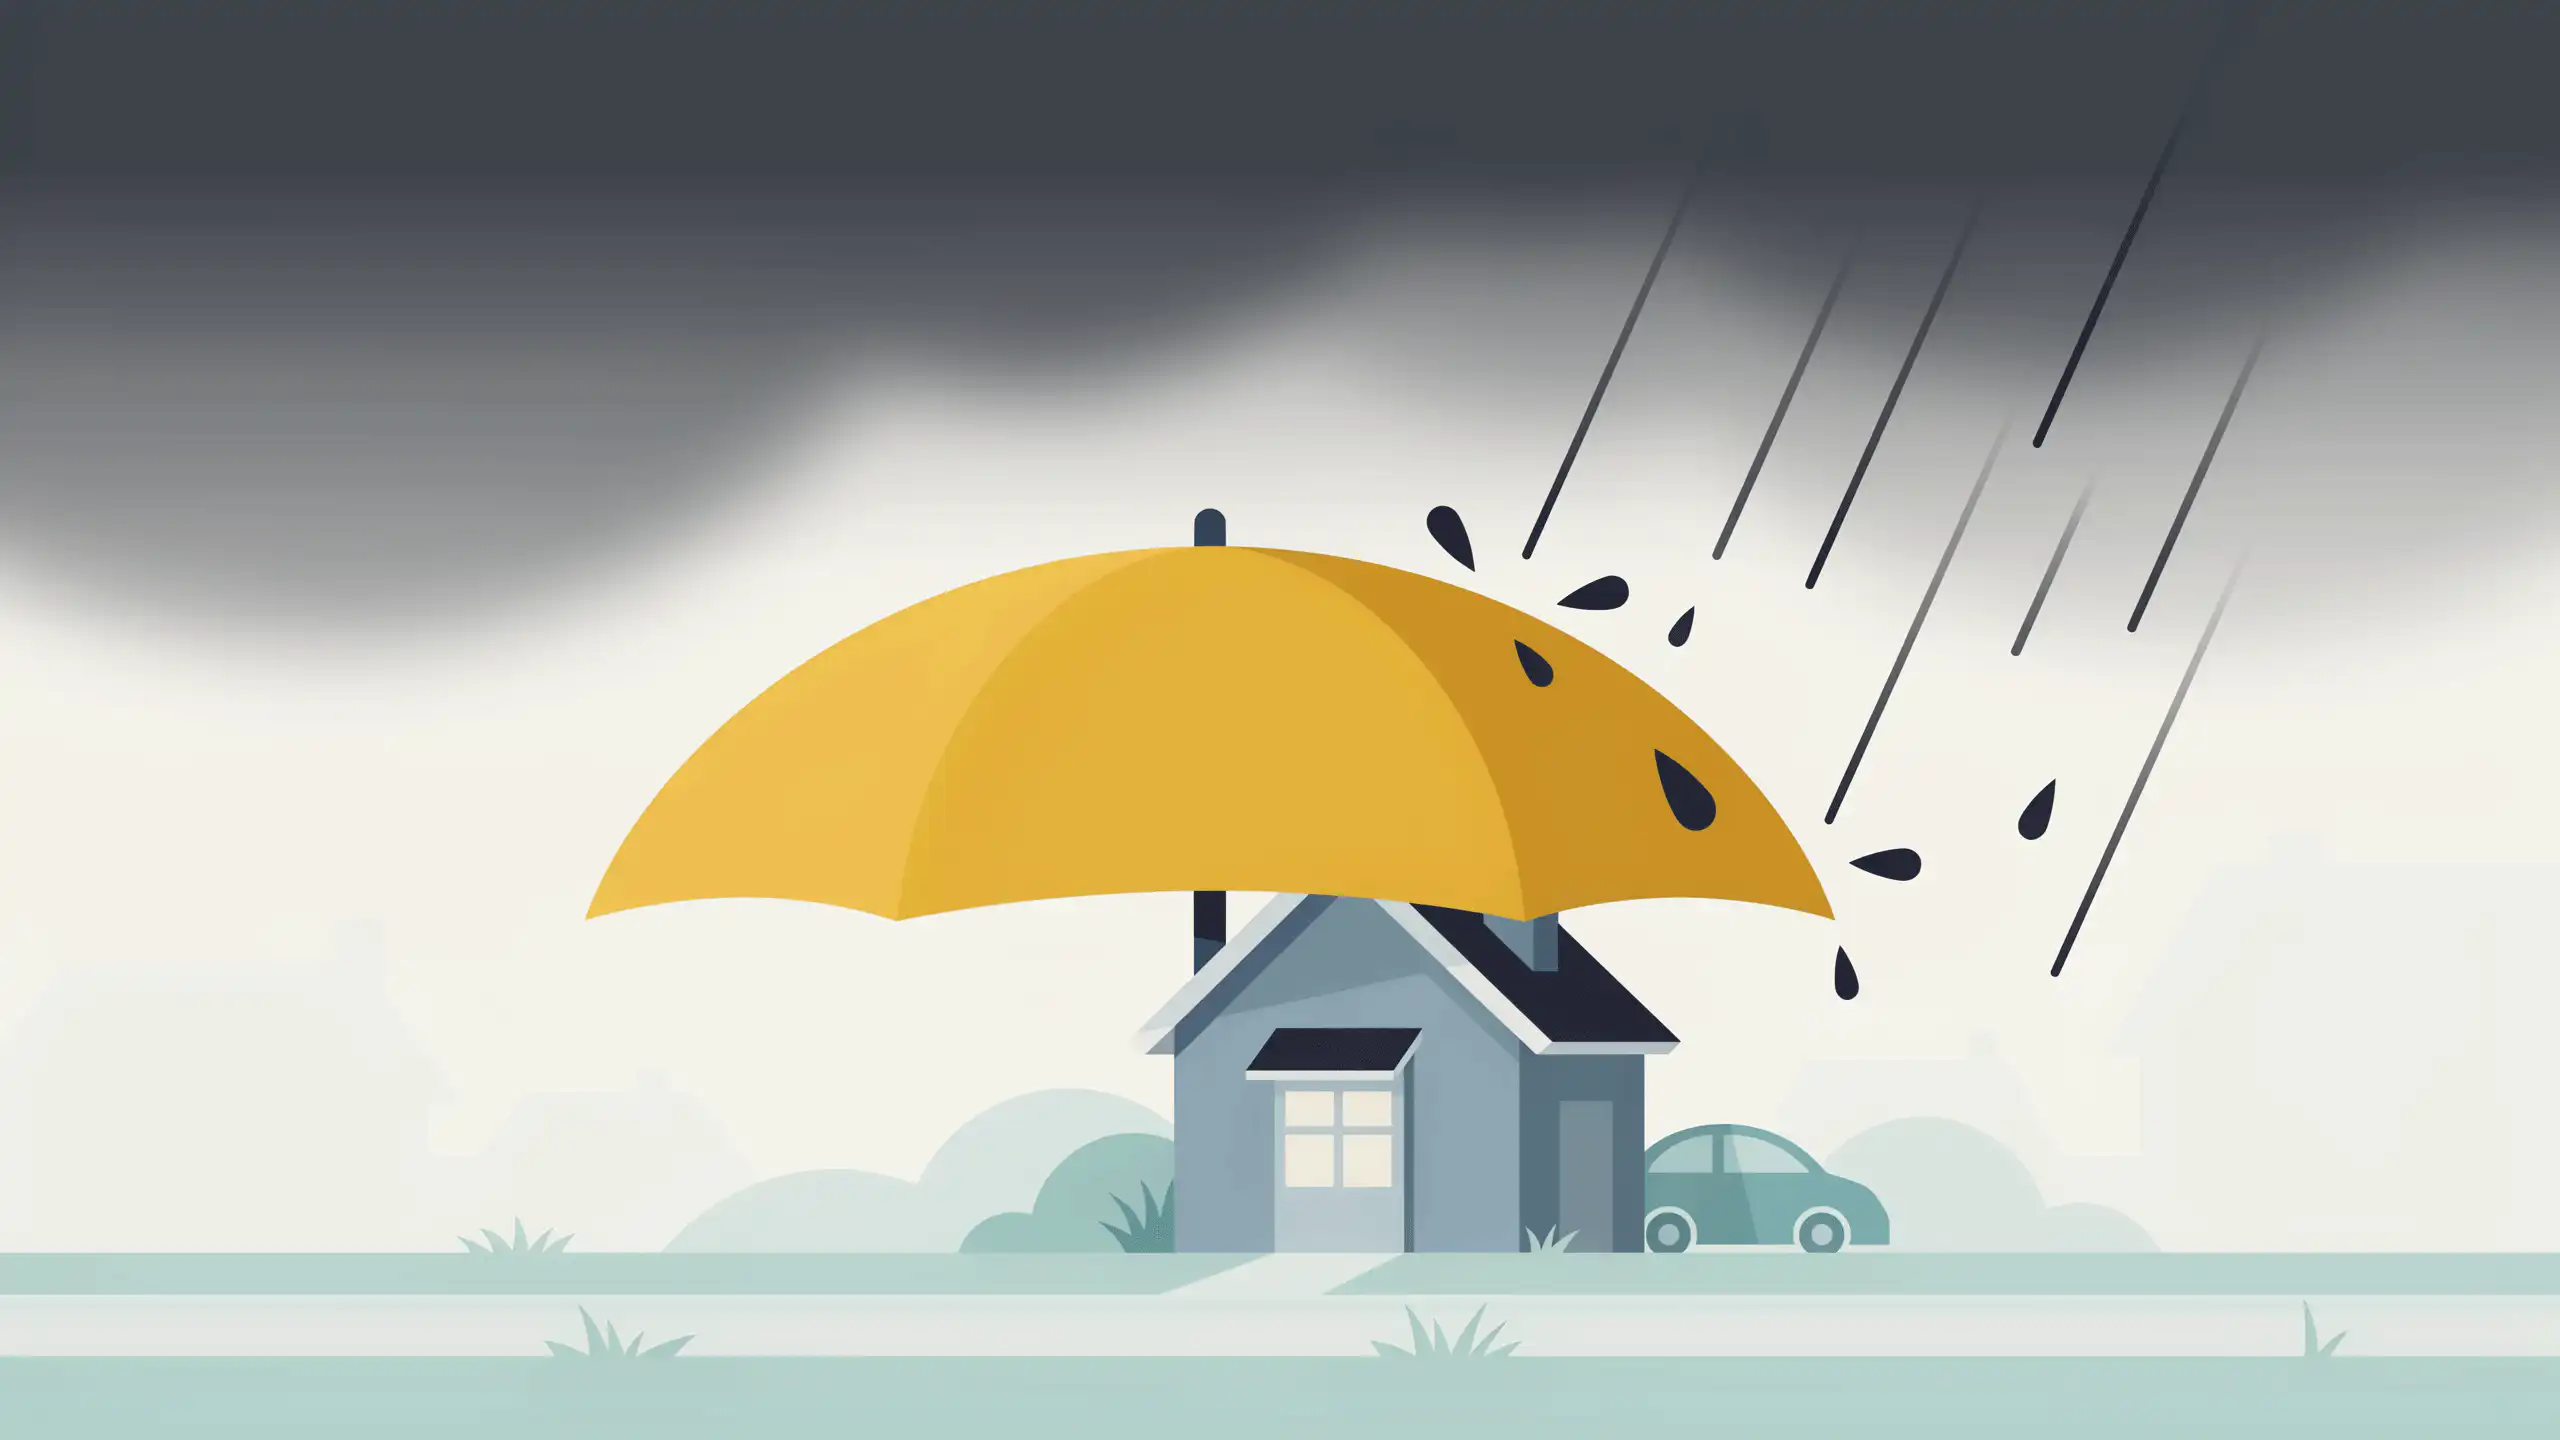
To bridge this perilous gap, financial planners increasingly recommend personal umbrella insurance. Offering millions of dollars in additional liability coverage for a surprisingly modest annual premium, umbrella policies have transformed from a luxury product for the ultra-wealthy into an essential risk-management tool for the modern middle and upper-middle class.
Main Facts: Understanding the Vulnerability and the Solution
At its core, a personal umbrella policy (PUP) is a secondary layer of liability insurance designed to kick in only after your primary auto, homeowners, boat, or renters insurance limits have been completely exhausted.
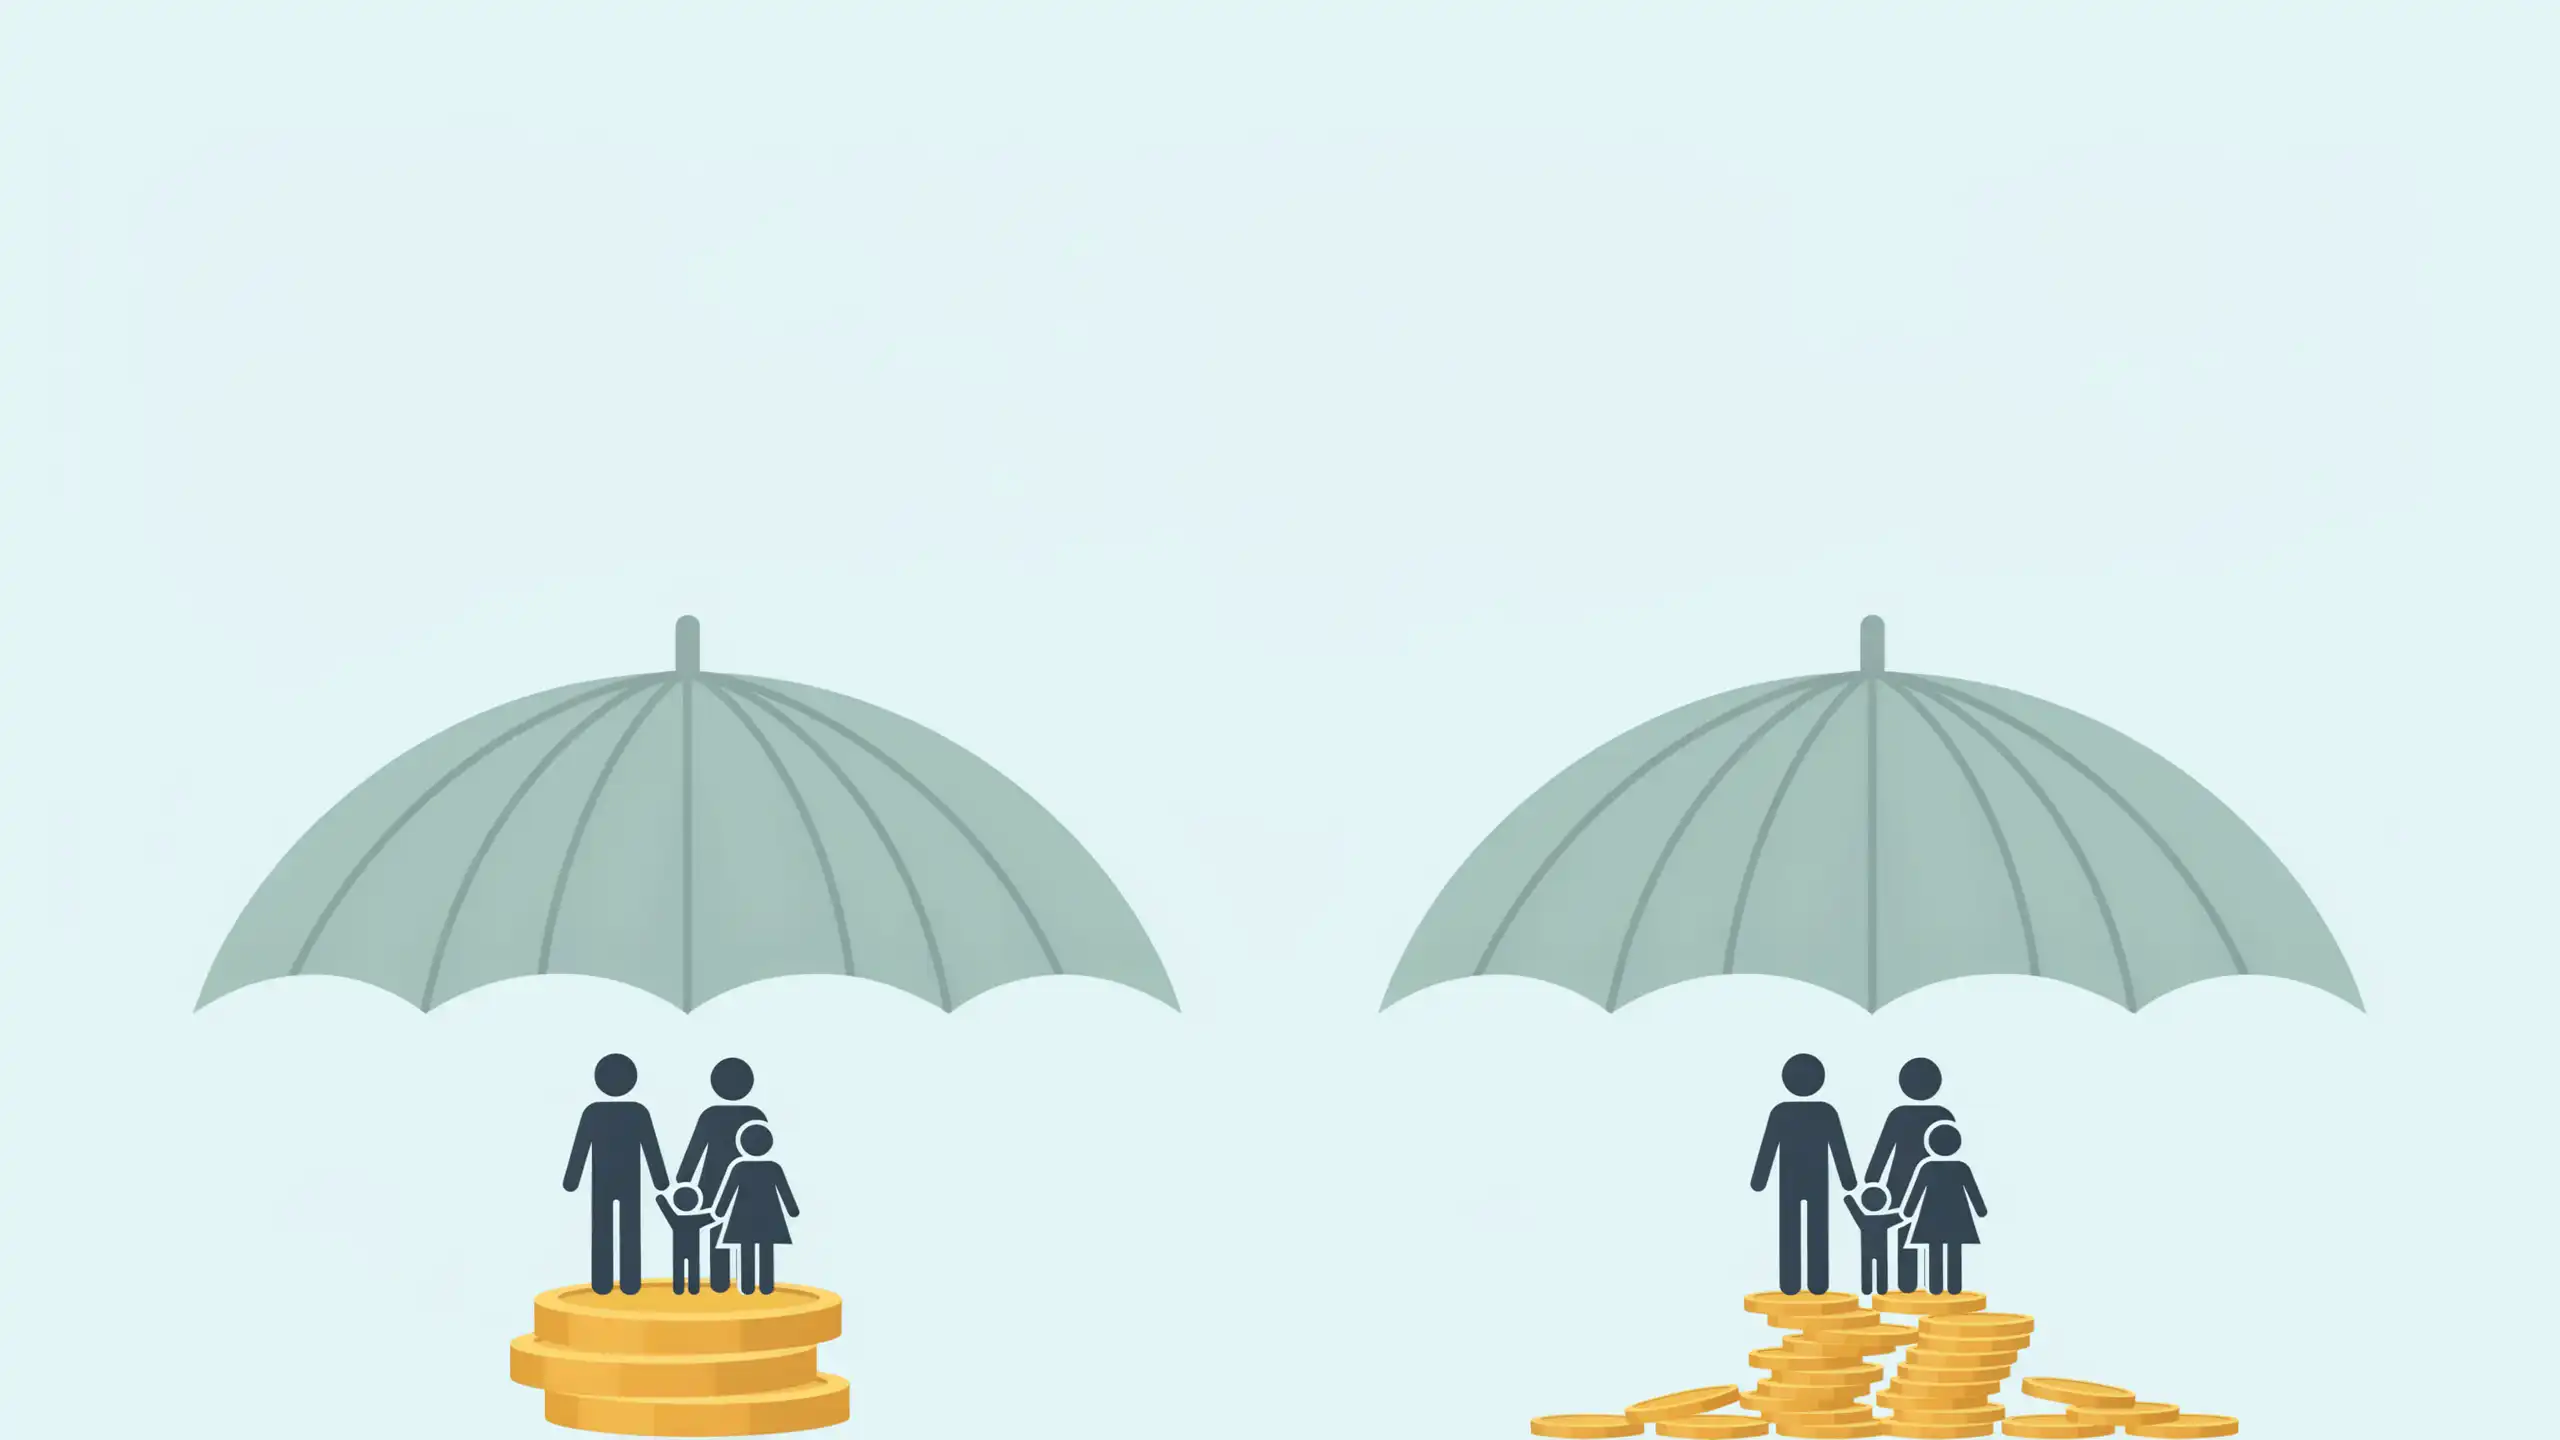
To understand the necessity of this coverage, consider a standard liability structure. If a driver carries auto insurance with bodily injury limits of $250,000 per person and $500,000 per accident, the insurance carrier will pay up to those designated amounts in the event of a covered at-fault collision. However, if a court awards injured parties a total of $900,000, the insurer’s obligation stops at the $500,000 cap. The remaining $400,000 becomes the personal responsibility of the at-fault driver.
Without an umbrella policy, plaintiffs can aggressively pursue a defendant’s personal assets. This includes liquid savings, investment portfolios, retirement accounts not protected by federal or state ERISA laws, equity in secondary homes, and even wage garnishments. Under federal law, creditors can garnish up to 25% of an individual’s disposable (after-tax) earnings to satisfy a civil judgment.
An umbrella policy absorbs these catastrophic overages. Typically sold in $1 million increments, these policies not only extend auto and home liability limits but also frequently cover expanded liabilities that standard policies routinely exclude—such as legal defense costs, defamation claims (libel and slander), false arrest, and invasion of privacy.
Chronology: The Evolution of Personal Liability and Umbrella Insurance
The trajectory of personal liability insurance mirrors the litigious evolution of modern society. Understanding how personal risk has escalated helps explain why umbrella policies have become critical fixtures in comprehensive financial planning.
- Mid-20th Century (The Rise of Standard Policies): As automobile ownership skyrocketed following World War II, state governments began implementing mandatory auto liability laws. Homeowners insurance similarly evolved to package property and casualty protection into a single product. During this era, liability limits of $10,000 to $50,000 were considered more than adequate to cover average damages and legal fees.
- The 1970s and 1980s (The Birth of the "Litigation Explosion"): Driven by changes in tort law, the expansion of legal precedents regarding negligence, and the growing prevalence of contingency-fee attorneys, jury awards began to climb dramatically. Insurance companies recognized that standard policy caps were frequently breached in severe accidents, prompting the introduction of personal umbrella policies to protect affluent policyholders.
- The Turn of the Century to 2010s (Mainstreaming Risk Management): As medical costs escalated and property values surged, the financial impact of a major lawsuit expanded exponentially. Umbrella policies transitioned from an exclusive product for high-net-worth individuals to a recommended staple for middle-class homeowners, particularly those with teenage drivers, residential swimming pools, or entrepreneurial side ventures.
- Present Day (The Era of "Nuclear Verdicts"): Contemporary legal environments are characterized by "nuclear verdicts"—jury awards exceeding $10 million. Social inflation, rising healthcare costs, and aggressive legal marketing have made catastrophic lawsuits more common. Consequently, insurance experts now advise anyone whose net worth exceeds their primary policy limits to secure umbrella coverage immediately.
Supporting Data: Costs, Requirements, and Risk Factors
Despite providing millions of dollars in supplemental security, personal umbrella insurance remains remarkably affordable. Because an umbrella policy is strictly secondary—meaning it only pays out after primary policies are depleted—the risk to the insurance carrier is statistically low.
Financial Breakdown
- Base Cost: According to data from major insurers like Progressive, the average cost for a $1 million personal umbrella policy covering one primary residence, two vehicles, and two drivers hovers around $383 per year.
- Incremental Expansion: Expanding coverage from $1 million to $2 million typically costs only an additional $75 annually, making higher limits exceptionally cost-effective.
- Underwriting Prerequisites: Insurance companies will not sell an umbrella policy in isolation. To qualify, applicants must maintain robust primary coverage. Insurers generally require auto liability limits of at least $250,000 / $500,000 and homeowners liability limits of at least $300,000. If current primary limits fall below these thresholds, policyholders must increase them before an umbrella binder can be issued.
Who Needs an Umbrella Policy Most?
While any individual with assets or future earning potential can benefit from an umbrella policy, the Insurance Information Institute (III) highlights specific lifestyle factors that dramatically elevate liability exposure:
- Teenage Drivers: Statistically prone to higher accident rates, young drivers dramatically increase a household’s auto liability exposure.
- Home Amenities: Swimming pools, trampolines, and aggressive dog breeds are frequent catalysts for premises liability lawsuits and dog-bite claims.
- Rental Properties or Real Estate Holdings: Landlords face unique tenant-related liabilities and slip-and-fall claims on secondary properties.
- Frequent Hosts and Public Figures: Individuals who regularly host large gatherings, serve on non-profit boards, or maintain a prominent social media presence face elevated risks of slander, libel, or guest injuries.
- High Earners: Even individuals with modest current savings should consider an umbrella policy if they command a high salary, as future paychecks remain vulnerable to long-term wage garnishment.
Official Industry Responses and Expert Perspectives
Insurance regulators, consumer advocacy groups, and financial planning bodies universally emphasize the importance of liability audits, yet consumer adoption rates remain surprisingly low.
Industry analysts point to a common psychological barrier: the misconception that primary insurance limits are "enough." Many consumers select standard limits (such as $100,000 or $300,000) simply because they meet state minimums or lender requirements, without ever conducting a formal net-worth assessment.
"People spend an incredible amount of time protecting their physical assets—locking doors, installing security systems, and buying fire alarms—yet they leave their financial foundation wide open to a single catastrophic lawsuit," notes a senior property and casualty specialist with the Insurance Information Institute. "An umbrella policy is the ultimate financial deadbolt. For roughly a dollar a day, it protects everything you’ve built and everything you plan to earn."
Financial advisors recommend an audit methodology known as the "Net Worth Equation." To determine the appropriate umbrella coverage amount, individuals should calculate their total net worth—including primary homes, investment accounts, business equity, and savings—and ensure their combined primary and umbrella liability limits match or exceed that figure. For high-earning professionals whose future lifetime earnings far outstrip their current asset base, advisors often recommend purchasing $2 million to $5 million in umbrella protection.
Implications: Securing Your Financial Future
Failing to account for liability gaps can have devastating, lifelong consequences. A single unfortunate event—a slick patch of highway, a distracted moment behind the wheel, or a visitor slipping on an icy walkway—can instantly unravel decades of diligent saving, investing, and career advancement.
For middle-class families, a civil judgment exceeding primary insurance limits can trigger forced liquidation of retirement funds, the sale of a family home, or years of mandatory wage garnishment. This effectively resets an individual’s financial timeline, destroying retirement readiness and generational wealth transfer.
Conversely, integrating a personal umbrella policy into an overall financial plan provides invaluable peace of mind. By spending a few hundred dollars a year to cover the high-stakes gray area between standard policy caps and catastrophic losses, policyholders effectively inoculate their financial futures against the unpredictability of modern litigation.
Actionable Next Steps:
- Review Declarations Pages: Pull the one-page coverage summary (declarations page) from your current auto, home, and boat insurance policies.
- Audit Your Limits: Verify whether your current auto liability limits meet or exceed $250,000/$500,000 and your homeowners limits meet or exceed $300,000.
- Calculate Your Exposure: Tally your total net worth and evaluate your lifestyle risk factors (e.g., teen drivers, rental properties, pets, public profiles).
- Request a Quote: Contact your current insurance provider this week to request a competitive quote for a $1 million to $3 million personal umbrella policy. Ensuring your coverage matches your hard work is one of the most cost-effective risk-management decisions you can make.