WASHINGTON — In the complex world of personal finance, few decisions spark as much debate—or carry as significant a financial footprint—as purchasing life insurance. For decades, consumers navigating the insurance market have been forced to choose between two fundamentally different financial instruments: term life insurance, which provides straightforward protection for a set period, and whole life insurance, a permanent product that bundles a death benefit with an investment vehicle known as cash value.
While insurance agents have traditionally pushed permanent policies for their lifelong coverage and accumulation features, a growing chorus of financial planners, consumer advocates, and recent industry data point to a simpler, more cost-effective strategy for the average household. By purchasing an affordable term life policy to cover peak financial vulnerability years and aggressively investing the remaining capital—a strategy commonly known as "buy term and invest the difference"—families could potentially build substantial wealth while maintaining robust protection.
Main Facts: Term Versus Whole Life
At its core, life insurance serves a singular, critical economic purpose: replacing lost income to ensure that dependents are not left financially vulnerable in the event of a wage earner’s untimely death. However, the mechanism by which policies achieve this varies wildly in cost and structure.
Term life insurance operates much like auto or homeowners insurance. It provides pure, unadulterated protection for a specified timeframe—typically 10, 15, 20, 25, or 30 years. If the policyholder passes away during that term, the beneficiaries receive the payout (the death benefit). If the term expires and the insured is still alive, the contract ends, and no payout is made. Because the insurer’s risk diminishes as the insured successfully navigates their working years, term policies are remarkably inexpensive.
Conversely, whole life insurance is a form of permanent coverage designed to last an entire lifetime, provided premiums are paid. It features a guaranteed death benefit coupled with a "cash value" component. A portion of every premium payment goes toward the cost of insurance, while the remainder is funneled into a tax-advantaged savings or investment account managed by the insurance carrier.
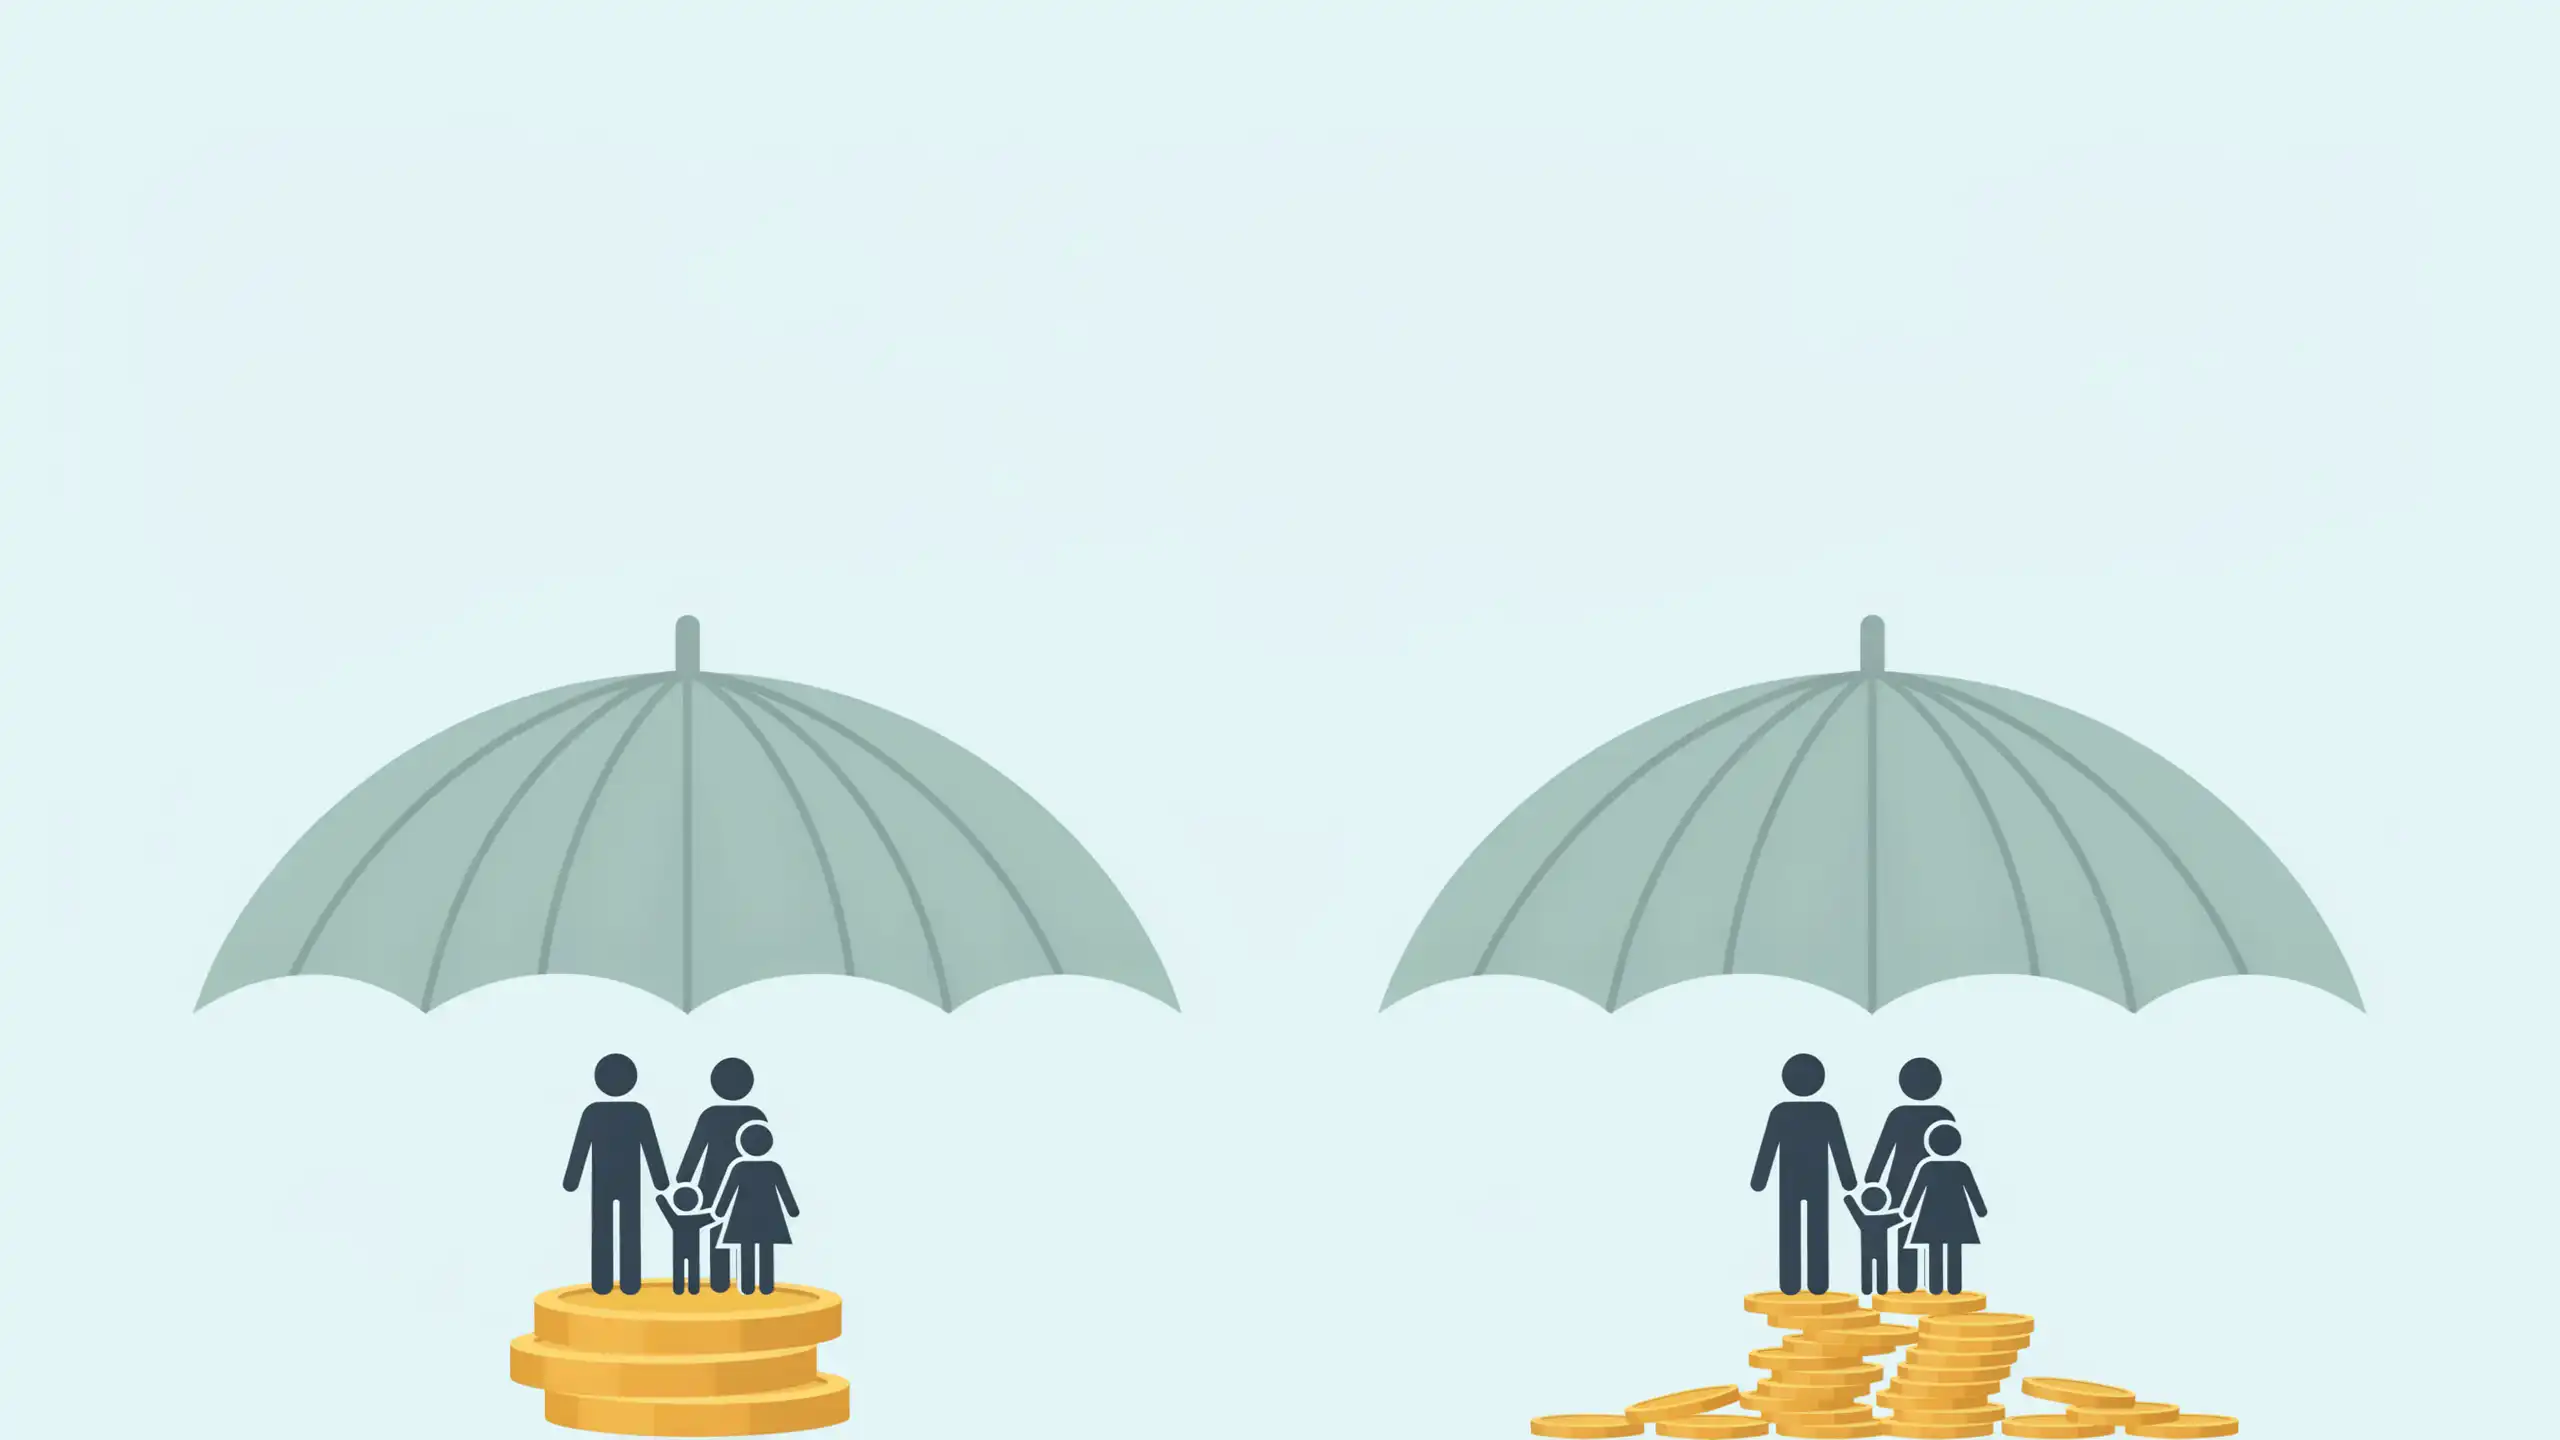
The primary friction point between the two products is cost. According to comprehensive market rate analyses from MoneyGeek, the financial gap between term and whole life is staggering. For a 35-year-old male nonsmoker in average health, securing a $500,000, 20-year term life policy costs roughly $40 per month. A whole life policy offering the exact same $500,000 death benefit commands a monthly premium of approximately $545—nearly 14 times the cost of the term policy.
This vast price discrepancy stems from the dual nature of permanent insurance. Policyholders are not merely paying for mortality risk; they are paying administrative fees, commissions, and management costs associated with the internal savings vehicle.
Chronology and Evolution of the Insurance Debate
The philosophical divide over how consumers should buy insurance dates back to the mid-20th century, evolving alongside modern portfolio theory and the rise of low-cost index funds.
- Pre-1970s Era: Historically, permanent life insurance dominated the American household landscape. Insurance was frequently sold by captive agents who emphasized the forced-savings aspect of whole life policies, pitching them as a safe way to accumulate wealth while protecting a family.
- The 1980s Financial Shift: As inflation spiked and alternative investment vehicles—such as mutual funds and 401(k) plans—became widely accessible to the retail public, financial educators began challenging the wisdom of tying insurance to investments. Pioneers in personal finance popularized the mantra "buy term and invest the difference," arguing that consumers could achieve higher returns by managing their own investments rather than relying on insurance company portfolios.
- The 2000s to 2010s Digital Age: The proliferation of online insurance brokerages radically transformed consumer behavior. For the first time, buyers could easily compare term life quotes across dozens of carriers in minutes, stripping away the mystery of underwriting costs and accelerating the adoption of term products.
- The 2026 Landscape: Today, economic pressures, rising costs of living, and a heightened focus on retirement readiness have brought the debate back to the forefront. With modern rate benchmarks highlighting a $505 monthly delta between term and whole life coverage for standard applicants, financial advisors are increasingly steering young families toward leaner risk-management models.
Supporting Data and Financial Modeling
To understand why the "buy term and invest the difference" philosophy commands such loyalty among fee-only financial planners, one must examine the hard math behind the strategy.
Taking the aforementioned benchmark scenario—a $505 monthly savings by choosing a 20-year term policy over a whole life policy—financial analysts can project long-term wealth accumulation. If a policyholder takes that $505 monthly difference and systematically invests it into a diversified portfolio (such as a 401(k), IRA, or taxable brokerage account tracking broad market indexes) assuming a conservative historical average annual return of 6%, the results are striking.
Over a 20-year horizon, consistent monthly contributions compounded at 6% would yield approximately $233,000 in cash assets.
In contrast, whole life insurance cash values are notoriously slow to accumulate in the early years of the contract. According to buyer’s guides published by the National Association of Insurance Commissioners (NAIC), a significant portion of early whole life premiums goes toward agent commissions and administrative overhead. Consequently, cash surrender values often remain minimal for the first decade of the policy, only accelerating later in life.
Furthermore, critics note that whole life returns generally lag behind broader equity markets due to conservative general-account investing by insurance companies, which heavily favor high-grade corporate bonds and government debt to guarantee minimum payouts.
Official Perspectives and Industry Guidelines
Regulatory bodies and industry watchdogs maintain neutral stances on product types, emphasizing that each serves a distinct financial function depending on a consumer’s unique lifecycle stage.
The National Association of Insurance Commissioners (NAIC) outlines clear consumer guidance regarding when permanent insurance makes logical sense. According to NAIC literature, cash-value and permanent policies can be the more economical and practical route when an individual has a permanent financial obligation.
Examples of permanent needs include:
- A dependent child with severe physical or cognitive disabilities who will require lifelong financial care and support.
- High-net-worth estates facing substantial estate tax liabilities, where heirs will require immediate liquid cash upon the policyholder’s death to settle tax burdens without selling illiquid assets like real estate or family businesses.
- Business continuation planning, such as funding complex buy-sell agreements among partners where policies must remain active regardless of advanced age.
Conversely, for the vast majority of working-class and middle-class families, the need for life insurance is temporary.
"For most families, life insurance does one primary job: replacing your income while others depend on it," notes financial education commentary from leading consumer resource platforms. "Once the kids are finished with school, the mortgage is fully paid off, and your retirement accounts are robust enough to support a surviving spouse, nobody depends on your paycheck anymore. At that stage, maintaining high-cost insurance premiums becomes an unnecessary financial drain."
Implications for Modern Consumers and Households
The choice between term and whole life insurance carries profound implications for household budgeting and long-term financial independence.
1. Cash Flow Flexibility
For young families juggling mortgages, childcare expenses, and retirement contributions, every dollar counts. Freeing up over $500 a month by opting for term life insurance provides immediate breathing room in a household budget. That capital can be redirected toward eliminating high-interest consumer debt, building an emergency fund, or maximizing employer-matched retirement plans.
2. The Risk of Policy Lapses
While the mathematical advantages of term insurance are clear, behavioral finance experts issue one vital caveat: discipline is required. The "buy term and invest the difference" strategy only works if the consumer actually invests the difference. If the savings are absorbed into lifestyle inflation—spent on dining out, luxury goods, or unbudgeted discretionary purchases—the consumer loses both the whole life cash value and the alternative investment nest egg. Automating transfers into retirement accounts or low-cost index funds is widely recommended to mitigate this behavioral risk.
3. Tailoring Coverage to the Lifecycle
Ultimately, financial advisors recommend conducting a comprehensive "needs analysis" rather than defaulting to a blanket insurance product. By matching the length of a term policy to the exact window of vulnerability—such as a 20-year term bought when a child is born—families secure maximum protection when stakes are highest, transitioning smoothly into self-insurance as their investment portfolios mature.
As economic conditions continue to fluctuate, the directive for consumers remains clear: insure the years that people depend on your earnings, and let disciplined, diversified investments secure the decades that follow.