As global economic paradigms shift and policymakers grapple with the realities of a deglobalizing world, prominent legal and economic scholars are rethinking the boundaries of corporate taxation. At the center of this renewed debate is a forthcoming Tax Law Review article titled “Taxation and Deglobalization,” authored by distinguished legal scholar Reuven Avi-Yonah.
Avi-Yonah’s provocative thesis suggests that if a country implements specific structural fixes to its corporate tax base—most notably the full expensing of business investments—traditional worries regarding the negative economic fallout of high corporate income tax (CIT) rates would essentially vanish. This bold proposition aligns with a broader intellectual undercurrent among various scholars and analysts who argue for a strategic overhaul of the corporate tax structure: fix the tax base first, then raise the rate.
However, this growing enthusiasm for structural tax base fixes comes with a dangerous caveat. While reforming the tax base can significantly improve economic efficiency, treating corporate tax rates as irrelevant once expensing is established is a serious analytical misstep. Even under ideal tax base conditions, imposing an 80 percent corporate tax rate—as Avi-Yonah entertains for high-profit entities—carries profound economic distortions that cannot be glossed over.
Main Facts: The Intersection of Deglobalization and Tax Reform
The debate over corporate tax rates and bases occurs against a backdrop of sweeping international economic changes. For decades, hyper-globalization allowed multinational corporations to seamlessly shift profits across borders to low-tax jurisdictions, minimizing their overall tax burdens and forcing nations into a competitive "race to the bottom" on corporate tax rates.
According to Avi-Yonah, the ongoing trend toward "deglobalization"—marked by reshoring, trade barriers, and a renewed emphasis on domestic market access—fundamentally alters this dynamic. In a deglobalized economy, corporations find it much harder to relocate their headquarters or shift profits offshore without losing access to lucrative consumer markets like the United States. Consequently, Avi-Yonah argues that a progressive corporate tax rate structure, scaling up to an astonishing 80 percent for global profits exceeding $10 billion, becomes feasible.
To support this high-rate framework, Avi-Yonah advocates for structural fixes designed to neutralize profit shifting and eliminate investment disincentives. Chief among these is full expensing, which allows businesses to immediately deduct the full cost of capital investments.
Other prominent analysts—including Kimberly Clausing, Jason Furman, Michael Linden, and Samantha Jacoby—have similarly explored variations of the "fix the base, raise the rate" philosophy, though generally stopping short of the extreme rates proposed by Avi-Yonah. Meanwhile, critics like Kyle Pomerleau maintain that corporate rate hikes remain fundamentally unwise, regardless of base-broadening efforts.
Chronology: The Evolution of the "Fix the Base, Raise the Rate" Debate
To understand how tax policy discussions arrived at the prospect of an 80 percent corporate rate, it is helpful to trace the intellectual milestones leading to modern tax reform proposals:
- The Hall-Jorgenson Framework (Historical Foundation): For decades, economists have relied on standard neoclassical user cost models to evaluate how taxation affects capital investment. Within this framework, full expensing mathematically removes the tax rate from the user cost of capital, sparking decades of academic literature on the neutrality of cash-flow taxation.
- The Rise of Profit Shifting and Base Erosion (1990s–2010s): As multinational enterprises grew increasingly sophisticated, profit shifting became a dominant challenge for sovereign tax authorities. This era highlighted the need for destination-based cash flow taxes (DBCFT) and border adjustments to protect domestic tax bases.
- Recent Academic and Policy Proposals (2020s): Scholars began exploring how post-globalization economic structures could alter tax enforceability.
- Forthcoming Tax Law Review Publication (Present): Reuven Avi-Yonah synthesizes these threads in "Taxation and Deglobalization," arguing that a deglobalizing world empowers governments to levy exceptionally high progressive rates on corporate economic rents—provided the underlying tax base is secured through measures like full expensing and digital services taxes.
Supporting Data: Why the Standard Economic Model Fails at Extreme Rates
The core theoretical justification for assuming tax rates don’t matter under full expensing relies on the traditional Hall-Jorgenson user cost of capital formula:
$$c = fracr + delta1 – tau(1 – z)$$
Where:
- $r$ is the required after-tax return
- $delta$ is economic depreciation
- $tau$ is the corporate tax rate
- $z$ is the present value of cost-recovery deductions per dollar invested
Under full expensing, businesses set $z = 1$, which causes the formula to collapse into $c = r + delta$. In this idealized scenario, the tax rate ($tau$) disappears entirely from the equation, suggesting that taxes cannot distort investment decisions.
The Reality of "Sweat Equity" and Implicit Wages
However, the standard framework fails to capture the entirety of the real-world economic system. A glaring omission is the entrepreneurial contribution of founders who work for less than their market wage—accepting "implicit wages" or "sweat equity"—while building early-stage enterprises.
Because tax systems cannot easily price or provide deductions for unpaid entrepreneurial effort, the tax rate does not fully cancel out, even under full expensing. An extended user cost model incorporating an unexpensed founder opportunity cost ($omega$) reveals a dramatic divergence in required pre-tax returns when rates climb:
- Raising the business tax rate from 21 percent to 31 percent increases the required pre-tax return by a modest 6 percent.
- Raising the rate by the same 10 percentage points from 70 percent to 80 percent increases the required return by a staggering 31 percent.
This demonstrates that the marginal cost of raising taxes is relatively low when rates are moderate, but becomes exponentially destructive when rates are already elevated.
Furthermore, tax asymmetries—such as the delayed deductibility of losses for startups (notably, studies show 55 percent of venture-backed startups founded between 1985 and 2009 terminated at a loss)—mean that investment cost offsets are rarely symmetric with the taxation of gains. Progressive corporate rate structures further exacerbate these intertemporal distortions over a firm’s lifecycle.
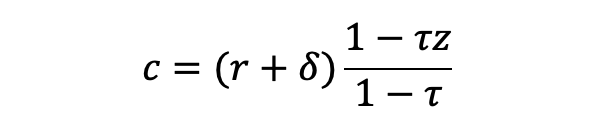
Official Responses and Expert Perspectives
The academic community remains deeply divided over the viability of pairing robust base reforms with punitive tax rates.
Proponents of high corporate rates, drawing inspiration from Avi-Yonah’s work, emphasize the necessity of capturing corporate "rents"—the supernormal returns generated by monopolies, cartels, and firms with immense pricing power. From this perspective, an 80 percent rate on global profits above $10 billion serves as an aggressive tool to curb corporate concentration and redistribute wealth without harming normal, productive capital investment.
Conversely, mainstream public finance economists and policy organizations, such as the Tax Foundation, push back vigorously against this narrative. They argue that admiration for pro-growth reforms like full expensing must not warp into economic complacency.
Critics emphasize that while destination-based cash flow taxes (DBCFT) and border adjustments successfully close profit-shifting channels, they do not immunize the economy against the dampening effects of confiscatory marginal tax rates. As empirical data shows, the economic penalty of tax rate hikes accelerates sharply at the upper margins, punishing entrepreneurship, innovation, and risk-taking.
Implications for Future Tax Policy
The debate sparked by "Taxation and Deglobalization" carries profound implications for the future of fiscal architecture in the United States and globally.
- The Promise of Base Reform: There is widespread consensus that moving toward a more resilient tax base—incorporating elements of full expensing, cash-flow taxation, and measures to curb profit shifting—is a net positive for economic productivity. These reforms successfully minimize administrative waste and reduce the sensitivity of capital to tax burdens.
- The Danger of Policy Overreach: The assertion that these base fixes provide a blank check for confiscatory tax rates is fundamentally flawed. Real-world complications, including uncompensated entrepreneurial labor, loss asymmetry, and progressive lifecycle distortions, ensure that tax rates always matter.
- Global Competitiveness in a Changing World: Even if deglobalization grants governments tighter control over domestic market access, excessively high corporate rates risk stifling domestic innovation. Startups and high-growth enterprises rely heavily on early-stage capital accumulation; imposing a punitive 80 percent rate on eventual success fundamentally alters the risk-reward calculus for founders and investors.
Ultimately, while lawmakers should continue pursuing pro-growth structural reforms to secure the tax base, treating those reforms as a shield against the heavy economic costs of exorbitant tax rates is a recipe for long-term stagnation.