By Gabrielle Saulsbery | Banking Dive
Published: October 7, 2026
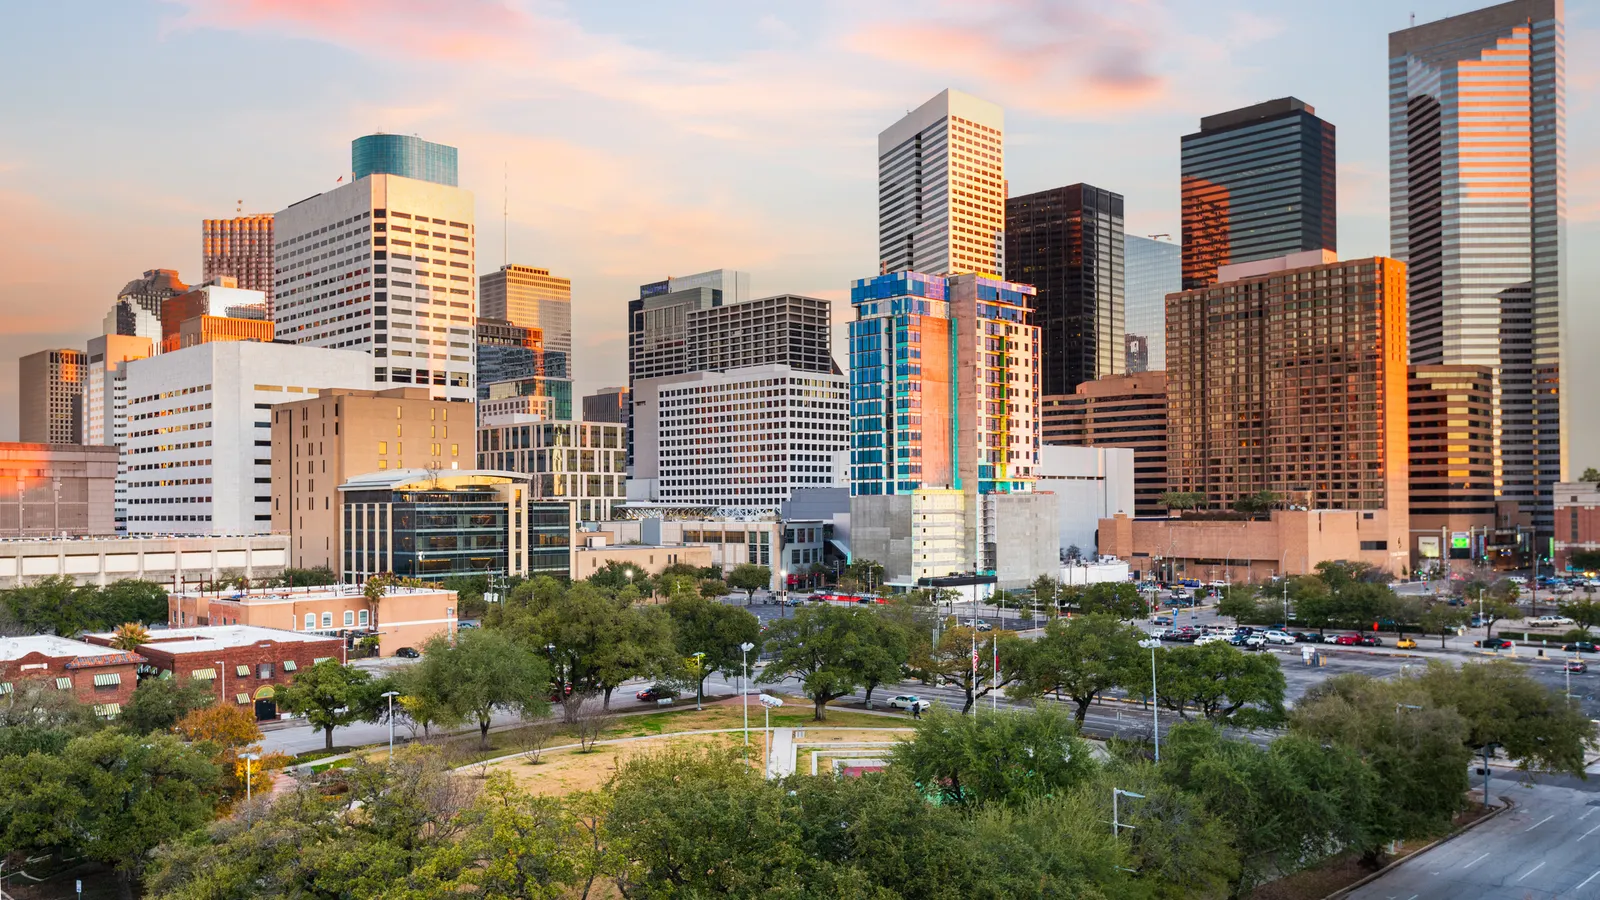
In a move that signals a continued consolidation trend within the regional banking sector, Houston-based Third Coast Bancshares announced today its definitive agreement to acquire Oklahoma-based Great Plains National Bank. This strategic merger marks a significant milestone for Third Coast, effectively expanding its geographical reach into the Oklahoma market while simultaneously deepening its presence in the highly competitive Dallas metropolitan area.
The transaction, which follows a period of aggressive growth for Third Coast, underscores the institution’s commitment to scaling its operations through targeted M&A activity. By integrating a centenarian institution like Great Plains into its corporate structure, Third Coast is positioning itself as a formidable player in the Southern banking landscape, balancing its established Texas roots with new, cross-state growth opportunities.
Main Facts: A Structural Overview
Under the terms of the merger agreement, the acquisition will be executed through a multi-step process. Third Coast’s wholly-owned subsidiary, Thunder Merger Sub, will first merge into Great Plains. In this exchange, Great Plains shareholders will receive common stock in Third Coast. Following this, Great Plains will be fully absorbed into Third Coast, and Great Plains National Bank will merge into the parent’s banking entity, Third Coast Bank.
Upon completion of the integration, the acquired institution will continue to operate under the "Great Plains Bank" name, functioning as a division of Third Coast Bank. This branding strategy aims to preserve the local identity and customer loyalty that Great Plains has cultivated over its 100-year history.
The ownership structure of the combined entity will reflect the relative sizes of the two institutions: Third Coast shareholders will maintain approximately 78% of the pro forma equity, while Great Plains shareholders will hold the remaining 22%. Furthermore, the governance of the organization will see a shift to reflect the new partnership, with two representatives from Great Plains being appointed to the boards of directors of both Third Coast and Third Coast Bank.
Chronology of Expansion
Third Coast Bancshares has demonstrated a clear, consistent appetite for growth. Today’s announcement arrives exactly one year after the company made headlines with its $123 million acquisition of Keystone Bancshares, based in Austin, Texas.
- February 2026: Third Coast officially closed its acquisition of Keystone Bancshares, a deal that significantly bolstered its footprint in the Texas capital.
- June 2026: Great Plains National Bank reported a robust balance sheet, showing $1.9 billion in assets, $1.7 billion in loans, and $1.7 billion in total deposits—figures that likely made it an attractive target for Third Coast’s expansion strategy.
- October 2026: Third Coast announces the definitive agreement to acquire Great Plains, marking its second major deal in less than 18 months.
This trajectory suggests a well-orchestrated roadmap, moving from securing the Austin market in early 2026 to targeting the Oklahoma and Dallas regions in the latter half of the year.
Supporting Data: The Scale of the Deal
To understand the significance of this acquisition, one must look at the data underpinning the merger. Great Plains National Bank brings a substantial portfolio to the table. With 23 branches spread across Oklahoma and Texas, the bank offers an immediate, established physical presence in a geography where Third Coast previously had limited reach.
The bank’s 2018 entry into the Dallas market via its acquisition of Liberty Federal Savings Bank remains a critical asset. By acquiring Great Plains, Third Coast effectively "acquires the acquisition," bypassing the lengthy organic process of establishing a new footprint in one of the most lucrative banking markets in the United States.
Financial analysts note that the integration of $1.9 billion in assets significantly inflates the scale of Third Coast’s balance sheet. The consolidation of deposit bases and loan portfolios is expected to yield operational efficiencies and enhance the combined entity’s lending capacity, allowing it to compete more effectively for larger commercial contracts that were previously out of reach.
Official Responses: The Leadership Perspective
The leadership teams at both institutions have framed the merger as a natural alignment of values and long-term goals.

"Together, we are creating a stronger organization with greater scale, expanded capabilities, and increased capacity to support our customers," said Bart Caraway, founder and CEO of Third Coast. "This combination will strengthen our ability to serve businesses and communities across our markets while creating long-term value for all stakeholders."
Mark Russell, CEO of Great Plains National Bank, emphasized the cultural fit of the two institutions. "Great Plains was built on the belief that strong relationships create strong communities. As we looked to the future, it was important to find a banking partner that shared that belief," Russell stated.
Russell is set to remain in a leadership role following the closure of the deal, ensuring continuity for Great Plains’ employees and clients. The inclusion of two Great Plains representatives on the board further solidifies the notion that this is a partnership intended to integrate rather than simply absorb.
Implications for the Future
The acquisition carries several implications for the regional banking sector and the future trajectory of Third Coast:
1. Market Diversification
By expanding into Oklahoma, Third Coast is successfully diversifying its geographic risk. While the Texas market remains a high-growth environment, the inclusion of Oklahoma provides a hedge against potential regional economic fluctuations within the Lone Star State.
2. Competitive Edge in Dallas
The Dallas-Fort Worth metroplex is a battlefield for regional and national banks. By absorbing Great Plains, Third Coast gains an immediate foothold in this market, supported by an existing client base and local expertise. This move forces competitors to acknowledge Third Coast as a growing regional power rather than just a Houston-centric institution.

3. Operational Synergy
The transition to a division model allows for "back-office" consolidation while maintaining "front-end" customer relationships. By merging the banks into a single charter while keeping the Great Plains brand, Third Coast can realize cost-saving synergies in compliance, technology, and administration without alienating the customer base that has been loyal to Great Plains for decades.
4. The M&A "Playbook"
Third Coast’s recent history serves as a blueprint for mid-sized banks looking to scale. By systematically identifying well-capitalized, community-focused targets, they are building a network that prioritizes "relationship banking"—a term frequently cited by leadership in their press releases. This strategy relies on the premise that in an increasingly digital world, the "human element" of local, community-focused leadership remains a differentiator.
5. Regulatory and Economic Outlook
As the financial industry faces ongoing scrutiny regarding interest rate environments and credit quality, this merger signals confidence. Both boards appear to believe that the combined entity will be better positioned to weather interest rate volatility and capitalize on lending opportunities than either bank would have been independently.
Conclusion
The acquisition of Great Plains National Bank is more than a simple expansion; it is a calculated effort by Third Coast Bancshares to transition from a regional player to a dominant force in the South-Central United States. With the closing of the Keystone deal earlier this year and the imminent absorption of Great Plains, Third Coast is clearly executing a vision of controlled, aggressive growth.
As the banking industry continues to consolidate in the face of digital transformation and economic headwinds, the success of this integration will be closely watched by investors and competitors alike. If Third Coast can successfully blend its operational efficiencies with the local, relationship-driven culture of Great Plains, the move will likely be viewed as a masterstroke in regional banking strategy.